Trade Fact of the Week: Florida’s sea turtle nest counts are growing

FACT:

Florida’s sea turtle nest counts are growing.


THE NUMBERS: 

Average counts of green turtle nests at 27 Florida “core index beaches,” two-year average*

2020-2021    ~23,000 nests
2010-2011     ~10,000 nests
2000-2001    ~4,000 nests
1990-1991      ~1,000 nests

* Florida Wildlife Commission; using two-year averages as green turtle nesting totals appear to vary in a two-year cycle.  These are not total statewide (or U.S.) nesting estimates; they are counts of nesting at 27 long-studied beaches, representing about 10% of the known Florida nesting beaches.

WHAT THEY MEAN:

Here’s a good idea:  Somewhere around 320 B.C., proto-conservationist Mencius offers King Hui of Liang (near present-day Kaifeng) a simple solution to a complex problem:

“If you ban nets with fine mesh from ponds, there will be more fish and turtles than the people can eat.  If you ban axes from the forests on the hillsides except in the proper season, there will be more timber than the people can use.”  

Twenty-three centuries later, and in the ocean rather than in ponds, all seven sea turtle species are “endangered,” “threatened,” or “critically endangered.” As large, armored reptiles with few natural predators, these turtles are very tough. Their nesting season this summer will be roughly the 150 millionth; the series has outlasted not only the last seven ice ages, but the end-of-Cretaceous asteroid that wiped out their early contemporaries the ammonite and the plesiosaur.

But maybe they are no longer tough enough. Some are caught and traded for shell jewelry.  Many more fall victim to “by-catch,” as shrimp and fishing fleets suck them into bag-shaped shrimp trawl nets or catch them on long lines meant for shark and tuna.  And many more, with beach erosion and harvesting of nests for eggs, never hatch at all.  This series of losses accelerated in the mid-20th century; to take one example, the global estimate of nesting leatherback females done by the International Union for the Conservation of Nature dropped from about 90,000 in 1980 to 54,000 in 2010.

How to respond?  Sea turtle protection in the United States may, tentatively, be succeeding, with a mix of three measures:

(1)    Trade restriction:  The 184 countries and territories in the Convention on International Trade in Endangered Species, the world’s first international trade-and-environment agreement, listed all sea turtles in ‘Appendix I,’ in the 1980s, banning trade in turtle jewelry and other products.

(2)    By-catch reduction:  To reduce by-catch, the United States in 1987 banned sale or import of shrimp caught by boats which do not use Turtle Excluder Devices or “TEDs.”  These are barred metal grills — something like the wide meshes like those Mencius recommended for fishnets in ponds — placed in the neck of the bag-shaped shrimp nets to let mistakenly captured turtles swim out.  They cost about $375.  Each summer, the State Department publishes a list of countries which, through compliance with this rule, can export ocean-caught shrimp to the U.S.  The most recent certifies 41 countries and territories as “equivalent” to the U.S. in turtle protection, and thus able to export wild-caught shrimp to the United States.

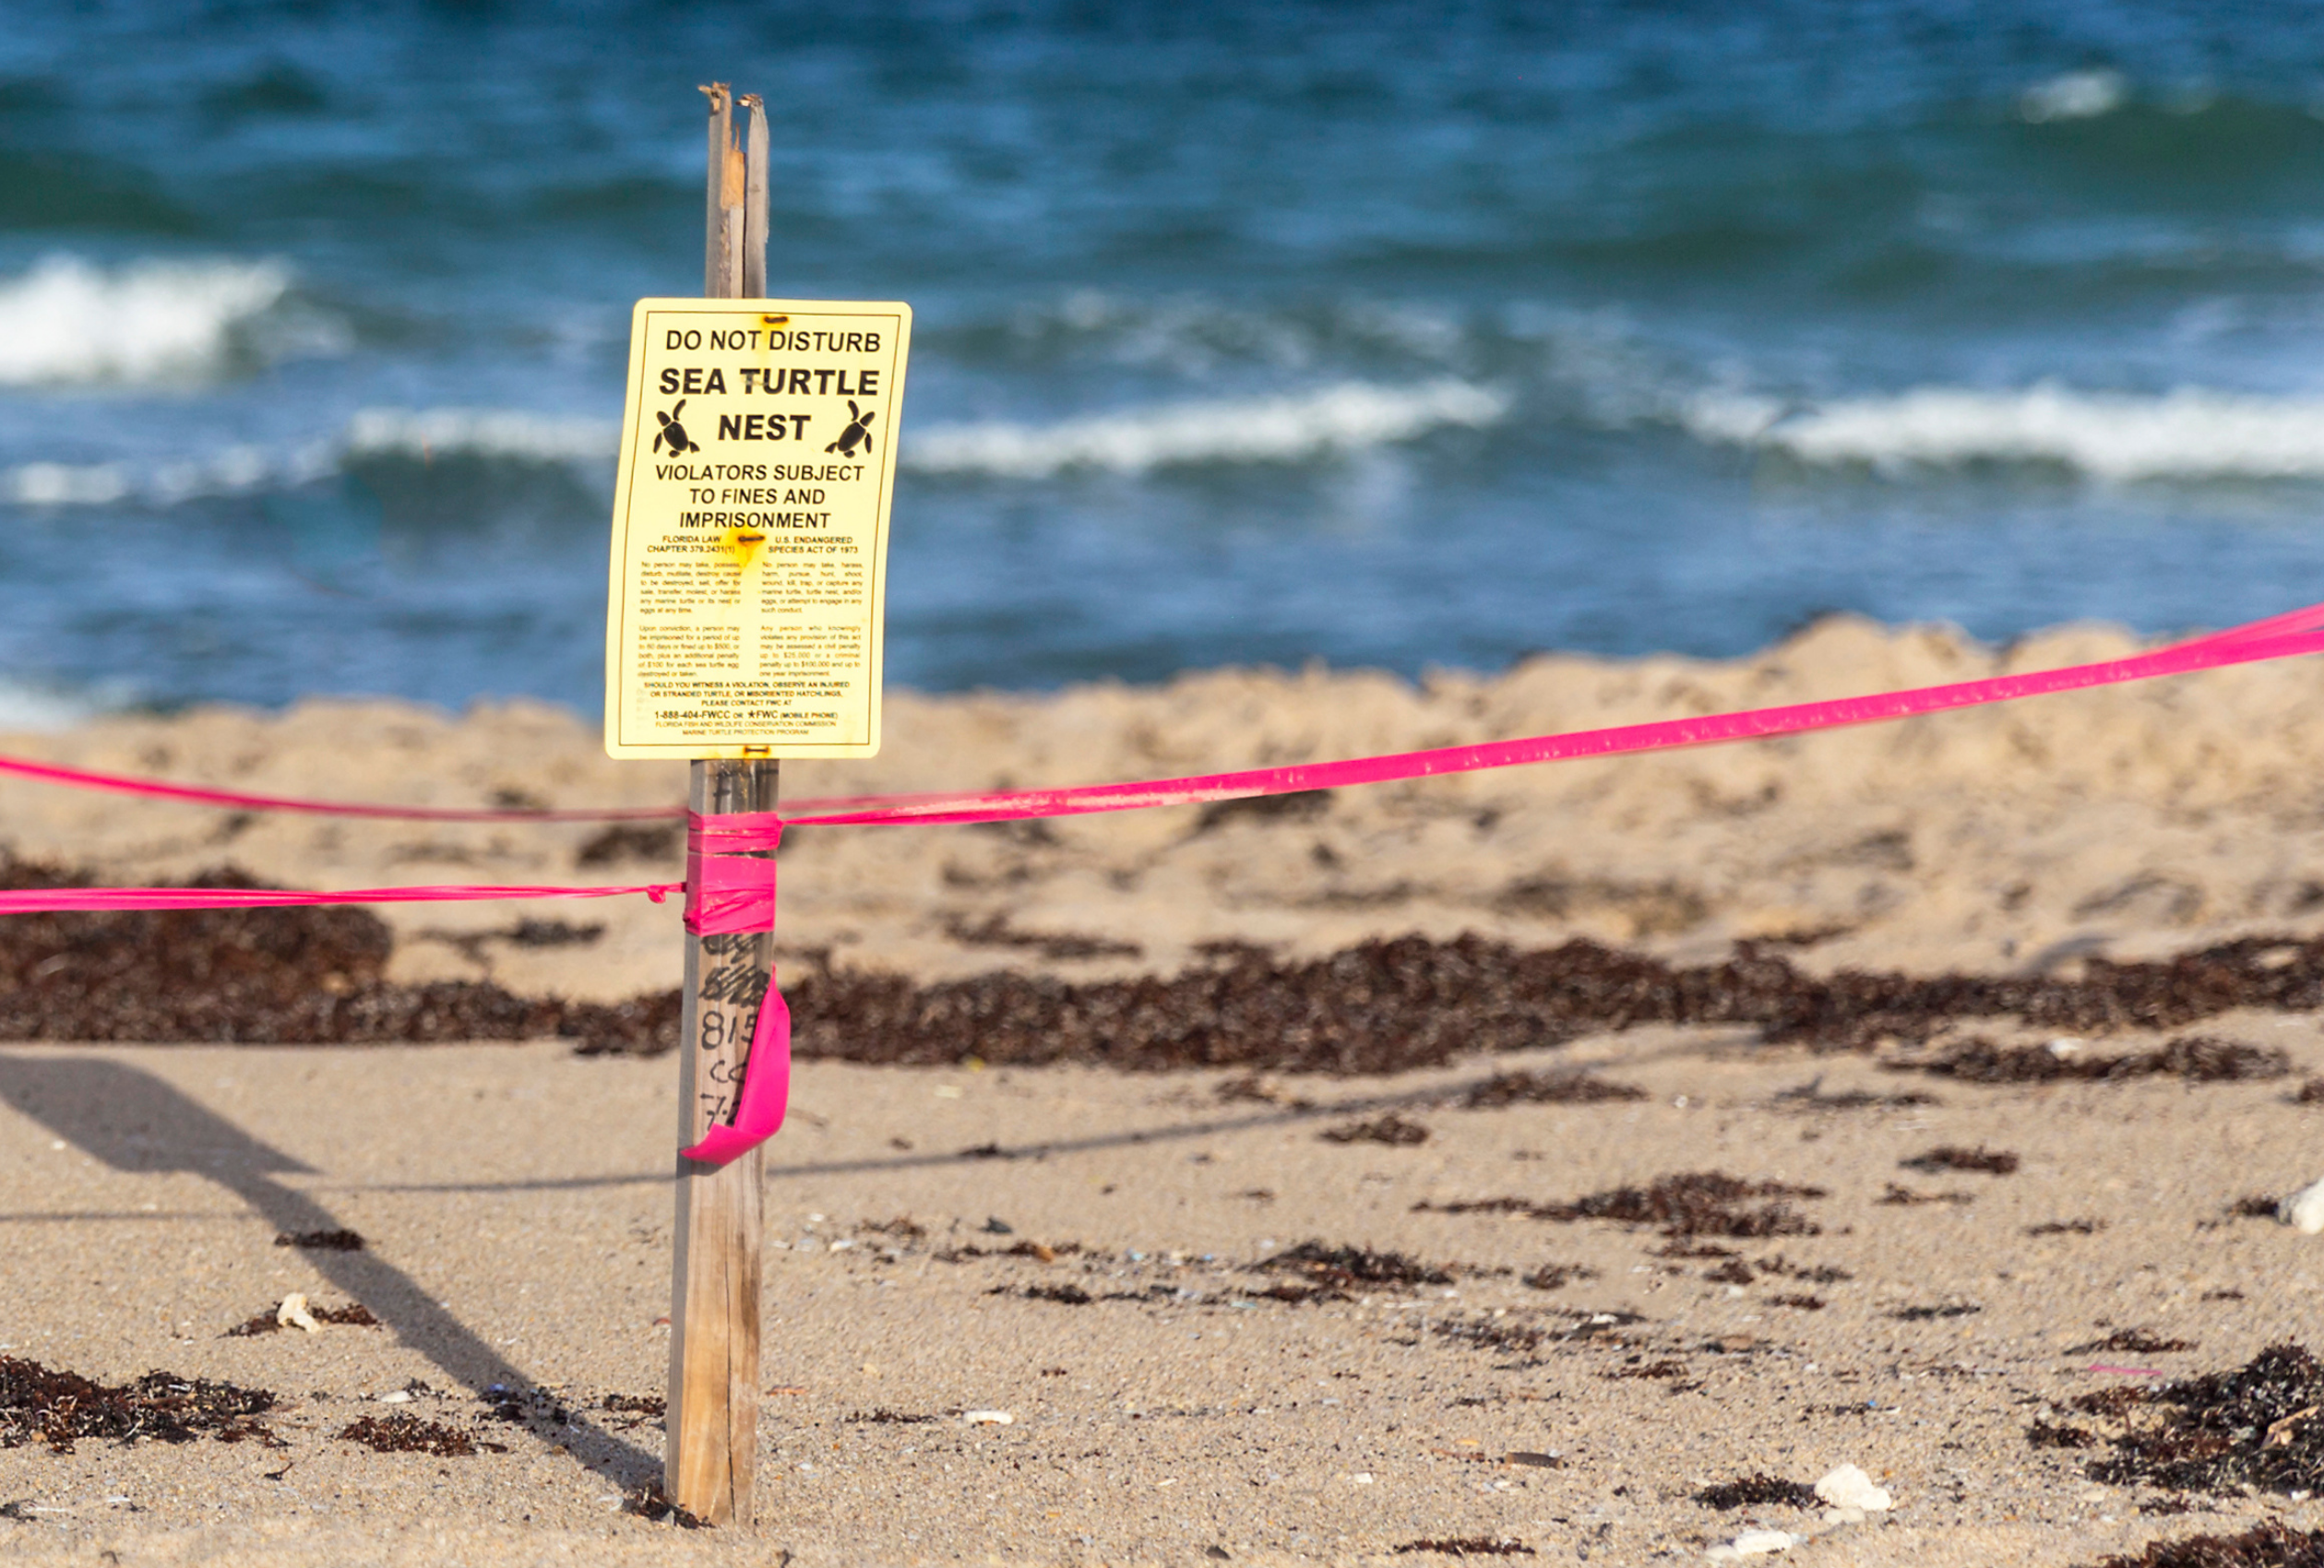
(3)    Beach protection:  National and state laws, and local regulations set aside beaches for nesting, and limit their use.  As an example, Florida’s Marine Turtle Conservation Act (passed in 1991 under then-Gov. Lawton Chiles) bars over-building, lighting schemes that can disorient hatchlings in season, and disruption of nesting by tourists.

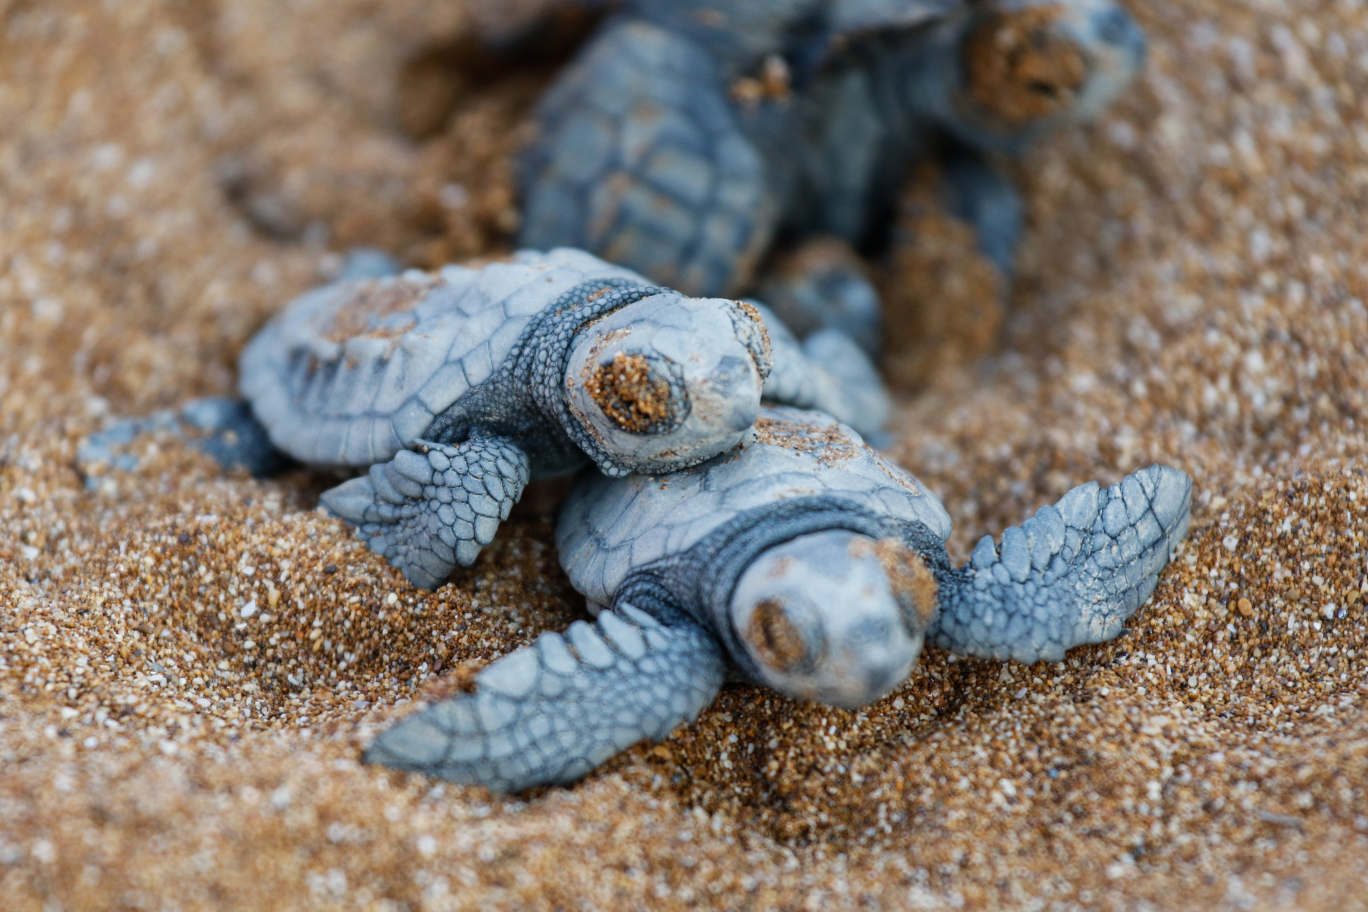
Does it work?  Tentatively, yes.  Florida’s green turtle population is a case in point:  while totals vary up and down each year, Florida Wildlife Commission figures shows about 20 times as many nests in the 2020/2021 season as there were in the early 190s, when the national TED and Florida beach protection laws began.  Kemp’s Ridley turtle nesting levels (almost exclusively on a single stretch of Mexican beach, though with outposts in Texas and Cape Hatteras) are up from a near-extinction low of 200 in the 1980s to about 5000 a decade ago, and perhaps as many as 20,000 in 2020.  On a larger scale, the International Union for the Conservation of Nature’s estimate of leatherback nesting females has risen from 54,000 in 2010 to 64,000 as of 2020, and looks ahead under current population trends (driven by strong growth in Atlantic populations) to 79,000-110,000 by 2040.

Just a start, of course.  Hardly Mencius’ “more than you can eat”; and (as an example) the IUCN’s optimistic take on Atlantic leatherbacks is offset by continuing Pacific leatherback decline.  And apparently positive trends remain open to newer questions about rising ocean temperatures, acidification, plastics accumulation, and beach erosion as sea levels rise.  But this said, a promising start and some validation for Mencius’ rather old, still simple, and still good idea.

FURTHER READING


The Florida Wildlife Commission reports on nesting totals for five turtle species at “index beaches” from 1989 forward.

A worried World Wildlife Fund fact-sheet.

The IUCN has assessments for all seven sea turtle species; optimistic projections for the leatherback here.

Reports from:

Florida: UCF ponders growth in small-turtle nesting.

… and Fort Myers explains beach lighting rules in the May to October nesting season.

Hawaii: NOAA’s Pacific Islands office on hawksbills in Hawaii.

Texas: The National Park Service on Kemp’s Ridley nesting.

Australia: Australia’s Department of Agriculture, Water, and the Environment on flatback turtle conservation.

Oman: The Oman Times reports on green turtle nesting and tourism at Ras al-Hadd in Oman (certified as U.S.-equivalent in turtle protection).

Belize: Oceana reports on hawskbills.

Policy

The State Department announces 2021 shrimp trade certifications: Oman, Australia, Belize joined by Bahamas, Malaysia, Fiji, et al.

The CITES (Convention on the International Trade in Endangered Species) homepage.

Sea turtle protection page from the National Oceanic and Atmospheric Administration.

Litigation

A famous WTO dispute of the 1990s, “DS-58”, wound up validating the U.S. TED rule against complaints.

And last…

Mencius, with the brief passage on nets, excluder devices and turtles in Chapter A3.

In A New Voyage Round the World (1699), English professional navigator, part-time pirate, and amateur naturalist William Dampier discusses the massive Caribbean green turtle populations of the 17th century:

“I heard of a monstrous green turtle once taken at Port Royal in the Bay of Campeachy that was four foot deep from the back to the belly, and the belly six foot broad.  Captain Roch’s son, of about nine or ten years of age, went in it as in a boat on board his father’s ship, about a quarter mile from the shore.  … One thing is very strange and remarkable in these Creatures; that in the breeding-time they leave for two or three months their common Haunts, where they feed most of the year, and resort to other places only to lay their Eggs: and ‘tis not thought that they eat any thing during this Season: so both the He’s and the She’s grow very lean. … Altho’ multitudes of Turtles go from their common places of feeding and abode, to those laying eggs:  and at the time the Turtle resort to these places to lay their Eggs, they are accompanied by abundance of Fish, especially Sharks; the places that the Turtle then leave being at that time destitute of Fish, which follow the Turtle.”

Dampier’s New Voyage, with the turtle passage in Chapter 5.

ABOUT ED

Ed Gresser is Vice President and Director for Trade and Global Markets at PPI.

Ed returns to PPI after working for the think tank from 2001-2011. He most recently served as the Assistant U.S. Trade Representative for Trade Policy and Economics at the Office of the United States Trade Representative (USTR). In this position, he led USTR’s economic research unit from 2015-2021, and chaired the 21-agency Trade Policy Staff Committee.

Ed began his career on Capitol Hill before serving USTR as Policy Advisor to USTR Charlene Barshefsky from 1998 to 2001. He then led PPI’s Trade and Global Markets Project from 2001 to 2011. After PPI, he co-founded and directed the independent think tank ProgressiveEconomy until rejoining USTR in 2015. In 2013, the Washington International Trade Association presented him with its Lighthouse Award, awarded annually to an individual or group for significant contributions to trade policy.

Ed is the author of Freedom from Want: American Liberalism and the Global Economy (2007).  He has published in a variety of journals and newspapers, and his research has been cited by leading academics and international organizations including the WTO, World Bank, and International Monetary Fund. He is a graduate of Stanford University and holds a Master’s Degree in International Affairs from Columbia Universities and a certificate from the Averell Harriman Institute for Advanced Study of the Soviet Union.

Read the full email and sign up for the Trade Fact of the Week

Targeting App Stores Reduces Consumer Choice in the Market for Mobile Devices

A bipartisan group of legislators is looking to improve competition within app stores and lower barriers to entry for developers in the market for mobile apps, though the reality of the bill’s impact is decidedly less clear. The Open App Markets Act would require that companies — namely Google and Apple — allow applications to be downloaded onto their operating systems from sources other than their respective app stores in a process known as sideloading. The bill also prohibits companies from requiring that apps facilitate in-app transactions through an operating system’s own payment mechanisms — an issue that took center stage in the 2020 lawsuit in which Epic Games sought to bypass the 30% revenue cut taken by Apple’s app store by implementing an external payment process. While the intention may be to promote competition, this bill misrepresents current industry standards by targeting practices of two major companies which are commonplace among competitors. The consequences of this action will fall on consumers, who will lose the ability to choose preferred methods of obtaining mobile apps by forcing identical business models between competing companies.

Approximately 85% of apps listed on the Apple App Store do not charge consumers or enable in-app purchases of any kind, meaning the commission fees for which this bill seeks to provide alternatives are irrelevant to the vast majority of developers utilizing the marketplace. Because of this, the 1.8 million apps available on Apple’s platform can reach billions of iOS users worldwide at a low cost. However, for those which do enable transactions — many of which operate within the realm of mobile games similar to those offered by Epic — the fees imposed by the Apple and Google app stores both currently operate at or below levels consistent with the standard set by the market. Apple and Google both collect 30% commission on digital goods and services and both implement a model where fees on subscriptions fall to 15% after a year. Both companies also lower fees to 15% for developers making under $1 million in revenue in order to lower barriers to entry for small developers. This is on par with the 30% fee charged by the Samsung Galaxy Store, Amazon App Store, and gaming platforms such as the Microsoft Store on Xbox consoles and the PC gaming store Steam.

In addition to disrupting current industry standards, efforts targeting Apple and Google’s app stores disregard the impact the bill will have on consumer choice in the market for mobile devices. Sideloading apps from sources other than Apple and Google’s approved listings is a useful feature for those who want to customize their devices and maintain a higher level of control over software installed, but there are significant security risks associated with doing so which are left unacknowledged by the Senate legislation. Google’s Android operating system currently allows users to enable the ability to sideload apps from unknown sources, but users doing so assume the risks associated with downloading untested software, potentially exposing their devices to malware. App store review processes are in place to ensure that apps work as intended and do not pose harm to users prior to becoming available to consumers. When sideloading, users have a limited amount of information about the applications source and content, and if the app has not been through the approval processes needed to list an app on a major app store, it is all too easy to misrepresent the content of the app, exposing consumers to potentially dangerous applications. This risk is heightened on any app which requires transactions, as payment information can be easily compromised by unknown third parties when operating outside an operating system’s payment platform. In 2020, Apple’s app review process rejected more than 48,000 apps containing hidden content or undocumented features, as well as 215,000 for privacy concerns, which Apple says saved consumers more than $1.5 billion in fraudulent transactions.

Despite the risks, the autonomy that comes with the Android model is a draw for many consumers as they choose between competing mobile operating systems. For the more tech-savvy consumer, security risks can be mitigated by the ability to make informed choices, and the results can be an enhanced level of functionality on mobile devices which are therefore customized to meet the needs of the individual user. But the average consumer may not want to weigh the benefits and risks of every download they make. App stores which are designed for the specific operating system ensure a level of security, and the payment systems used make it so that financial information is not compromised by exposure to unknown third parties. By requiring that Apple follow the lead of Google and enable sideloading on their devices, consumers lose the option to take advantage of this ensured security and will be open to malware — a practice which Apple has reported results in Android devices having an estimated 15 to 47 times more infections from malicious software compared to their iOS counterparts.

A common critique of this bill is that by targeting only two major companies, the Senate is artificially deciding winners and losers in a market where competition is already present. By manipulating the market to require identical business models by leading app stores, this critique appears especially salient. The assurance of safeguards for privacy and security is a feature of Apple products, and if a consumer feels confident in their ability to monitor their own security risks when downloading unapproved applications from third-party sources, switching costs to another operating system are relatively low from an antitrust perspective. It is thus not the role of Congress to regulate what is considered an ideal business model in areas where innovation and competition are present, particularly when that regulation exposes the everyday consumer to significant security risks.

RAS REPORTS: Celebrating National School Choice Week

In this week’s episode of RAS Reports, Curtis Valentine and Tressa Pankovits, Co-Directors of PPI’s Reinventing America’s Schools Project, celebrate National School Choice Week by discussing new developments in the movement to provide access to affordable, quality education to all of America’s youth. The hosts highlight Innovation Schools in Indianapolis, IN which serve as a prime example of the benefits of granting schools the flexibility to make decisions tailored to the specific needs of their student body. Curtis and Tressa discuss how these “schools of choice” attract high-quality teachers, produce higher learning outcomes, and gives parents more power to decide what educational environment is best for their student.

Learn more about the Reinventing America’s Schools Project here. 

Learn more about the Progressive Policy Institute here.

PPI’s Mosaic Economic Project Statement on Biden’s Federal Reserve Nominations

Jasmine Stoughton, Program Lead for the Mosaic Economic Project at the Progressive Policy Institute (PPI), released the following response in reaction to Biden’s Federal Reserve Nominations:

“President Biden’s nomination of the Hon. Sarah Bloom RaskinDr. Lisa Cook, and Dr. Philip Jefferson to the Board of Governors of the Federal Reserve System is a key step toward ensuring stable economic growth that will be felt by every American, and it is a demonstration of Biden’s commitment to uplift leaders that reflect the diversity of our country.

“Raskin, Cook, and Jefferson are well-respected and highly qualified to serve on the Board. Combined, they have decades of experience in academia and government and have each shown extraordinary judgement and skill throughout their careers.

“Diversity in leadership is among the most important elements of successful governance. If the Senate confirms Biden’s nominations, the complete Board will be majority women for the first time in its 108-year history. Incredibly, Cook will be the first Black woman to serve on the Board, and Jefferson will be the fifth Black governor — representation that is long overdue.”

The Mosaic Economic Project is a network of diverse women with expertise in the fields of economics and technology. Mosaic programming aims to bring new voices to the policy arena by connecting cohort members with opportunities to engage with top industry leaders, lawmakers, and the media.

The Progressive Policy Institute (PPI) is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock. Learn more about PPI by visiting progressivepolicy.org.

Follow the Progressive Policy Institute.

Follow the Mosaic Economic Project.

###

Media Contact: Aaron White – awhite@ppionline.org

PPI Statement on Historic Federal Reserve Nominations

The Progressive Policy Institute (PPI) released the following statements ahead of the Senate Banking Committee’s hearing on the nominations of the Hon. Sarah Bloom RaskinDr. Lisa Cook, and Dr. Philip Jefferson for the Board of Governors of the Federal Reserve System:

“President Biden has overseen a year of remarkable achievement in restoring economic growth, with steady job creation and strong evidence of wage increases. With the economy stabilized after the COVID-19 pandemic experience but concerns about inflation rising, the country needs both professional management and imaginative policy in the coming years,” said Ed Gresser, Vice President and Director of Trade and Global Markets for PPI.

“President Biden’s excellent nominations for the Federal Reserve Board of Governors demonstrate his awareness of this challenge. The current chair and nominee for vice chair, Jerome Powell and Lael Brainard, are exceptional public servants who have helped to steer the Fed through the turbulence of the Trump years and the COVID crisis, and fully merit confirmation. New nominees Lisa Cook, Sarah Bloom Raskin, and Phillip Jefferson are outstanding economists who will bring a diversity of strengths and experience to the Fed, with its dual mandate of price stability and full employment, and will help ensure that the Board of Governors takes its next steps with consideration for both macroeconomic consequences and impacts on Americans at all income levels and in all walks of life. This is a very strong group of nominees which will serve the country well during a very complex time, and deserves support,” concluded Gresser.

“The Progressive Policy Institute applauds President Biden and the Biden-Harris administration for this historic, diverse, and highly qualified slate of nominees to the Board of Governors of the Federal Reserve. At a time when our nation faces several economic challenges — caused primarily by the COVID-19 pandemic and evolving variants — this group will bring steady, competent leadership. America is getting back on track after an unimaginable health and economic crisis, and President Biden is proving his commitment to Build Back Better by prioritizing strong leadership in every facet of the federal government,” said Sarah Paden, Vice President and National Political Director.

The Progressive Policy Institute (PPI) is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock. Learn more about PPI by visiting progressivepolicy.org.

Follow the Progressive Policy Institute.

###

Media Contact: Aaron White; awhite@ppionline.org

Among Swing Voters, Inflation and Health Care Costs are Top of Mind

The high cost of health care has been at or near the top of voters’ concerns in recent election cycles. According to a series of focus groups with swing voters commissioned recently by the Progressive Policy Institute (PPI), high prices for everything are now their chief worry, with the issue of inflation and the high cost of health care being raised unprompted in every listening session.

Nonetheless, these voters aren’t demanding radical or systemic change in America’s health care system. They mostly expressed satisfaction with their current health insurance, as well as the outcomes of their own interactions with their health care providers. They have little knowledge about proposals in Washington aimed at lowering medical and drug costs.

“What these pivotal voters want most are simple, direct, and concrete actions that help them lower their medical and drug bills,” said PPI President Will Marshall. “For example, they strongly favored PPI’s proposal for capping out-of-pocket costs for prescription drugs.”

Conducted by IMPACT Research (formerly ALG Research), the focus groups took a deep dive into all aspects of health care. They consisted of five diverse groups of swing voters — senior men in Philadelphia and college educated suburban women in Pittsburgh, Pennsylvania; Latino men and college educated suburban women in Arizona; and college educated men in Georgia and Black women in Georgia.

Here are key takeaways from IMPACT Research’s report:

    1. Inflation is the most top of mind issue to these voters and they are especially sensitive to any cost increases in their daily lives, health care included. Most are acutely aware that their health care costs have risen unabated year after year.
    2. They don’t dislike their current insurance and have very positive things to say about their own point-of-care experiences. Their concerns about cost aren’t enough for them to want to swap the current system for something similar to the nationalized health care systems in Canada or England.
    3. Neither party is trusted to bring down health care costs. Although Democrats have taken the lead in Washington on health cost containment, even Democrats in these groups don’t give the party any credit for these efforts because they don’t see their medical bills going down.
    4. None of the participants had any real knowledge of or strong preferences for reforms or policy solutions under debate in Washington to bring down health care or prescription costs. This includes allowing Medicare to negotiate drug pricing, which many assume already happens.
    5. What they are looking for are concrete ways to help lower out-of-pocket costs their insurance doesn’t cover. They enthusiastically favor a direct approach — capping out-of-pocket prescription costs as a percent of income or total annual expenses.
    6. They are less interested in indirect measures to control the costs of care and prescriptions, or wholesale change that compromises the quality, choice, and access that to them defines the American health care system. Some voters are also wary of too-harsh restrictions that could results in less innovation which they see as a positive attribute of our current system.


Read the full brief here.

The Progressive Policy Institute (PPI) is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock. Learn more about PPI by visiting progressivepolicy.org.

Follow the Progressive Policy Institute.

###

 Media Contact: Aaron White; awhite@ppionline.org

The America COMPETES Act Rightly Prioritizes Technological Innovation to Drive Growth

As the United States engages in what the Biden administration has referred to as “strategic competition” with China over economic leadership, a newly released House bill seeks to secure America’s role on the global stage by promoting technological innovation. The America COMPETES Act both stimulates investment in research and revitalizes industrial capabilities in the American technology sector. From funding research in new network technologies to eliminating green card caps for recipients of doctoral degrees in STEM fields, the bill acknowledges that the key to facilitating long term economic growth is investment in scientific development. It is promising to see Democrats encourage innovation as a driver of growth and, while not perfect, the bill provides much needed resources to address numerous areas where the American economy has fallen behind.

Over the past two decades, American domestic expenditure on research and development as a share of GDP has risen only slightly while other major economic rivals have experienced significant gains. In 2003, American investment in R&D made up approximately 2.6% of gross domestic product, compared to 3.1% in 2019. Over the same period, China and South Korea effectively doubled their own R&D spending as a share of GDP, with South Korea boasting 4.6% of GDP being attributed to R&D spending compared to 2.3% in 2003, and China seeing an increase from 1.1% to 2.2%. Additionally, between 2012 and 2021, the Chinese government made significant investments into higher education, increasing the number of PhD graduates in the country by 40%. To keep up, it is essential for the U.S. to support STEM programs at every level of education, from K-12 to those pursuing advanced degrees. The House seeks to accomplish this with this bill, prioritizing research across STEM fields to facilitate purpose-driven R&D to address pressing societal challenges such as environmental sustainability, while also supporting a new generation of teachers, researchers and professionals trained in STEM. These are worthy investments in domestic talent which can drive long run growth.

Another notable aspect of the bill is the focus on domestic manufacturing of tech-sector inputs, such as microchips, to address shortages of input goods which currently threaten to interrupt production of products such as cars, medical equipment, and consumer tech devices. Included is an allocated $52 billion to support the domestic production of semiconductors, a product market which has faced shortages heavily exacerbated by the ongoing pandemic. The Department of Commerce reported this week that demand for chips increased 17% from 2019 to 2021 with no comparable increase in supply. In 2019, buyers of semiconductor products had a median inventory of 40 days, compared to just five days in 2021 — meaning a week-long disruption in the supply chain has the potential to cripple high-tech industries reliant on microchips the short term, an especially daunting threat in the era of pandemic shutdowns. The Department of Commerce found that a driving force behind the issue was a lack of production capacity, and with the U.S. currently accounting for just 12% of global production. Funding to expand this has the potential to go a long way in addressing supply shortages while also opening new opportunities for domestic production and trade.

The bill enjoys wide support among House Democrats as well as President Biden, who applauded the bipartisan effort to promote America’s ability to compete in the global economy. The Senate version — the United States Innovation and Competition Act — passed with 68 votes in May of 2021, highlighting the bipartisan nature of the issue.

However, one controversial difference between the House and Senate bills as they impact the American tech sector is the inclusion of the SHOP SAFE Act in the House bill. The SHOP SAFE Act was introduced last September and sought to reduce the prevalence of counterfeit products sold online by imposing legal liability on e-commerce platforms for the sale of counterfeit goods. However, because many e-commerce platforms rely on the presence of third-party sellers, this would force small and large platforms to scrutinize even the smallest sellers to avoid penalties. This well-intentioned provision will likely hurt smaller e-commerce platforms who lack the tools to moderate listings on their sites to the level required to avoid penalty. Companies are given avenues to avoid liability if moderation procedures for listings follow certain practices, but the vague standard given will make it difficult for smaller platforms to compete with large e-commerce sites which can do so effectively at a relatively low cost. While much of the bill promotes the American technology industry’s ability to compete, this type of penalty will undermine the ability for U.S. companies to compete with Chinese giants such as Alibaba in the e-commerce space, running counter to the legislations intended purpose.

Ultimately, the America COMPETES Act has the potential to spur long term growth through significant investment in scientific innovation and emerging technology. Though imperfect, the sentiment behind the bill is a positive one. The American technology sector has long been a leading global innovator and by investing in the future of the industry Congress can promote both global competition and a robust domestic economy driven by new technologies.

Marshall for The Hill: How Biden Can Get His Presidency Back on Course

By Will Marshall

President Biden’s fall from political grace has been swift and steep. He began 2021 basking in the gratitude and approval of a solid majority of Americans and ended it only marginally less unpopular than former President Donald Trump.

What happened? Last week Biden blamed Republican obstructionism, marveling that not one voted for the $1.9 trillion bill Congress passed last March to fight the pandemic and speed the economic recovery. He’s also had to endure non-stop political sabotage by Trump, who in refusing to accept the voters’ thumbs down in 2020 has shredded yet another vital norm of American democracy.

Nonetheless, the White House missed an important opportunity in not making more of the president’s big bipartisan breakthrough — passing the first major infrastructure bill in decades. Instead, they attempted to use it as leverage in an unsuccessful bid to pressure dissident Senate Democrats into supporting the strictly partisan reconciliation bill.

Read the full piece in The Hill.

Trade Fact of the Week: Energy accounts for 3/5 of Russian exports

FACT:

Energy accounts for 3/5 of Russian exports.


THE NUMBERS: 

Russia GDP (IMF estimates, currency-basis) 

2021    $1.7 trillion
2016    $1.3 trillion
2013    $2.3 trillion
2009    $1.3 trillion


WHAT THEY MEAN:

Most economies “grow” incrementally and undramatically (with occasional incremental dips in recessions).  Through productivity growth, investment, and slight rises in the populations of consumers and workers, they steadily add a couple of percentage points each year.  The Russian economy looks different: More like an inflating and deflating bellows, nearly doubling in size from 2009 to 2013, then contracting by nearly half over the next three years, and since 2016 another burst of growth.

Why?  The pattern reflects Russia’s exceptionally high dependence on energy production and energy sales.  According to the WTO’s Trade Profiles 2021, an annual country-by-country summary of imports, exports, partners and balances for 197 countries, “fuels and mining products” accounted for 59% of Russian exports in 2020.  This figure is quite large — among developed economies, only Norway’s is higher — and likely understates the actual role of energy in Russian trade.  The WTO lists Russia’s top four exports in 2020 as:

Crude oil, $122 billion;
Refined petroleum products, $67 billion;
Coal, $16 billion; and
Natural gas, $10 billion.

These four products combine for $215 billion, or 65% of $332 billion in total Russian goods exports that year, with the “refined petroleum products” category, presumably including include some goods classified as manufactures rather than primary “fuels and mining” products.  Overall, Russia was the world’s second-ranking exporter of these goods; the U.S. ranked second, but with energy making up a much smaller 15% of the U.S.’ $1.4 trillion in exports.

Two frequent consequences of this level of dependence on energy sales:

(1)    Countries this reliant on energy and metal ore exports are economically volatile — they boom when world prices rise and crash when prices fall — unless they have especially sophisticated ways of banking excess resource rents in good years.  Thus the odd pattern of Russian GDP.  With large shares of GDP and government revenue coming through a small group of companies and individuals, they also frequently (though again not always) develop political systems centralized around a few government officials and top executives of state or quasi-private enterprises.  The Russian examples are Gazprom, Rosneft, Lukoil, and a few similar organizations.

(2)    Their customers need to diversify sources, so as to avoid reliance on potentially unstable partners.  Paul Bledsoe examines this question in PPI’s most recent energy and climate paper, reviewing the implications of Western and Central European reliance on Russian natural gas for heating and electricity.  He suggests an important place for the United States as an alternative source for European energy needs:

“New sources of gas, including liquefied natural gas (LNG) imports from the United States and other clean sources, can reduce the EU’s reliance on methane-heavy Russian gas. But of course, that will require the United States and other exporters to drive down methane and carbon dioxide emissions from the lifecycle as close to zero as possible, and verify their reductions with credible methodologies.  Moreover, the geopolitical costs of Russian gas continue to plague the EU broadly, and Ukraine and other Eastern European nations specifically. EU imports of Russian gas have actually increased since Moscow’s illegal annexation of the Crimea in 2015. Over time, limiting Russian gas imports thus could diminish its political leverage over Europe while also helping the EU achieve its climate goals.”


Don’t miss this PPI report by Paul Bledsoe

The report covers natural gas, Atlantic economics, and European security. Read it below:


FURTHER READING

Read PPI’s Bledsoe on natural gas, Atlantic economics, and European security here.

And read this from PPI President Will Marshall on the Biden administration, Putinist threats, and re-anchoring American foreign policy in liberal and democratic values.

Data 

The World Bank’s Russia Economic Report can be found here.

The WTO’s World Trade Profiles has exports/imports/partners by country for 197 economies can be found here.

Background reading

Anna Politkovskaya’s essay collection “Putin’s Russia: Life in a Failing Democracy,” on Russian life and politics circa 2005:

The State Department’s European and Eurasian Affairs Bureau can be found here.

The European Union is Russia’s main trading partner, buying 41% of Russian exports and providing 34% of Russian imports in 2020. Read about the EU’s Moscow mission.

The Ukrainian Embassy in D.C., can be found here.

Read about Russian gas giant Gazprom.


ABOUT ED

Ed Gresser is Vice President and Director for Trade and Global Markets at PPI.

Ed returns to PPI after working for the think tank from 2001-2011. He most recently served as the Assistant U.S. Trade Representative for Trade Policy and Economics at the Office of the United States Trade Representative (USTR). In this position, he led USTR’s economic research unit from 2015-2021, and chaired the 21-agency Trade Policy Staff Committee.

Ed began his career on Capitol Hill before serving USTR as Policy Advisor to USTR Charlene Barshefsky from 1998 to 2001. He then led PPI’s Trade and Global Markets Project from 2001 to 2011. After PPI, he co-founded and directed the independent think tank ProgressiveEconomy until rejoining USTR in 2015. In 2013, the Washington International Trade Association presented him with its Lighthouse Award, awarded annually to an individual or group for significant contributions to trade policy.

Ed is the author of Freedom from Want: American Liberalism and the Global Economy (2007).  He has published in a variety of journals and newspapers, and his research has been cited by leading academics and international organizations including the WTO, World Bank, and International Monetary Fund. He is a graduate of Stanford University and holds a Master’s Degree in International Affairs from Columbia Universities and a certificate from the Averell Harriman Institute for Advanced Study of the Soviet Union.


Read the full email and sign up for the Trade Fact of the Week

School Choice Week Must be a Catalyst for Salvaging our Education System

By Tressa Pankovits, Co-Director of PPI’s Reinventing America’s Schools Project

This is the 12th year in which the final week of January has been designated National School Choice Week (SCW). The nonprofit that sponsors the celebration — 26,000 events this year — chose this particular week because, more than any other week of the year, this is when parents begin the process of searching for schools. The event is a campaign to draw attention to the fact that children have unique learning needs; therefore, children need unique educational opportunities.

National School Choice Week is celebrated locally with school fairs, parent information sessions, open houses and rallies. There are webinars and meetups. Governors sign proclamations. Students sport bright yellow and red scarves and teach each other a new school choice dance each year. There is an upbeat “kickoff video,” and 31 public buildings and monuments — including the Aloha Tower in Hawaii and Niagara Falls on the New York-Canadian border — will dazzle in yellow and red lights after dark.

This year, however, underneath the fun and fanfare, there is a serious message for Democrats. For years, public school systems have either disregarded parents or failed to encourage their engagement. Once the progressive champions of school reform, charter schools and other education innovations, many Democrats are now failing to listen to parents as well, at their own peril.

For almost two years, parents have had an unprecedented front-row-seat into their kids’ classrooms. Many haven’t liked what they saw. Many decided one-size-doesn’t fit all, after all. Many voted with their feet. Public charter school enrollment grew from school year 2019-2020 to the end 2020-2021 by nearly a quarter of a million students, while traditional public school enrollment declined by 1.7 million students. Home schooling, virtual schools, micro-pods, and other non-traditional models also contributed to traditional schools’ decline.

Currently, it seems there are almost as many studies documenting parents’ demand for more choices as there are studies documenting student learning loss.

Democrats for Education Reform found 81% of likely 2020 voters and 89% of Black voters supported school choice. A June poll from RealClear Opinion Research found a majority support school choice (74%). The National School Choice Week organization’s own early January study found that more than half of parents either already had or were considering switching schools. Additionally, in 2021, 22 states enacted or expanded — dramatically in some cases — school choice legislation.

But not all school choice is created equal. In each of the 22 states, 2021’s school choice legislation included some kind of voucher (sometimes called education tax credit or education savings account). This has long been a top priority for Republicans, so it’s not surprising that in 18 of the 22 states, the governor signing the bill into law was a Republican.

Vouchers sound great on the surface. “Fund students, not systems!” “Let the money follow the student!” These are common rallying cries. But there are problems with vouchers, not the least that widespread distribution of vouchers would effectively dismantle the free, universally available public education system that built America’s middle class into the envy of the world.

Vouchers come with two other major flaws, as Reinventing America’s Schools’ founder, David Osborne has long argued. First, vouchers offer no guarantee that kids will get a good education, because private schools are not accountable to any public body, the way public schools are (at least theoretically). Second, if vouchers are limited to those who live in poverty, they can enhance equal opportunity, but if their use is widespread, they will actually increase inequities. Parents who can afford it will add their own money to buy more expensive education for their kids and the education market will stratify by income, Osborne argues, like the housing market and every other market has. The outcome? Children will lose the chance to grow up learning next to children of different races, ethnic groups, and social classes. If that happens, imagine even how much more fragmented and polarized our country will become.

Public charter schools, or their cousin, autonomous partnership schools, are the better, more pragmatic form of choice. If charter or partnership schools do not live up to their charter or the performance metrics of their partnership contracts, the operator loses the school. That just happened in Indianapolis. Schools can be returned to the district, given to a different partner, or closed. This offers far superior accountability to vouchers — and, for that matter, traditional district schools, which are rarely voluntarily closed even after multiple years of abysmal performance — while offering parents choices and enhanced decision-making authority over their children’s education.

But Democratic leadership and political will is lacking to decentralize massive school bureaucracies into nimble, quick-to-adapt systems. In this vacuum, Republicans pushed through or inflated voucher in nearly half of the states in 2021 alone. Democrats – especially the progressive wing of the party — largely retreated into the arms of the teachers unions while letting parents’ cries for increased school choice fall on deaf ears.

As a result, parents didn’t just vote with their feet. In 2021, they voted at the polls as well. Just a year after Joe Biden beat Donald Trump in Virginia 54% to 44%, Virginians elected Republican Glenn Youngkin, largely on education issues. Those issues included Youngkin’s promise to create 20 new charter schools in Virginia. And Youngkin may just do it. He needs just two Democratic defectors in the Senate to fulfill his charter school promise. This would be good news for Virginia students but bad news for Democrats in the 2022 midterms. Republican candidates around the country are seeking to emulate Youngkin’s playbook.

Some Democrats are starting to see the light. New Mexico House Representatives Meredith Dixon (D-Bernalillo)  and Joy Garratt (D-Albuquerque) recently co-sponsored a bill that would make it easier for charter schools to obtain facilities funding. Two Florida House Education Committees set politics aside to unanimously advance a bill that would make the charter renewal process fairer for charter schools. In Washington state, Representative Debra Entenman (D-Kent), formerly hostile to charter schools, introduced a bill to extend this year’s deadline for new charter schools to be authorized to 2027. And in Virginia, Senator Chap Peterson, who represents Fairfax, where remote learning was an exceptional mess and parents were extraordinarily angry, is on record as the likely first defector to help Governor Youngkin fulfill his charter school campaign promise.

None of this is enough for thousands of students on charter school waiting lists, of course. But it’s a start and pragmatic lawmakers like these should be celebrated. More should consider following their lead — if not for the kids, for their own political careers. National Charter School Week would be a great time to start.

PPI Report Explores Effort to Keep Mortgage Costs Low While Protecting Consumers

A new report from the Progressive Policy Institute (PPI) explores pitfalls associated with some proposed reforms to credit score markets and discusses issues that should be addressed to keep competition in the market. The report, from contributing author Brodi Fontenot, is titled “Don’t Drive Up Mortgage Costs Through Unnecessary Changes.”

While the system of credit scoring used by Fannie Mae and Freddie Mac (the Enterprises) has been in effect for some time, Congress recently asked them — along with the Federal Housing Finance Agency (FHFA) —  to review their credit scoring model to determine if additional models could be used to increase competition. But as Fontenot explains, the incorporation of a flawed new model could have unforeseen impacts and potentially drive up borrower costs.

The report concludes that the Enterprises have used a current credit scoring model that has produced necessary liquidity in the market in both good and difficult times — and that as the FHFA oversees the next phase of testing alternative credit score models, it should ensure that the models are subjected to scrutiny concerning the cost and market affects any change would have.

Read the full paper, expanded conclusion, and questions for consideration here.

Brodi Fontenot is President of Fontenot Strategic Consulting LLC. Mr. Fontenot was previously appointed by President Obama to be the Department of the Treasury’s Assistant Secretary for Management and was nominated to serve as Treasury’s Chief Financial Officer. Fontenot also served in a variety of senior roles at the Department of Transportation, including Assistant Secretary for Administration, Chief Human Capital Officer (CHCO), and Senior Sustainability Officer (SSO).

The Progressive Policy Institute (PPI) is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock. Learn more about PPI by visiting progressivepolicy.org.

###

Don’t Drive Up Mortgage Costs Through Unnecessary Changes

INTRODUCTION:

The Federal Reserve made clear in its December 2021 meeting that it intends to raise interest rates in 2022.  Interest rate changes flow through the economy and affect the rates borrowers pay on all types of loans.  In particular, the increases in interest rates may place greater pressure on home mortgage rates and the credit scores that are used by financial institutions to determine who qualifies for loans.

In the area of housing finance, how credit scores are used by key market players has received attention for some time. The better the credit score, the more likely a borrower will qualify for a mortgage at the best possible rate, saving the borrower money over the life of the loan.  There has been debate, however, over the models used to create those scores — should there be more competition and, more important, can new models lower costs for home buyers and ensure equity of access to loans.

Two of the most important entities in housing finance are the nation’s housing government sponsored enterprises — Fannie Mae and Freddie Mac (Enterprises) — which are now under government conservatorship overseen by Federal Housing Finance Agency (FHFA). As a result, many policymakers and elected officials have encouraged the FHFA to take steps to promote more competition in the credit scoring models used by the Enterprises to help lower costs to consumers and give greater access to credit for previously underserved individuals.

These are important goals and should be pursued. However, some reforms presented would have had a less than optimal effect — decreasing competition and potentially driving up mortgage costs rather than lowering them. The Enterprises have used a valid credit score model for over 20 years.  Introducing competitive reforms has merit, but it must be done in a way that does not create unfair advantages.  FHFA has a clear mandate to keep the Enterprises solvent and help homeowners, as witnessed by their recent COVID assistance.  But FHFA must ensure that any reforms maintain competition and keep prices low for consumers.

This paper reviews how credit scores are presently used by the Enterprises and discusses some of the issues that can be addressed to keep competition in the credit score market. This paper also discusses some of the pitfalls associated with some proposed reforms to credit score markets.

ENTERPRISES HAVE USED PROVEN CREDIT SCORE MODELS FOR OVER TWO DECADES

Fannie Mae and Freddie Mac (Enterprises) are commonly known as housing government sponsored enterprises.  Somewhat unique in their structure, they were originally chartered by Congress, but owned by shareholders, to provide liquidity in the mortgage market and promote homeownership.[1] The Enterprises maintained this unique ownership structure until their financial condition worsened during the financial crisis of 2008, when they were placed in government conservatorship under the leadership of the Federal Housing Finance Agency (FHFA).

The Enterprises do not create loans.  They purchase loans made by others (such as banks), and then package those loans into securities which are then sold on the secondary market to investors.  The loans purchased by the Enterprises can only be of a certain size and home borrowers must have a minimum credit score to qualify.  The Enterprises use these and other criteria to minimize the risk that the loans they purchase will not be paid back (default) — an important step because it is this step of buying loans from banks and other lenders, thereby providing them with replenished funding that allows further home lending.

The loans purchased by the Enterprises then are packaged into securities that have specific characteristics which are told to investors — including the credit scores on the loans in the security.  According to FHFA, the Enterprises use credit scores to help predict a potential borrowers likeliness to repay and has been using a score developed from a model, FICO Classic,[2] for over 20 years.[3]  In discussing FICO Classic, FHFA points out that it “and the Enterprises believe that this score remains a reasonable predictor of default risk.”[4]

While the current system has been in effect for some time, Congress recently asked FHFA and the Enterprises to review their credit scoring model to determine if additional credit scoring models could be used by the Enterprises to increase competition.  Specifically, FHFA was to “establish standards and criteria for the validation and approval of third-party credit score models used by Fannie Mae and Freddie Mac.”[5]  Advocates of using alternatives to FICO Classic said, at the time, that using other validated credit scoring models would lead to more access.[6]  While a worthy goal, incorporating a flawed new model, could have impacts and potentially drive-up costs.

CONFLICT OF INTEREST COULD LEAD TO DECREASED COMPETITION

Beginning in 2017, FHFA proposed a rule which would set the stage for reviewing the Enterprises’ credit score models.  The rule FHFA finalized in 2019 directed the Enterprises to review and validate alternative credit models in the coming years.

Section 310 of the Economic Growth, Regulatory Relief, and Consumer Protection Act of 2018 (Pub. L. 115–174, section 310) amended the Fannie Mae and Freddie Mac charter acts and the Federal Housing Enterprises Financial Safety and Soundness Act of 1992 (Safety and Soundness Act) to establish requirements for the validation and approval of third-party credit score models by Fannie Mae and Freddie Mac.[7]

At the time of the proposed rule, some thought that alternative credit scores could open access to a larger group of homeowners.[8] [9] While an admirable goal, and in keeping with FHFA’s mission for the Enterprises even now, a major issue was left unresolved.  The proposed rule “would have required credit score model developers to demonstrate, upon applying for consideration, that there was no common ownership with a consumer data provider that has control over the data used to construct and test the credit score model.”[10]

The proposed rule would have created a separation between those who create and control the data, from those in charge of the model creating the scores — an important goal. Not surprisingly, the proposed rule received significant comments. Sadly, the final rule did not adopt this important provision which required those submitting models to not have a conflict of interest or “common ownership with a consumer data provider that has control over the data used to construct and test the credit score model.”[11]  This lack of clear independence could set the stage for a lack of competition in the future.

While the rule was being proposed, former FHFA director Mel Watt in 2017 said, “how would we ensure that competing credit scores lead to improvements in accuracy and not to a race to the bottom with competitors competing for more and more customers?  Also, could the organizational and ownership structure of companies in the credit score market impact competition?  We also realized that much more work needed to be done on the cost and operational impacts to the industry.  Given the multiple issues we have had to consider, this has certainly been among the most difficult evaluations undertaken during my tenure as Director of FHFA.”[12]

Several at the time of the proposed rule pointed out that having one dominant player possibly replaced by another, would not further competition but could further consolidate it.  One commentator stated, “to push for alternative scoring models may simply trade one dominant player (FICO) for another (Vantage),”[13] in referring to legislation which would ultimately be incorporated into the bill where the proposed rule was developed.  The Progressive Policy Institute (PPI) held an expert panel discussion at the time which also discussed the problems with adopting VantageScore due to conflict of interest.[14]  “The reason? Because the owners of Vantage control the supply of information currently used by FICO to make its determination. And given the history of monopolies, it would not be surprising to see Equifax, Experian, and TransUnion use that leverage to the advantage of Vantage, and eventually force FICO out of business.”[15]

The proposed rule points out that “VantageScore Solutions, LLC is jointly owned by the three nationwide CRAs.  The CRAs also own, price, and distribute consumer credit data and credit score.  This type of common ownership could in theory negatively impact competition in the marketplace.”[16]  Another writer at the time, also acknowledged the potential conflict of interest provision of the proposed rule.[17]  While these issues were not resolved in the final rule, they still matter and can affect not only competition but also costs in the residential mortgage marketplace.

Competition is key to innovation and inclusiveness is important to further homeownership.  Using alterative data, rent payments, utility payments, bank balances, all could potentially be used help complete the credit picture and increase access to credit.[18]  Other research organizations have acknowledged that FICO has improved models and incorporated alternative sources of data that are available,[19] which would not have the conflict of interest that VantageScore would have.  FHFA must ensure that competition is maintained, without creating unfair advantages.

LACK OF REAL COMPETITION COULD INCREASE COSTS

Before any changes can happen, however, FHFA must articulate all costs to consumers, lenders, the Enterprises, and investors of any change.  COVID-19 proved a real-world laboratory for the Enterprises under stress.  FHFA’s recent Performance Report lays out the series of actions the Enterprises took to help borrowers affected by COVID-19, including payment deferrals, forbearance, and evictions suspensions.[20]  These actions likely kept many homeowners in their homes during a difficult period, and kept the Enterprises functioning.  The relief provided was important and was balanced against the risk to the Enterprises — but it did come at a cost.

FHFA made their first announcement on COVID assistance to homeowners in March 2020.[21]  A few months later in August 2020, FHFA announced that the Enterprises would charge a fee of 50-baisis points per refinancing to help make up for any potential losses the Enterprises might experience.[22]  An initial estimate put the projected losses at $6 billion.  Thankfully the Enterprises saw declining rates of loans in forbearance and the fee was ultimately ended in July 2021.[23]

Changes at the Enterprises have affects across the industry.  Just as the potential increases in interest rates by the Federal Reserve this year could raise interest costs to home buyers, at time of the proposed rule, former FHFA Director Watt knew that changes to the credit scoring model could raise costs and even stated “much more work needed to be done on the cost and operational impacts to the industry,”[24] before changes were made.  Clearly, the FHFA realizes that any changes to its credit scoring models will also likely have increased costs to the housing finance sector.  As an aside, the related issue of changes to issues such as mortgage servicing have led to increased costs in the home purchase ecosystem.[25]

Changes to the credit scoring models could also affect prices in the secondary market for mortgage-backed securities (MBS) and credit risk transfers (CRT).  As the FHFA pointed out, investors “in Enterprise MBS and participants in Enterprise CRT transactions would need to evaluate the default and prepayment risks of each of the multiple credit score options.”[26]  While the FHFA in the final rule did not address the costs of these evaluations, incorporating multiple credit score options could raise the cost investors demand and ultimately increase the costs to home buyers via the fees the Enterprises would need to pass on.

Others have pointed out that changes to credit scoring models could have cost impacts for banks, investors, pension funds, and others.[27]  These issues of cost and operational impacts need to be given serious consideration, because as the recent Enterprise actions related to COVID-19 made clear — they matter.  The lending industry was upset when the Enterprises raised a temporary fee to help ensure Enterprises’ soundness through the difficult period.[28]  What would the costs be with a wholesale change to the credit score model system?  And who would ultimately pay those costs?  These are questions the FHFA must address as they review any changes to the credit scoring model.

One of the FHFA’s current core goals is to “Promote Equitable Access to Housing.”[29] To ensure that the Enterprises can undertake their important role in addressing long standing issues of equity, they need to be in the best place possible financially to do that.  A question that FHFA needs to address as they review credit scoring models is, would using a model with a conflict of interest hurt their goal of equity?  Would changes raise prices or worse, limit access for those FHFA is looking to provide access into the market?

CONCLUSION AND QUESTIONS FOR CONSIDERATION

The crisis of COVID-19 and its effects on the housing market were serious, but thankfully not detrimental due to prudent planning and oversight of the Enterprises and FHFA.  The Enterprises have used a current credit scoring model that has produced necessary liquidity in the market in both good and difficult times.  As FHFA oversees the next phase of testing alternative credit score models, it should ensure that the models are subjected to the criteria laid out in their final rule — with emphasis placed on the cost and market affects any change would have.  The Enterprises were called upon to help homeowners during the recent crisis and could do so with minimal disruption to the consumers and housing finance stakeholders.  The Enterprises and FHFA should take seriously how any further changes would impact competition, soundness of the Enterprises, and how those changes could increase the costs for everyone in housing finance.

REFERENCES

[1]“Fannie Mae and Freddie Mac in Conservatorship: Frequently Asked Questions,” Congressional Research Service, July 22, 2020, https://crsreports.congress.gov/product/pdf/R/R44525.

[2] “Selling Guide: B3-5.1-01, General Requirements for Credit Scores,” Fannie Mae, September 2021, https://selling-guide.fanniemae.com/Selling-Guide/Origination-thru-Closing/Subpart-B3-Underwriting-Borrowers/Chapter-B3-5-Credit-Assessment/Section-B3-5-1-Credit-Scores/1032996841/B3-5-1-01-General-Requirements-for-Credit-Scores-08-05-2020.htm.

[3] “There’s More to Mortgages than Credit Scores,” Fannie Mae, February 2020, https://singlefamily.fanniemae.com/media/8511/display.

[4] “Credit Score Request for Input,” FHFA Division of Housing Mission and Goals, December 20, 2017, https://www.fhfa.gov/Media/PublicAffairs/PublicAffairsDocuments/CreditScore_RFI-2017.pdf.

[5] “FHFA Issues Proposed Rule on Validation and Approval of Credit Score Models,” Federal Housing Finance Agency, December 13, 2018, https://www.fhfa.gov/Media/PublicAffairs/Pages/FHFA-Issues-Proposed-Rule-on-Validation-and-Approval-of-Credit-Score-Models.aspx.

[6] “Validation and Approval of Credit Score Models,” Federal Housing Finance Agency, August 13, 2019, https://www.fhfa.gov/SupervisionRegulation/Rules/RuleDocuments/8-7-19%20Validation%20Approval%20Credit%20Score%20Models%20Final%20Rule_to%20Fed%20Reg%20for%20Web.pdf.

[7] “Federal Register/Vol. 84, No. 159/Friday, August 16, 2019/Rules and Regulations,” August 2019, https://www.govinfo.gov/content/pkg/FR-2019-08-16/pdf/2019-17633.pdf

[8] Karan Kaul, “Six Things That Might Surprise You About Alternative Credit Scores,” Urban Institute, April 13, 2015, https://www.urban.org/.

[9] Michael A. Turner et al., “Give Credit Where Credit Is Due,” Brookings Institution, June 2016, https://www.brookings.edu/wp-content/uploads/2016/06/20061218_givecredit.pdf.

[10] “Federal Register.”

[11] “Federal Register.”

[12] Melvin L. Watt, “Prepared Remarks of Melvin L. Watt, Director of FHFA at the National Association of Real Estate Brokers’ 70th Annual Convention,” Federal Housing Finance Agency, August 1, 2017, https://www.fhfa.gov/Media/PublicAffairs/Pages/Prepared-Remarks-of-Melvin-L-Watt-Director-of-FHFA-at-the-NAREB-70th-Annual-Convention.aspx.

[13] Paul Weinstein Jr., “No Company Should Have a Monopoly on Credit Scoring,” The Hill, December 7, 2017, https://thehill.com/opinion/finance/363755-no-company-should-have-a-monopoly-on-credit-scoring.

[14] “Updated Credit Scoring and the Mortgage Market,” Progressive Policy Institute, December 4, 2017, https://www.progressivepolicy.org/event/updated-credit-scoring-mortgage-market/.

[15] “No Company Should Have a Monopoly.”

[16] “Validation and Approval of Credit Score Models: Final Rule,” Federal Register, August 16, 2019, https://www.federalregister.gov/documents/2019/08/16/2019-17633/validation-and-approval-of-credit-score-models.

[17] Karan Kaul and Laurie Goodman, “The FHFA’s Evaluation of Credit Scores Misses the Mark,” Urban Institute, March 2018, https://www.urban.org/sites/default/files/publication/97086/the_fhfas_evaluation_of_credit_scores_misses_the_mark.pdf.

[18] Kelly Thompson Cochran, Michael Stegman, and Colin Foos, “Utility, Telecommunications, and Rental Data in Underwriting Credit,” Urban Institute, December 2021, https://www.urban.org/research/publication/utility-telecommunications-and-rental-data-underwriting-credit/view/full_report.

[19] Laurie Goodman, “In Need of an Update: Credit Scoring in the Mortgage Market,” Urban Institute, July 2017, https://www.urban.org/sites/default/files/publication/92301/in-need-of-an-update-credit-scoring-in-the-mortgage-market_2.pdf.

[20] “Performance & Accountability Report FY2021,” Federal Housing Finance Agency, 2021, https://www.fhfa.gov/AboutUs/Reports/ReportDocuments/FHFA-2021-PAR.pdf.

[21] “Statement from FHFA Director Mark Calabria on Coronavirus,” Federal Housing Finance Agency, March 10, 2020, https://www.fhfa.gov/Media/PublicAffairs/Pages/Statement-from-FHFA-Director-Mark-Calabria-on-Coronavirus.aspx.

[22] “Adverse Market Refinance Fee Implementation Now December 1,” Federal Housing Finance Agency, August 25, 2020, https://www.fhfa.gov/Media/PublicAffairs/Pages/Adverse-Market-Refinance-Fee-Implementation-Now-December-1.aspx.

[23] “FHFA Eliminates Adverse Market Refinance Fee,” Federal Housing Finance Agency, July 16, 2021, https://www.fhfa.gov/Media/PublicAffairs/Pages/FHFA-Eliminates-Adverse-Market-Refinance-Fee.aspx.

[24] Melvin L. Watt, “Prepared Remarks.”

[25] Laurie Goodman et al., “The Mortgage Servicing Collaborative,” Urban Institute, January 2018, https://www.urban.org/sites/default/files/publication/95666/the-mortgage-servicing-collaborative_1.pdf.

[26] “Credit Score Request for Input.”

[27] Pete Sepp and Thomas Aiello, “Risky Road: Assessing the Costs of Alternative Credit Scoring,” National Taxpayers Union, March 22, 2019, https://www.ntu.org/publications/detail/risky-road-assessing-the-costs-of-alternative-credit-scoring.

[28] “FHFA Eliminates Controversial ‘Adverse Market Refinance Fee’.”

[29] “Performance & Accountability Report.”

DOWNLOAD THE PAPER


Representative Lori Trahan and Esteemed Public Health Experts Join PPI for Event on the How to Live with COVID in 2022 and Beyond

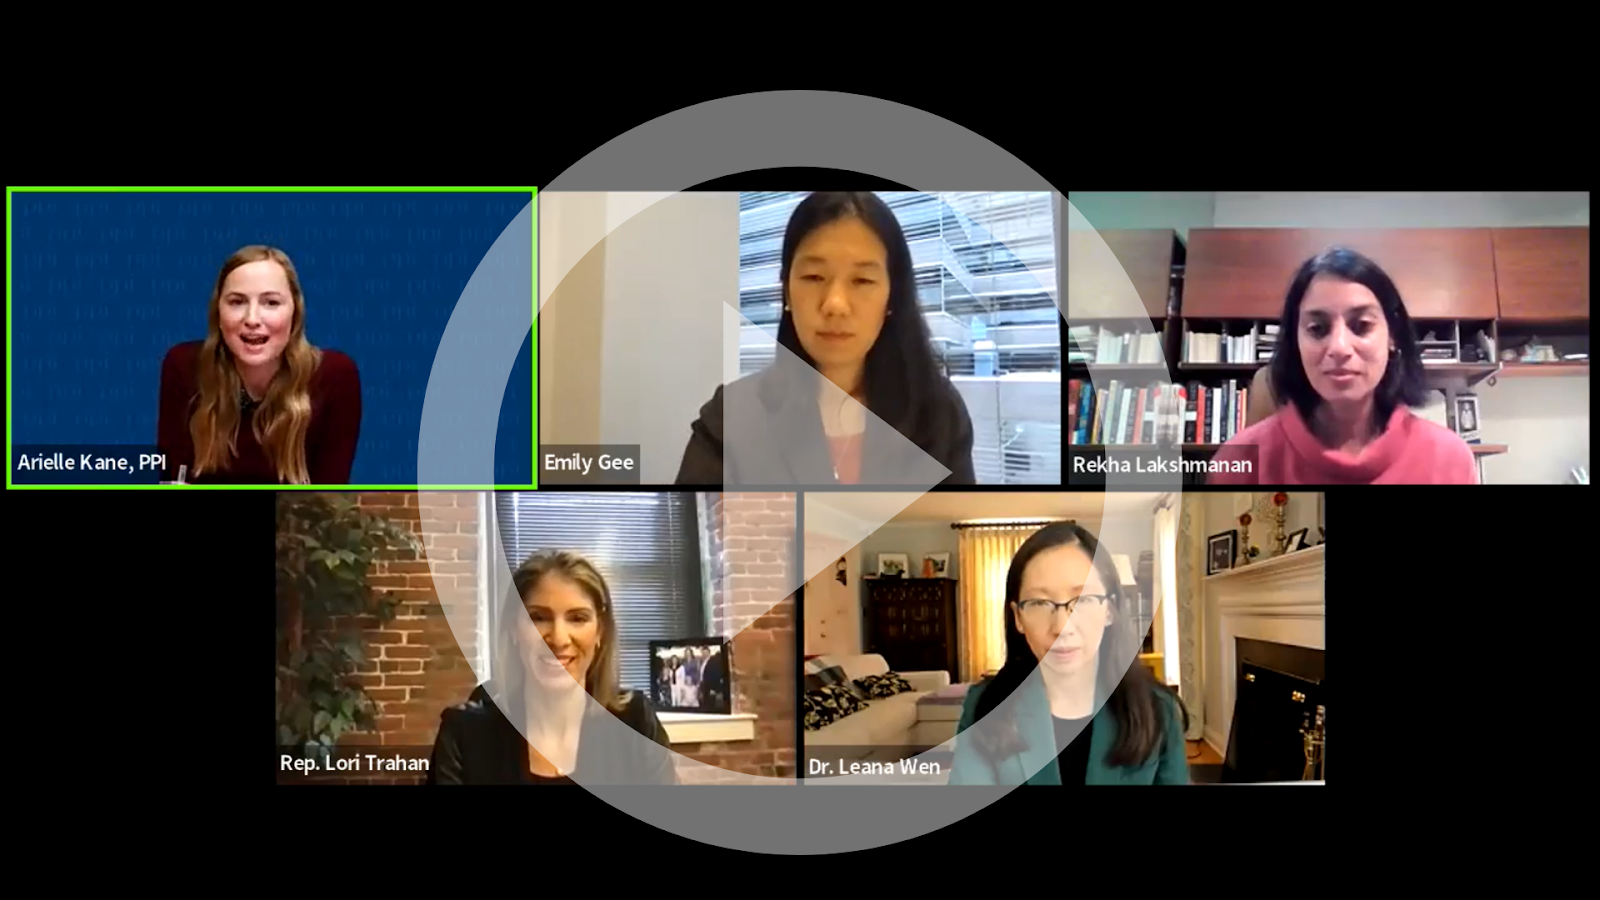
Rep. Lori Trahan, Dr. Leana Wen, Rekha Lakshmanan, and Emily Gee discuss how to respond to a deluge of changing public health guidance, a minefield of conflicting information, and pandemic preparedness for the future.

Today, the Progressive Policy Institute hosted an event with Rep. Lori Trahan (MA-03) and an esteemed panel of medical and health policy experts on the sustainable policies lawmakers should consider to combat the omicron variant. The panel also discussed how to best balance the tradeoffs between combating the spread of COVID-19 and letting normal life resume — and how businesses, employers, families and individuals can best respond to the deluge of changing public health guidance on the virus.

“We need to get the virus to a manageable level — where hospitals aren’t overrun — but we will be living with it for years to come. Policies need to reflect that reality,” said Arielle Kane, Director of Health Policy at PPI and moderator of the event. “Thank you to Congresswoman Trahan, Dr. Leana Wen, Rekha Lakshmanan, and Emily Gee for lending their expertise to this important discussion on solutions to this continuing public health challenge, and for their leadership throughout this pandemic.”

Watch the event livestream here:

Representative Lori Trahan serves on the House Energy and Commerce Committee, and sits on the subcommittees on Health, Consumer Protection and Commerce, and Oversight and Investigations. The Congresswoman is also a Co-Chair of the Pandemic Preparedness Caucus.

“With the creation and distribution of the vaccine, we’ve begun down the road to establishing a new normal with COVID-19 — but one where we can be protected from it, if we all do our part,” said Rep. Trahan during the event. “…Conversations about what the new normal is, what restrictions are too burdensome and which ones are practical safety measures — that keep people safe — are really important.”

In addition to Rep. Trahan, this event’s esteemed panelists included Leana S. Wen, MD, MSc, Research Professor of Health Policy and Management at George Washington UniversityRekha Lakshmanan, Director of Advocacy and Policy, The Immunization Partnership and Contributing Expert, Rice University’s Baker Institute for Public Policy; and Emily Gee, Vice President and Coordinator for Health Policy at the Center for American Progress.

“At this point in this pandemic, we have to accept that we’re going to be living with COVID. What does that look like? It’s actually not a scientific answer as much as it is a policy and political answer,” said Dr. Leana Wen during the event. “…We in science can’t tell people what you value. Is the value going to be ‘we prioritize infection control above all else?’ Or is the value that we want society to move on, above all else? That’s the decision ahead of us.”

The Progressive Policy Institute (PPI) is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock. Learn more about PPI by visiting progressivepolicy.org.

Follow the Progressive Policy Institute.

###

Media Contact: Aaron White – awhite@ppionline.org

PPI Statement on Senate Judiciary Committee’s Advancement of Klobuchar-Grassley Anti-Tech Antitrust Bill

Aaron White, Director of Communication for the Progressive Policy Institute (PPI), released the following response in reaction to the Senate Judiciary Committee’s advancement of the American Innovation and Choice Online Act:

“For those of us that believe in good governance and the importance of legislative deliberation and debate, today’s markup of the American Innovation and Choice Online Act was embarrassing for the Senate.

“The Judiciary Committee’s markup made it crystal clear that there are still significant, unresolved concerns on both sides of the aisle. As written, the bill sparks major national security and privacy risks, includes overly broad and burdensome language, and will harm American consumers, workers, and the digital economy.

“Senator after Senator raised concerns that this was a rushed legislative process, and this bill is not ready for primetime, yet Senator Klobuchar chose to force this vote. The Senate should do its job and return to the legislative process that all Senators can be proud of. This bill should not see the Senate floor until the legitimate concerns of Senators are addressed.

“The digital economy is a hallmark American achievement that has created millions of middle-class jobs. Scrutiny is important and healthy; but the Senate must address their concerns in a deliberative fashion — not in a haphazard, potentially reckless manner.”

###

Last Minute Changes to Klobuchar’s Anti-Tech Bill Do Nothing to Ease Harms to Consumers

Ahead of tomorrow’s Senate Judiciary Committee markup, an amended version of Senator Klobuchar’s American Innovation and Choice Online Act has been released. While the amendment makes clear the bill’s sponsors are cognizant of the shortcomings associated with the legislation, it is functionally devoid of the changes necessary to prevent the harm the bill currently poses to American consumers. The result is a bill which puts aside the objective of consumer welfare and threatens the way in which both users and businesses utilize integrated online services.

In no section is this more glaringly obvious than in the amended language around subscription-based services. The amendment seeks to fortify Senator Klobuchar’s claim that the bill does not interfere with Amazon’s ability to offer Prime delivery services by clarifying that companies cannot be held liable for “offering a fee for service subscription that provides benefits to covered platform users”. What the amendment ignores, however, is the mechanisms through which the bill harms Prime in the first place. By opening the company up to legal liability on the grounds that Prime’s benefits to consumers give an unfair advantage to Amazon itself, the amended bill still could render Amazon Prime infeasible under the threat of significant fines should they continue to offer the service. For the estimated 153 million Americans subscribed to Amazon Prime, this could mean the loss of popular services such as two-day shipping, while third-party retailers who take advantage of Amazon’s Fulfillment By Amazon (FBA)  service to offer Prime delivery on third-party products lose valuable access to Amazon’s established customer base. Moreover, Amazon’s FBA service might itself become a victim of self-preferencing charges, since lawsuits would certainly be filed arguing that Amazon was charging third-party sellers too much for logistic services compared to a hypothetical price that it was charging itself.

The implementation of such a carve-out for subscription services introduces additional complications for online platforms which also come at the expense of the consumer. By shielding from liability in cases where a fee is charged to users, companies are incentivized to begin charging for services which are currently available free of cost to ensure that they remain accessible to consumers in their current form. For example, under the original language of the bill, Google is not able to display Google services such as maps or company profiles at the top of search results, as such a practice is considered as self-preferencing. The amendment makes it so that to preserve this feature, Google must offer a paid subscription to services such as Google Maps, essentially making it so that companies seeking to avoid penalties under this bill must implement fees to consumers for already popular services to avoid legal liability.

The disregard for the bill’s implications regarding consumer welfare raises an important question: Who is antitrust legislation meant to benefit? In theory, promotion of competition on online platforms may lower prices and increase choice, but the line of thinking promoted by this bill turns a blind eye to the reality of how users and businesses engage with internet services. For consumers, integrated online services are a valued feature of the products provided by platforms. By taking this integration away or requiring that it be offered at cost, Americans who depend on these services will be left worse off with the passage of this bill. The committee is clearly trying to defend itself against valid criticism of the bill with such last-minute tweaks, but the deeper question is, how do these proposed changes in any material way promote innovation, competition or consumer welfare?

Trade Fact of the Week: The U.S. Generalized System of Preferences program has been expired for more than a year

FACT:

The U.S. Generalized System of Preferences program has been expired for more than a year.


THE NUMBERS: 

GSP imports, 2020 –

tons of Ukrainian pickles
3,700 traditional Mongolian ger (nomadic living tents)
11,900 liters of Georgian wine
1.5 tons of Pakistani spice mix
$5 million in Namibian stonework
412 tons of taro root from Tonga and Samoa
90,000 Rwandan travel bags
492 tons of Fijian ginger (candied and sushi-grade)
1 million dog collars and leashes from Cambodia
14,000 Senegalese wicker baskets
15 tons of vegetable oil from Timor-Leste
$9.5 million in Armenian-made golden jewelry
217 tons of South African essential oils (eucalyptus, orange, lemon, grapefruit)
27.3 million Thai orchids
870,000 Haitian-woven flags
32,700 Bolivian-made wooden doors


WHAT THEY MEAN:

The U.S.’ oldest and largest effort to help the poor abroad is the “Generalized System of Preferences”, or “GSP” for short.  Dating to 1974, it waives tariffs on about 3,500 types of products (more precisely, on 3,500 “tariff lines”) from 119 low- and middle-income countries meeting 15 eligibility criteria covering cooperation against terrorism, labor standards, intellectual property, expropriation, trade policy, and other issues.  The law authorizing GSP benefits lapsed at the end of 2020, so for a year the program has been stopped.  As Congress works on renewal, PPI Vice President Ed Gresser – who among other things directly oversaw GSP system administration from 2015-2020 – has observations and ideas in PPI’s newest policy paper:


By way of background, GSP is fairly simple. By waiving U.S. tariffs – 7.0% on flags, 9.6% on pickles, 2.3% on fresh taro root, etc. – imposed on things made or grown in places like Haiti, Ukraine, and the Pacific Islands, it encourages buyers otherwise drawn to the EU, China, or other larger suppliers to these smaller and poorer countries, helping them diversify their economies and create better job opportunities. Australia, EU, Canada, Japan, and other high-income countries have their own GSP programs launched around the same time as the U.S. GSP; other countries such as China, Taiwan, Chile, and Korea have created their own similar systems more recently.

The program’s scale is modest.  Imports of variously picturesque and mundane GSP products totaled $16.9 billion in 2020 – 0.8% of the U.S.’ $2.351 trillion in total goods imports, and (more relevant) 11.1% of the $152 billion in imports from the 119 participating countries – but the impact is useful.  Reviewing the results in 2016 (along with those of regional preference programs AGOA and CBI) the Obama administration concluded that “U.S. trade preference programs have encouraged exports from developing countries, with particular effect in value-added and labor-intensive goods … This is corroborated by a large body of economic literature [which has] also found that U.S. trade preference programs have made a contribution to the reduction of poverty.”

Gresser’s paper applauds Congressional interest in renewing the system – the Senate has passed a reauthorization bill and House Democrats have introduced one which differs in some areas from the Senate bill but shares much with it – noting that reauthorization will be good for the countries participating in the system and, in a small but tangible way, for the Biden administration’s effort to show that America “is back”.  It also endorses Congress’ interest in rethinking aspects of the program.  GSP’s list of “eligibility criteria” (that is, a set of policy goals a country needs to meet to qualify for tariff waivers) mainly dates to the 1970s and 1980s.  So does its list of “import-sensitive” products excluded as overly competitive with U.S. goods and its “Competitive Need Limits” on the levels of particular products a country is allowed to send duty-free.  All these could probably use a fresh look.

On the other hand, the paper expresses concern about a large proliferation of new eligibility rules in both the Senate and House Democratic bills.  It argues for dialing this back a bit and balancing new rules with new product coverage (as a complementary proposal by Representatives Stephanie Murphy (D-Fla) and Jack Walorski (R-Ind) suggests).  Three thoughts as Congress moves ahead:

1.    Set priorities when adding new eligibility rules.

The current list of 15 eligibility criteria includes some moribund issues (“domination by the international Communist movement”), misses some contemporary concerns, and overall is a bit of a hodge-podge.  But it also has some virtues, including brevity: the list is short enough to set clear priorities, so governments of GSP countries know what they need to do to retain benefits.  Both reauthorization bills risk losing this virtue by adding many new criteria: human rights, poverty reduction, environment, gender policy, anti-corruption, economic reform, microcredit availability, political participation, rule of law, digital trade, and others.  Though all appear well-intended, expansion on this scale can overload a small system, and risk forcing wholesale unintended expulsions of countries which fall short on one or two of many criteria, or pushing administrations into unsystematic and essentially arbitrary enforcement to avoid such an outcome.

2.    Recognize good-faith effort.

A second virtue is that the current eligibility criteria are flexibly written, enabling officials administering the system to recognize good-faith if imperfect efforts to comply.  Overly strict rules for low-income countries can be unrealistic: “low-income countries often have well-trained and well-intentioned leaders and senior bureaucrats who design good policies … [but] few such countries have the deep and professional civil services needed to effectively [implement] these policies uniformly and nationwide.”  Whether adding new criteria or updating old ones, good-faith effort by well-intentioned governments should continue to get credit.

3.    Balance new eligibility rules with broader benefits. 

Finally, new looks at old eligibility rules should go together with new looks at old limits on benefits.  GSP rules set in the 1970s excludes some significant categories of goods (clothes, shoes, glassware, watches) and also, under an unusual feature known as “Competitive Need Limitations”, remove products from a country’s GSP portfolio when it becomes too good at making them.  The paper suggests reconsidering some of the product exclusions, for example that of shoes not made in the United States, and applauds the Murphy/Walorski proposal’s reforms to the ”Competitive Need Limitation” feature of GSP.

FURTHER READING

>> PPI’s Gresser on GSP Renewal – “Trade, the Poor, and America is Back” – Read the Report 

Background:

The U.S. Trade Representative’s GSP Guidebook explains GSP program goals, product coverage, eligibility rules, and country participation.

The Obama administration (2016) evaluates U.S. trade preference programs (including GSP and also the African Growth and Opportunity Act and the Caribbean Basin Economic Recovery Act) and their records on poverty alleviation.

Some beneficiaries:

The Embassy of Ukraine explains GSP benefits to potential U.S. customers.

The Fiji Sun reports on a U.S. official’s 2018 visit to a GSP-beneficiary ginger factory.

USTR presentation on benefits for Mongolia (tungsten concentrate, leather bags, pine nuts, traditional “ger” tents).

Ecuadoran Ambassador Ivonne Baki updates Quito press on GSP reauthorization.

… and a Delaware vendor of Mongolian “ger” (traditional tents).

Renewal proposals from:

Senate Finance Committee (included in larger bill and passed in 2021).

House Ways and Means Democrats.

Reps. Murphy & Walorski.

… and for comparison, the current GSP statute.

And some international comparisons: 

Japan’s Ministry of Foreign Affairs explains the Japanese GSP.

The European Union.

Australia.

China’s “least-developed country” tariff waiver.


ABOUT ED

Ed Gresser is Vice President and Director for Trade and Global Markets at PPI.

Ed returns to PPI after working for the think tank from 2001-2011. He most recently served as the Assistant U.S. Trade Representative for Trade Policy and Economics at the Office of the United States Trade Representative (USTR). In this position, he led USTR’s economic research unit from 2015-2021, and chaired the 21-agency Trade Policy Staff Committee.

Ed began his career on Capitol Hill before serving USTR as Policy Advisor to USTR Charlene Barshefsky from 1998 to 2001. He then led PPI’s Trade and Global Markets Project from 2001 to 2011. After PPI, he co-founded and directed the independent think tank ProgressiveEconomy until rejoining USTR in 2015. In 2013, the Washington International Trade Association presented him with its Lighthouse Award, awarded annually to an individual or group for significant contributions to trade policy.

Ed is the author of Freedom from Want: American Liberalism and the Global Economy (2007).  He has published in a variety of journals and newspapers, and his research has been cited by leading academics and international organizations including the WTO, World Bank, and International Monetary Fund. He is a graduate of Stanford University and holds a Master’s Degree in International Affairs from Columbia Universities and a certificate from the Averell Harriman Institute for Advanced Study of the Soviet Union.

Read the full email and sign up for the Trade Fact of the Week