Shift to “Demand Driven” Immigration

The COVID-19 crisis initially affected the U.S. immigration system by prompting the shutdown of immigration courts and suspension of routine visa processing services. These actions were more or less in line with broader economic shutdowns and closures. The Trump administration, however, has seized on the COVID-19 crisis as a fresh pretext for enacting a cruel and radically restrictive immigration agenda that slows economic recovery, hurts the United States in the long-term, and is out of step with what Americans support.

In June, for example, President Trump announced an extension, through the end of the year, of his “temporary” ban on new work visas. This includes high-skilled workers, executives, and seasonal workers who are critical to U.S. innovation and growth. While small modifications to the order have been made—and lawsuits have been brought—it still places serious limitations on America’s ability to act as a magnet for talent. Immigrant workers already in the country have also faced disproportionate exposure to the pandemic at, for example, meatpacking plants, thanks to the administration’s lax approach to occupational safety.

The administration’s actions are bad policy at any time; today they make life even more difficult for immigrants and dig the pandemic-created economic hole even deeper. They also follow three years of immigration policymaking that has made our labor markets less flexible and our economy less dynamic and less innovative.

Yet it must also be said that America’s immigration system was not in the best shape even before the Trump administration’s detour into nativism and wall-building. Despite some progress made by President Obama, U.S. immigration policy had been growing misaligned with the nation’s changing economic needs. For progressives, the challenge is not merely to undo what Trump has done, but to make our economy more dynamic and resilient by bringing our immigration laws into the 21st century.

The key change is to make U.S. immigration laws more “demand-driven” and responsive to labor market needs as America ages, our workforce grows more slowly, and labor shortages hamper production from agriculture to high tech.

Two-thirds of green cards issued each year are for family reunification, with about one in six being employment-based. A large share of employment-based green cards, moreover, are issued to family members of workers. While family reunification is the broad superhighway by which most legal immigrants enter the United States, we also have an alphabet soup of visa programs which offer certain workers narrow routes of entry. There are, for example, nearly two dozen different types of visas for “temporary nonimmigrant workers.” Some of these programs function fairly well but taken as a whole they make work-based immigration unduly fragmented and complex, and subject to industry capture.

Family reunification should remain an important goal for U.S. immigration policy. Our country has a proud tradition of welcoming migrants and refugees as families as well as individuals. Many economically successful first- and second-generation immigrants that we celebrate—such as Sergey Brin, Elon Musk, and Steve Jobs—came here as children or students.

Nonetheless, the time has come to adjust the balance and widen channels for work-based immigration, making sure they more closely match employer demand and economic need. To shift our policies in this direction, PPI proposes to replace the welter of narrow visa programs with a new Willing Worker Visa that admits people regardless of the kind of skills they have as long as they have a valid job offer from a U.S. employer. In order to be valid, employers would have to show they could not meet their labor needs with native workers alone.

In addition to expanding the supply of legal workers and dramatically simplifying our immigration laws, our approach would crack down on employers who knowingly hire illegal workers. The Trump administration has focused instead on penalizing workers while letting employers off the hook—echoing the president’s own record of using illegal workers in his businesses.

Key elements of the Willing Worker Visa would include:

  • Simplification and consolidation of existing visa programs to make entry and certification processes far smoother.
  • Contingency on job offers from U.S. employers, just as many employment-based visas are now.
  • Expanded pathways for temporary and nonimmigrants workers to become citizens, in part to discourage and reduce illegal border-crossing.
  • Tying visas for willing workers to areas of demonstrated skill gaps and labor shortages.
  • Tougher penalties on employers who knowingly hire illegal workers, fail to check documentation, or ignore immigration law.

It may seem incongruous to argue for more employment-based immigration as the coronavirus pandemic continues to spread across the United States. Much of our economy is still locked down, we have double-digit unemployment, and there’s deep uncertainty about how long it will take the economy to recover.

Current projections are that unemployment rates will remain over 10 percent well into 2021. We know, however, that even at the height of the economic expansion in 2019, the U.S. economy faced severe skill shortages, with more than seven million jobs unfilled.

Moreover, Trump’s claim that he wants to restrict immigration to preserve U.S. jobs for
U.S. workers stems from a faulty, zero-sum understanding of how labor markets work. In
a dynamic market economy, the number of jobs is never fixed but grows with labor supply. We have a compelling national interest in opening America’s doors to willing workers from elsewhere who can help us close skills gaps and fill labor shortages.

The challenge is to ensure that unemployed native workers are successfully reabsorbed into the labor force while also ensuring a strong supply of willing foreign workers who help make the U.S. economy more productive and innovative.

Make Electoral Democracy More Resilient

The COVID-19 pandemic has laid bare the fragility of the United States electoral voting system. Polling places, which are often densely packed indoor spaces, represent an acute public health danger. Yet, many states do not have the infrastructure in place to adapt to this situation, and it has thrown the health of Americans and our democratic institutions into doubt.

Right from the onset of this pandemic, several individuals and organizations raised alarms that the United States’ electoral system would have to radically adapt to coronavirus. Some states took this cue and pushed back their elections to buy time to implement alternative election systems or in hopes that COVID-19 would abate. Several other states, however, did nothing. Florida, which held its Democratic primary on March 17th, experienced a 53% drop in turnout from its turnout in 2016. Illinois which held its primary on the same day, saw a 61% drop in primary turnout.

States are still lagging on providing their residents with ways to vote safely during coronavirus. According to analysis from the Brooking Institute, 32 states received a C grade or lower on their performance providing residents with the ability vote-at-home during the pandemic. Alabama, which received an F grade as of writing, requires voters to have a notary or two witnesses to complete an absentee ballot. Connecticut, which received a D grade as of writing, does not offer no-excuse absentee voting, nor does it accept COVID-19 as a permitted reason to request an absentee ballot.

There is a solution to this dilemma: universal vote-at-home. Registered voters would receive a ballot in the mail automatically, without having to file an application or request one. Unlike traditional election procedures, universal vote-at-home allows Americans to vote from the safety of their households and then to return their ballot by mail or to drop in a secure drop box. This would give Americans the opportunity to carry out their democratic responsibility without putting them in harm’s way. Yet, very few states have the infrastructure currently in place to shift their electoral system to universal vote-at-home. Neither has Congress made this a priority.

Universal vote-at-home is not a novel idea. Five states – Washington, Oregon, Utah, Hawaii and Colorado – currently have the proven capacity to conduct their elections without the need for physical polling locations. Dozens of other states have the proven capacity to allow a significant percentage of their citizens to vote-at-home, and few others have precedence for voting-at-home but only allow it in the most extreme of circumstances.

Congress should incentivize the remaining states to move to a universal vote-at-home model, not only for the upcoming election but for future elections as well. Based on estimates from the Brennan Center for Justice, the cost of expanding vote-at-home to all Americans runs from $982 million to $1.4 billion. While the short-run cost is not insignificant, research has shown that universal vote-at-home reduces the administrative costs related to running elections by 40%. This represents a long-term cost saving for states and all Americans.

Some officials and organizations have alleged that universal vote-at-home is more vulnerable to fraud than in-person voting, but the evidence does not support such claims. The decentralized nature of vote-at-home means that widespread fraud would require infiltrating the foundations of the decentralized electoral network itself, while in-person voter fraud requires only the infiltration of a singular machine or ballot box within a centralized network. The track record of states with vote-at-home proves this point: Oregon, for example, had only 10 instances of voter fraud during the 2016 Presidential election.

In other words, allowing all citizens to vote from home will make our democracy more resistant to fraud as well as more resilient against national emergencies that threaten to impede our citizens’ basic right to vote.

With the evidence stacked against them, Republicans have resorted to other lines of argument to oppose vote-at-home. Sen. McConnell argued during the CARES Act debate that the proposed $2 billion in election grants would “federalize” states’ elections. Only $400 million in election grants were included in the final bill. President Trump also weighed in, saying “Mail ballots, they cheat. OK, people cheat. Mail ballots are a very dangerous thing for this country because there are cheaters” and tweeting “…[MAIL-IN VOTING] WILL ALSO LEAD TO THE END OF OUR GREAT REPUBLICAN PARTY.” This alarmist tweet is not just anti-democratic, but wrong. In a working paper out of Stanford, a team of researchers took advantage of the staggered rollout of vote-at-home in California, Utah and Washington to show that while vote-at-home modestly improved overall election turnout, the additional turnout did not benefit any party disproportionality.

Never has it been more paramount that our democratic institutions preserve their trust between it and the American people. For a small investment – one that will likely pay off in the long-run – Congress can ensure that our elections are safe and secure not just for this November but for generations to come.

PPI Unveils Blueprint for American Resilience

WASHINGTON, D.C. — Looking ahead to the general election campaign this fall, the Progressive Policy Institute (PPI) today rolled out a bold plan for making America’s health care system, economy and social safety net more resilient against future pandemics and national emergencies.

“During the coronavirus pandemic, we’ve learned the hard way that our country needs stronger economic and social shock absorbers,” said PPI President Will Marshall. “Our challenge isn’t just to recover from the present crisis, but to build a stronger, more equitable democracy that will be more resilient against future shocks none of us can foresee.”

In Building American Resilience, PPI’s scholars and policy experts present 14 bold and original proposals for tackling long-festering social inequities and bolstering the capacities of business, government and schools to perform their vital roles during national crises. 

“The 2020 campaign isn’t just a referendum on President Trump’s catastrophic failure to lead the nation in containing the virus,” said Marshall. “It’s also an opportunity for voters to demand action against deep structural problems that our leaders have ignored too long, and that have weakened our nation’s response to the pandemic.”

To that end, Building American Resilience offers radically pragmatic ideas to: 

  • Spur digital manufacturing in America and shorten supply chains for essential goods, such as masks and other personal protective equipment; 
  • Launch a “national reemployment” drive to get everyone back to work as soon as conditions allow, and to make work pay;
  • Drive down the exorbitant cost of medical care so that we can invest more in healthy communities;
  • Create well-paid production jobs and fight climate change by making America number one in electric vehicles;
  • Make the social safety net more resilient against hunger and other problems;
  • Forge a new economic security bargain with gig workers;
  • Install a “fiscal switch” that allows Washington to automatically stimulate during economic downturns and shrink its debts during expansions;
  • Give birth to two million new businesses to replace those that have gone under during the pandemic shutdown; 
  • Invest in resilient cities and metro regions;
  • Fix America’s broken financing model for higher education; 
  • Create a more nimble and accountable K-12 school system;
  • Democratize capital ownership and expand national service;
  • Replace outdated U.S. immigration laws with a “demand-driven” policy that welcomes more willing workers;
  • Make our electoral democracy more resilient by ensuring that every citizen can vote at home.

“Americans have made enormous sacrifices to save lives and keep our health system and economy from collapsing.” the PPI report notes. “If U.S. don’t emerge from this painful period resolved to build a more just and resilient society, this suffering and sacrifice will have been in vain.”

View Building American Resilience by clicking here.

Contact: Carter Christensen, media@ppionline.org.

Spur Digital Manufacturing in America

This piece is part of our Building American Resilience Series.

Resilience is the ability to react quickly to unexpected events. Market economies are inherently resilient because they are decentralized. But by outsourcing too much production to the rest of the world, the U.S. has traded much of its flexibility and resilience for somewhat lower short-run prices. Moreover, we’ve reduced our ability to deal with new sources of unexpected events, including climate change, pandemics, and wars.

Our inability to produce enough N95 masks for healthcare workers, months into the pandemic, is both astonishing and instructive. N95 masks are classic examples of what might be called “middle-tech”—the masks themselves are individually cheap to produce and have no moving parts or electronic components, but the machines to make the masks, including the special non-woven fabric that filters out tiny particles, are precise pieces of equipment that are expensive, time-consuming to build and mainly come from overseas. A resilient manufacturing sector has to have the know-how and the capabilities to build more machines if needed—and it may be that we no longer have enough of the suppliers with the necessary know-how and capabilities to increase our productive capacity in a crisis.

Government statistics clearly show our eroding manufacturing base. Twelve out of nineteen major manufacturing industries shrunk between 2007 and 2019. Over the same stretch, the non-oil goods trade deficit grew by 60% to record levels, showing the gap between what we produce and what we need, and how unprepared we are to deal with potential shocks.

That’s why we propose a “National Resilience Council” to lead a national push to stimulate local production, shorten supply chains, create high-wage factory jobs and make our manufacturing sector more resilient in crises. We have to harness our strength in tech to transform manufacturing for the 21st century. To be honest, we can’t and shouldn’t fight this battle on China’s ground of giant factories supported by government subsidies.

Instead, a resilient manufacturing recovery requires the fostering of flexible, local, distributed manufacturing—relatively small efficient factories that are spread around the country, using new technology, knitted together by manufacturing platforms that digitally route orders to the nearest or best supplier.

The National Resilience Council would be tasked with identifying those industries and capabilities that are strategic, in the sense of improving the ability of the economy to deal with shocks like pandemics, wars, and climate changes. These areas are likely to be underinvested by private sector companies, who quite naturally don’t have an incentive to tackle these sorts of large-scale risks. For example, no single company has an incentive to invest in improving N95 mask technology so that it is easier to scale up production, but the US government does. Or to harken back to an important historic example, the Defense Department’s original motivation for funding the research that led to packet switching and the Internet was to create a decentralized network that would be more survivable in case of nuclear attack.

Shorter, simpler supply chains also help with sustainable production. Long and complicated supply chains require more air and water transportation, generating more greenhouse gases. International shipping alone, especially container ships, accounts for about 2 percent of all carbon dioxide emissions, about the same as Germany. Beyond that, the more links in the supply chain, the more difficult it is for end producers to get a full picture of their carbon emissions.

Our initiative has four parts:

• First, we should double the National Science Foundation’s roughly $8 billion budget, with more of an emphasis on manufacturing-related areas such as materials sciences. That would still put it well below the roughly$40 billion going to the National Institutes for Health.

Such a doubling has been a consistent bi-partisan goal in the past, yet the U.S. has consistently fallen short. For the past two decades more than two-thirds of U.S. private and public R&D spending has gone to infotech and biosciences, while other areas of science and technology have received much less attention. It’s time to make up the shortfall.

• Second, the government can shore up the nation’s supplier base by providing $200 million in low-cost loans and grants to help small and medium manufacturers test and adopt new production technologies, including digital advances such as robotics and additive manufacturing. Even in a low-interest rate environment, capital is relatively scarce for companies that are too small to tap the bond market.

A somewhat similar initiative to provide loan guarantees for investment in innovative manufacturing technologies, authorized under the America COMPETES Act and supervised by the Commerce Department, never got off the ground because of excessively restrictive terms. Under our proposal, the loans and grants to small and medium companies would be tied to improving the resilience of the manufacturing base.

• Third, the National Resilience Council should sponsor a Manufacturing Regulatory Improvement Commission, along the lines that PPI has suggested in the past. We have no desire to roll back essential environmental and occupational health regulations. But we do want to consider whether rules governing manufacturing have become so restrictive as to unnecessarily force out jobs.

• Fourth, the federal government should take the lead to create a common “language” so that product designers, manufacturers, and suppliers can more easily work together online, just like DARPA helped create the basic structure of the Internet in the late 1960s. Just as a young person can write an app, put it online, and find users around the world, it should be possible to create a design for a new product and easily find potential local manufacturers.

The first two parts of our “National Resilience Council” initiative, which were laid out in our 2019 policy brief, “Jumpstart a New Generation of Manufacturing Entrepreneurs”, find echoes in Joe Biden’s excellent plan for boosting U.S. manufacturing. Key elements that we support include his proposals for bringing back critical supply chains to America, boosting worker training, increasing R&D investment, building up the Manufacturing Extension Partnership, and providing capital for small and medium manufacturers.

Biden’s “Buy America” initiative is understandable, given the stunning size of the trade deficit. But in the long run, improving resilience is more about improving America’s manufacturing capabilities than it is about restricting trade. Globalization and the development of new sources of supply, like India, can be a plus for resilience as long as we keep investing at home.

Moreover, one key word is essentially missing from Biden’s plan: Digital. His proposals make no mention of digital manufacturing, cloud computing, 3D printing, or all the other technologies that have the potential to create new business models for America’s factory sector.

The key is connectivity. Twenty-five years ago the rise of the Internet connected computers and made all sorts of new businesses possible, creating millions of jobs. Now it’s time to make even the smallest factory in Ohio or Michigan part of a larger manufacturing network that can compete on a level playing field with larger foreign competitors.

Some manufacturing networks or “platforms”, with names like Xometry and Fictiv, are already starting to sprout. Such platforms can make it easier for buyers to find domestic suppliers who have the necessary capabilities, and then to shift producers quickly when shocks hit or when it becomes necessary to lower carbon emissions. Such platforms can also give manufacturing startups access to immediate markets, make it easier for entrepreneurs to create well-paying factory jobs.

But this transformation of manufacturing is not happening fast enough to help American workers. The government has an important role to play leading the way to the Internet of Goods.

Building American Resilience: A Roadmap for Recovery After COVID-19

For Americans and much of the world, 2020 has been an annus horribilis. Following its outbreak in China late last year, the coronavirus has spread quickly across the main international travel and trade routes. To contain the pandemic, nations have been forced to order mass quarantines, freezing economic activity and social life. It likely will take decades to calculate the full human, economic and psychic costs of this still-unfolding global calamity.

Few countries have been spared the ravages of Covid-19, but no country has been hit harder than the United States. At this writing, coronavirus has killed more than 156,000 Americans, and infected more than 4.6 million. And with the pandemic spreading rapidly across the South, West and Midwest – 39 states report sharp increases in infections – the end is nowhere in sight.

Stay-at-home orders and social distancing have put the world’s biggest economy on life support. After shrinking by 5 percent in the first quarter of 2020, U.S. output plunged by nearly 10 percent in the second quarter. Since March, more than 42 million Americans have filed for unemployment and nearly 20 million are still out of work. As many as 40- percent of the virus-related layoffs could become permanent, according to a University of Chicago study.

Many small businesses have gone under, and millions more are treading water. “Data from credit-card processors suggest that roughly 30 percent of small businesses have shut down during the pandemic,” reports The Atlantic. And many large companies in sectors hit directly by social distancing – travel and tourism, restaurants and hotels, and brick and mortar retail – have announced layoffs and permanent workforce reductions.

The federal government has borrowed and spent prodigiously to combat the virus, put money in peoples’ pockets and keep the economy from cratering. Congress so far has passed three major relief bills and is wrestling over the scope of a fourth. Washington has spent $3 trillion and could be headed toward a staggering annual deficit of $5 trillion or more, the largest since World War II. Amid this unprecedented public health and economic crisis, an old American dilemma – racial injustice – has reared its head. The unconscionable killing of George Floyd, Breonna Taylor and other black Americans by police has triggered widespread public outrage and protests.

THE CRISIS IN U.S. DEMOCRACY

Intensifying all three of these traumatic shocks is a catastrophic failure of national leadership. In past crises, leaders of extraordinary skill and character have arisen to steer our republic through the storm. Not this time. President Donald Trump has run the ship of state aground.

As the coronavirus first appeared, he sought refuge in denial and dissembling. When that did nothing to halt the spread of the virus, he passed the buck to governors and refused to mobilize the full powers of the federal government to supply tests, masks and ventilators, and to help the states set up rigorous contact tracing systems. Learning nothing from his early blunders, Trump has continued to dismiss the severity of the virus, tout phony cures, and demand premature openings of the economy and schools.

Trump’s incompetence cost our country precious weeks when the federal government should have been taking vigorous action to contain the pandemic. The delay was deadly: Had we started social distancing and locking down on March 1 rather than March 14, 54,000 fewer Americans would have died, according to disease modelers at Columbia University.

Elections really do matter. If the United States had elected leaders as capable as those in Germany, South Korea and Japan, many fewer Americans would be getting sick and dying today. And with contact tracing, masks and selective social distancing, we could keep more of our economy up and running.

As demonstrations against police brutality and racial discrimination flare up around the country, Trump again has displayed a perverse talent for inciting social rancor and pitting Americans against each other. He has smeared protesters as “domestic terrorists” and, over the protests of Mayors and Governors, dispatched unbadged federal security guards to put down the phantom threat of mass anarchy in the streets.

Finally, with a crucial national election approaching, Trump is trying to deny Americans the right to vote safely at home. He’s falsely crying fraud to undermine public confidence in the legitimacy of our electoral system, even to the point of issuing a preposterous call to postpone the vote.

No wonder America’s nerves are frayed. At this fateful moment of intersecting crises – threatening our health, prosperity and cultural cohesion – our country is saddled with a dishonest, incompetent and malicious demagogue who specializes in creating chaos rather than solving problems. Here and abroad, the impression is growing that America is becoming a failed state.

DON’T COUNT AMERICA OUT

But that’s wrong. For all our dilemmas, America remains a resourceful and dynamic country capable of swift course corrections. Beneath our fractious politics lies a bedrock of shared belief in liberty, equality and democracy. We also draw strength from a diverse and inventive citizenry jealous of its freedoms. Time and again, this country has shown it can bounce back from adversity stronger than before. Now we have to reinvent ourselves again.

Fortunately, there is a national election this fall. The American people can fire a sham president and his cowed GOP lackeys and replace them with genuine leaders who can unite us and make our democracy work.

But new leaders also need a new vision.
The United States has received a series of extraordinary shocks in this still-young century: the dot-com bust, 9/11, the great recession and financial meltdown of 2007-8, and now coronavirus, a hobbled economy and civil strife over endemic racism.

We’ve learned the hard way that our country needs stronger economic and social shock absorbers. Our challenge isn’t just to recover from the present crisis, but to build a better, more equitable democracy that will be more resilient against future shocks no one can foresee.

Americans have made enormous sacrifices to save lives and keep our health system and economy from collapsing. Many have stood by helplessly as friends and relatives have died lonely deaths in isolation. The psychological toll also has been heavy: Research by The Society for Human Resource Management finds that one in four workers report feeling either hopeless or depressed. If U.S. leaders don’t emerge from this painful period resolved to build a more just and resilient society, this suffering and sacrifice will have been in vain.

CONFRONTING ENTRENCHED INEQUITIES

The fight against Covid-19 has not been borne equally by all Americans. Health care and emergency workers and those in “essential” industries (such as meatpacking and grocery stores) have been exposed to higher risks of falling ill. The chief victims of Covid-19, by far, are older Americans. Thus far, 43 percent of deaths have been linked to nursing homes.

The pandemic also has taken a severe toll on low-income and minority communities, where many suffer from health problems associated with poverty and discrimination. African-Americans are dying from Covid-19 at a rate nearly twice as large as their share of the population. At this writing, blacks (13 percent of the U.S. population) account for 24 percent of all deaths.

The economic pain inflicted by the pandemic also has been unevenly distributed.

The lockdown, in fact, has exposed a new class divide in America. On one side are office workers, mostly college-educated, well-paid and digitally enabled, who have been able to keep working from home, and to have food and other goods delivered to them. On the other side are low-paid service, hospitality and retail workers, who can’t work remotely. Young workers, immigrants and Hispanic workers have been hit hardest by Covid-19 job losses.

Minority-owned businesses, often smaller and more precarious, have been damaged disproportionately by the pandemic. The National Bureau of Economic Research reports that, between February and April, there was a 41 percent decrease in black business owners and a 31 percent decrease in Latinx business owners, compared to an overall decline of 22 percent.

The pandemic also has exposed serious weaknesses in our private economy. Because of offshoring and long supply chains, for example, U.S. factories were unable to supply masks, gowns, gloves and ventilators in a timely way to health care workers desperately battling the virus.

Key public sector systems, long starved of investment and entangled in red tape, also have failed to respond nimbly to the crisis. Archaic computer systems in state Unemployment Insurance offices crashed as applications surged. The Center for Disease Control and Prevention, our front-line agency against pandemics, not only sent out flawed coronavirus tests, but also allowed bureaucratic inertia to delay the production of reliable tests by private laboratories.

Tens of millions of young children and older students have lost months of early learning and classroom instruction as schools of all kinds have closed. Some K-12 school systems used virtual learning to mitigate the loss, but many either did not have that capacity or chose not to use it to avoid discriminating against low-income families without computers or internet access.

Through the free and reduced price lunch and breakfast programs, public schools also play a critical role in feeding needy children. While some schools improvised “grab and go” programs to provide meals to kids, 80 percent report serving fewer meals, and only 22 percent offered meals two days a week. School closings thus have contributed to an upsurge in hunger in poor communities, even as they interrupt all childrens’ education.

A BOLD BLUEPRINT FOR RECOVERY AND RESILIENCE

In contrast to Trump’s “let’s get back to the way things were” message, progressive leaders should offer voters this fall an ambitious vision for America’s economic and social reconstruction. In this report, PPI presents a blueprint for speeding recovery and building a more resilient society. It tackles long-festering social inequities and bolsters the capacities of business and government to perform their vital missions during future pandemics or other national emergencies. Applying what we have learned during the Covid-19 crisis, our scholars and policy experts offer radically pragmatic ideas for change:

• Spur digital manufacturing in America and shorten supply chains for essential goods.

• Launch a “national reemployment” drive to get everyone back to work as soon as conditions allow, and to make work pay.

• Drive down the exorbitant cost of medical care so that we can invest more in healthy communities.

• Create well-paid production jobs and fight climate change by making America number one in electric vehicles.

• Make the social safety net more resilient.

• Forge a new economic security bargain with gig workers.

• Install a “fiscal switch” that allows Washington to automatically stimulate during economic downturns and shrink its debts during expansions.

• Give birth to two million new businesses to replace those that have gone under during the pandemic shutdown.

• Invest in resilient cities and metro regions.

• Fix America’s broken financing model for higher education. • Create a more nimble and accountable K-12 school system.

• Democratize capital ownership and expand national service.

• Replace outdated U.S. immigration laws with a “demand-driven” policy that welcomes more willing workers.

• Make our electoral democracy more resilient by ensuring that every citizen can vote at home.

Find each report of our series, Building American Resilience, below:


INTRODUCTION: BUILDING AMERICAN RESILIENCE

Will Marshall

SPUR DIGITAL MANUFACTURING IN AMERICA 

Michael Mandel

GET EVERYONE BACK TO WORK – AND MAKE WORK PAY 

Will Marshall

INVEST IN A HEALTHIER AMERICA 

Arielle Kane

MAKE AMERICA #1 IN ELECTRIC VEHICLES

Paul Bledsoe

WEAVE A STRONGER SAFETY NET POST-COVID 

Crystal Swann

MAKE THE GIG ECONOMY MORE RESILIENT

Alec Stapp, Michael Mandel

CREATE A “FISCAL SWITCH” TO MAKE OUR ECONOMY MORERESILIENT AGAINST RECESSIONS

Ben Ritz

CREATE TWO MILLION NEW BUSINESSES

Dane Stangler

INVEST IN METRO RECOVERY AND RESILIENCE

Crystal Swann

FIX HIGHER ED’S BROKEN MODEL

Paul Weinstein, Jr.

CREATE MORE INNOVATION SCHOOLS

David Osborne

DEMOCRATIZE CAPITAL OWNERSHIP 

Jason Gold

SHIFT TO “DEMAND DRIVEN” IMMIGRATION

Dane Stangler

MAKE ELECTORAL DEMOCRACY MORE RESILIENT

Colin Mortimer

Post-Pandemic, Joe Biden Needs to Rethink His K-12 Education Plans

The Covid-19 pandemic has shown people some real flaws in our public education systems. If Joe Biden is elected, will he fix them?

Many school districts had trouble adapting to the sudden closure and were never able to deliver effective distance learning. Many parents were surprised how low schools’ expectations were and disappointed by the quality of education their children were receiving.

Different children had very different experiences with distance learning. Even more than usual, they will arrive at school next fall with different needs. Batch processing—teaching an entire classroom the same thing at the same pace—will work even worse than usual.

We need an education system that is adaptable, that meets all students where they are, that helps them move at a pace that works for them, and that has high expectations for all of them. As many schools have demonstrated, children rise to the expectations we set for them.

As we reopen schools, we shouldn’t simply restore the old public education system. We should aim higher and apply the lessons of the last four months to building a more flexible, resilient K-12 school system.

Read more here.

Conversation with Rep. Sharice Davids and Rep. Scott Peters on Rebuilding America’s Fiscal Strength

PPI President Will Marshall and Ben Ritz from the Center for Funding America’s Future are joined by Congresswoman Sharice Davids (KS-3) and Congressman Scott Peters (CA-52) for a conversation on the fiscal health of the United States, budget priorities, the election, and their perspective on how America’s economy can return with a resilient recovery.

A vision for independent workers

A slice of bread is good, but a whole loaf is better. In the spring, Senator Mike Braun of Indiana introduced the Helping Gig Economy Workers Act to shield digital companies from lawsuits on worker classification when providing protective equipment during the coronavirus pandemic. This legal “safe harbor” for such digital companies could find its way into the Republican stimulus package under consideration in Congress.

But independent workers around the country, including freelancers and sole proprietors, need much more than protective equipment. They need access to a universal baseline level of benefits, paid for by the companies they work with, without losing the work flexibility they value. They need a new regulatory framework that is suited for the 21st century labor market rather than the 20th century labor market. Reaching these goals requires legislation, but it is very different from what Braun is proposing.

First, it is important to realize that while independent contractors receive tax deductions with expenses like vehicle miles, the tax system penalizes independent workers who provide their own benefits. Most independent workers must pay Social Security and Medicare taxes on the money they contribute to their retirement accounts. By contrast, the contribution of employers to their employee retirement accounts is exempt from these taxes, subject to certain rules. Indeed, this tax exemption can be worth thousands of dollars for middle income workers. Similar problems also arise with health insurance coverage for independent workers.

Second, the companies that do business with independent workers are not able to provide benefits because then the Internal Revenue Service would classify the workers as employees, leading to the loss of flexibility and control over their hours and who they can work for. Such a shift with status would likely reduce the number of available jobs. Those remaining workers would have fixed schedules, capped hours, and inability to work with more than one company. It is obvious that these tax and regulatory barriers weaken the labor market position of independent workers since benefits are more expensive and difficult for them to receive.

Read more here.

PODCAST: Conversation with Rep. Sharice Davids and Rep. Scott Peters

Listen on Breaker.

Listen on Google Podcasts.

Listen on Overcast.

Listen on Pocket Casts.

Listen on Radio Public.

Listen on Spotify.

PPI President Will Marshall and Ben Ritz from the Center for Funding America’s Future are joined by Congresswoman Sharice Davis (KS-3) and Congressman Scott Peters (CA-52) for a conversation on the fiscal health of the United States, priorities for the upcoming stimulus bill, the election, and their perspective on how America’s economy can return with a resilient recovery.

10 Myths About Big Tech & Antitrust

On Wednesday, the House Subcommittee on Antitrust will hear testimony from the CEOs of Amazon, Google, Facebook, and Apple. Throughout the long pandemic shutdown, Big Tech has supplied the products and services that allow many Americans to keep working remotely and to stay in touch with family and friends while socially distancing. Our connectedness is one of the few bright spots in this ordeal. It’s an odd moment for lawmakers to be expending energy on castigating America’s most innovative and globally competitive companies, simply because they are big. 

However, critics of the tech giants have labeled them “monopolies” and increasingly advocate for regulators to break them up. With that in mind, here are 10 myths about Big Tech and antitrust you should be aware of before tuning in to the hearing.

Myth #1: “Big Tech companies are monopolies”

There is a difference between the layperson’s use of “monopoly” and the technical meaning of the term. In casual commentary, “monopoly” is often used interchangeably with “large” or “dominant” when describing a company. But the term has a much more precise legal definition, and future court cases will hinge on its technical rather than colloquial meaning. According to DOJ guidelines, a company has monopolized a market when it has “maintained a market share in excess of two-thirds for a significant period and market conditions (for example, barriers to entry) are such that the firm’s market share is unlikely to be eroded in the near future.” The tech companies are not above that threshold:

  • Amazon has 38% of the US e-commerce market, including first party sales and sales from third parties on the Amazon Marketplace.
  • Apple has 58% of the US smartphone operating system market.
  • Google has 29% of the US digital advertising market
  • Facebook has 23% of the US digital advertising market.

Amazon is actually a surging competitor in digital advertising, and has an estimated 10% market share this year. It is deeply ironic that multiple Big Tech companies have been accused of monopolizing the advertising market at the same time. In reality, the largest player — Google — has less than a third of the market. The second largest — Facebook — has less than a quarter of the market. And Amazon is nipping at their heels.

Critics of Big Tech often try to define arbitrarily narrow markets to show a market share in excess of two thirds. That’s why you’ll hear that Google has “89-93%” of the US digital search advertising market or a large share of the “US digital display advertising market” or the “US digital video advertising market.” What these critics fail to show is why these should be distinct antitrust product markets. Advertisers maximize return on investment. If prices increase in one advertising channel, they likely substitute that spending to other channels. If anything, the simultaneous rise of digital advertising and fall of print advertising — while other advertising channels have remained flat — suggests that “US digital advertising” might be too narrow of a market. It seems that advertisers are substituting digital advertising for print advertising. A good rule of thumb in antitrust is that the more adjectives someone tries to use to define a market, the less likely it has any relation to economic reality.

It’s also important to remember that in digital markets users often multi-home, meaning they use multiple services in the same market. For example, the average person has nine social media accounts. Take a look at your phone. How many messaging apps do you have? How many social media apps do you have? What about email? Does one company really have a monopoly on how you communicate with your friends, family, and coworkers? Does one company have a monopoly on the entertainment you consume? The answer for most people is no.

Myth #2: “Big Tech harms consumers”

Next, let’s look at consumer harm. According to DOJ guidelines, an antitrust enforcer must show that a company has used its monopoly power to “harm society by making output lower, prices higher, and innovation less than would be the case in a competitive market.” But prices in digital markets have been falling (or at zero) for years.

  • The price of digital advertising has fallen more than 40% in the last decade (while the price of print advertising has increased 5% over the same period).
  • The price of books has fallen more than 40% since 1997, the year Amazon went public.
  • Social media and messaging apps are priced at zero.

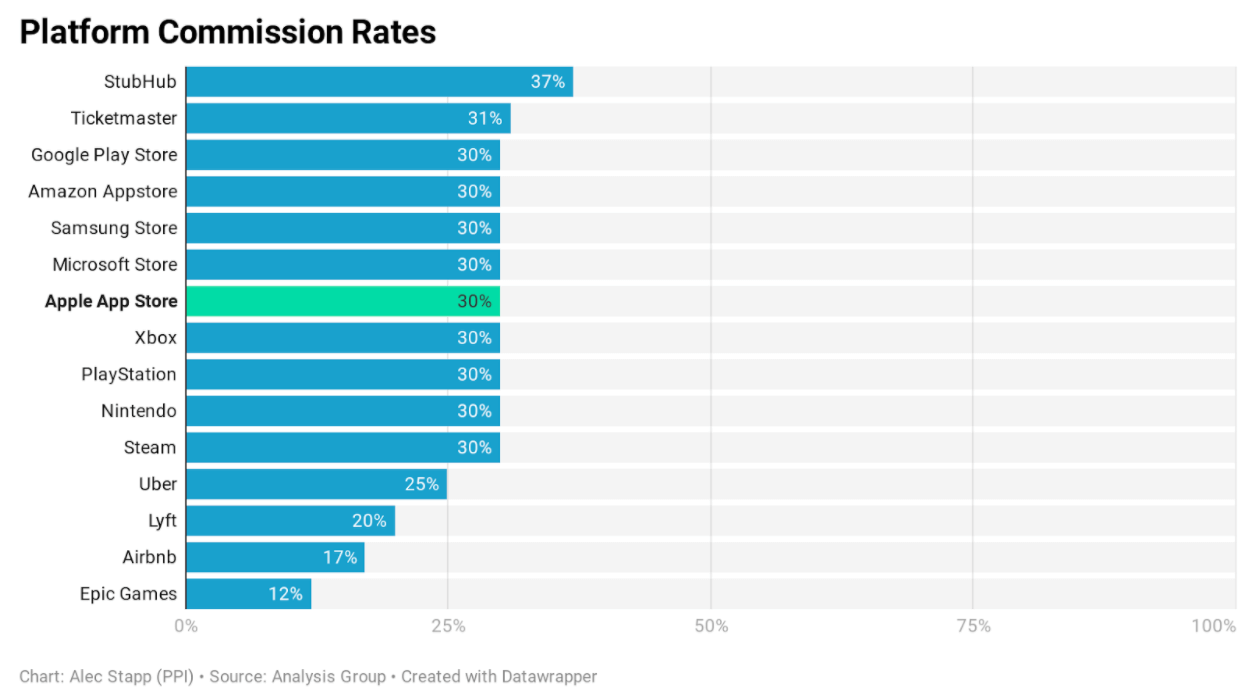
Apple’s 30% App Store “tax” is actually the going rate for platform commissions (and once you account for the revenue generated by free apps, effective app store commission rates are in the range of 4-7%).

While the prices for these services are low or even zero, consumers value them a great deal. Research has shown that, on average, consumers value search engines at $17,530 per year, email at $8,414 per year, digital maps at $3,648 per year, and social media at $322 per year. Again, the price to access these services is typically zero.

Myth #3 “Big Tech doesn’t innovate”

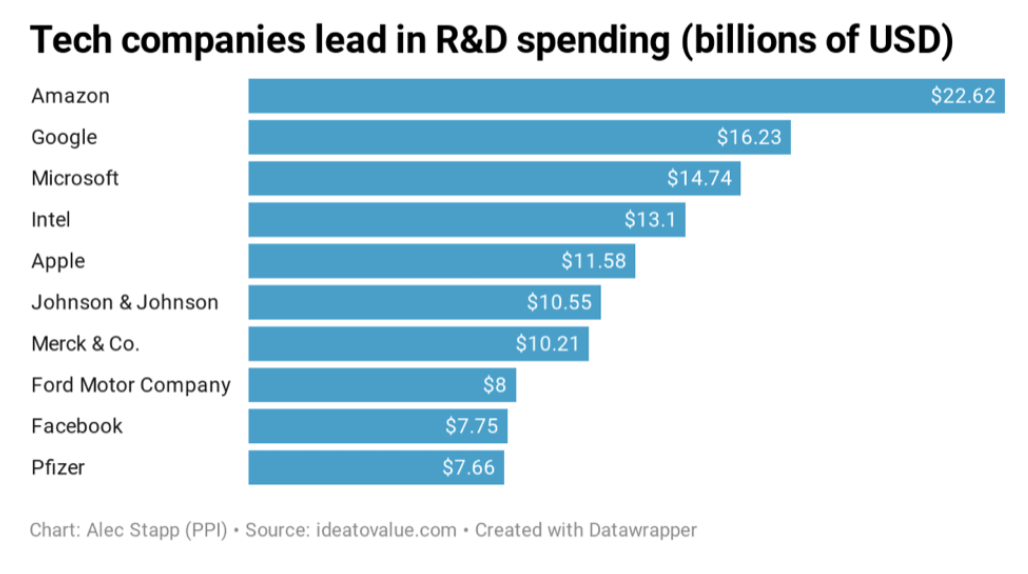
But what about innovation? It’s a hard thing to measure directly. One proxy variable we can look at is spending on research and development (R&D). A complacent incumbent harvesting monopoly rents tends not to invest much in the future. By contrast, in a competitive marketplace, even the dominant firms are nervous they will be unseated by nascent or potential competitors. To prevent that from happening, they invest in the next generation of technology that will benefit consumers.

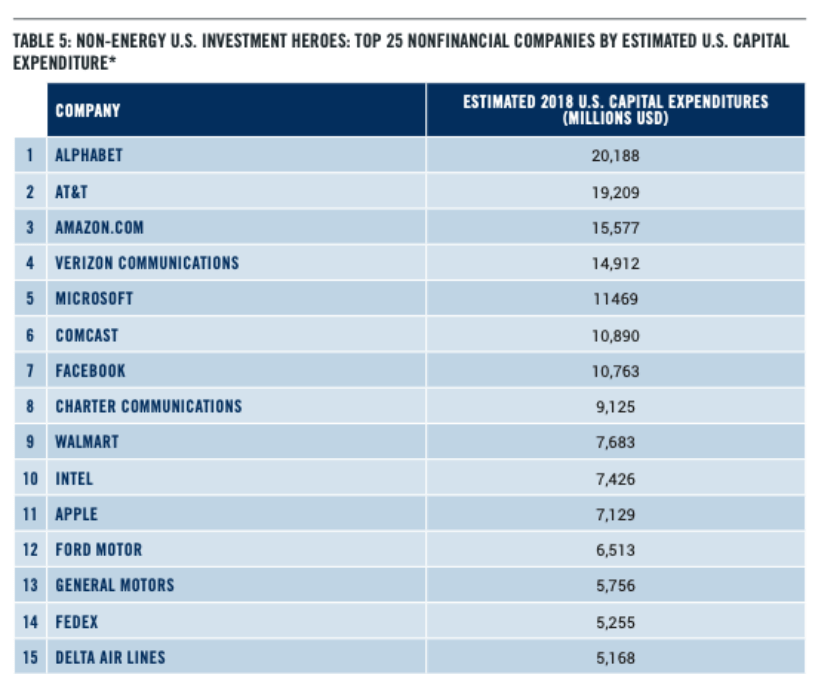
Another metric that’s worth looking at is capital expenditures. The line of reasoning here is similar: a monopolist secure in its market position would rather distribute profits to shareholders than make risky investments. Here again, the tech companies lead the country in spending in this category, according to the Investment Heroes report by Michael Mandel and Elliott Long at PPI.

Myth #4: “Network effects make Big Tech unbeatable”

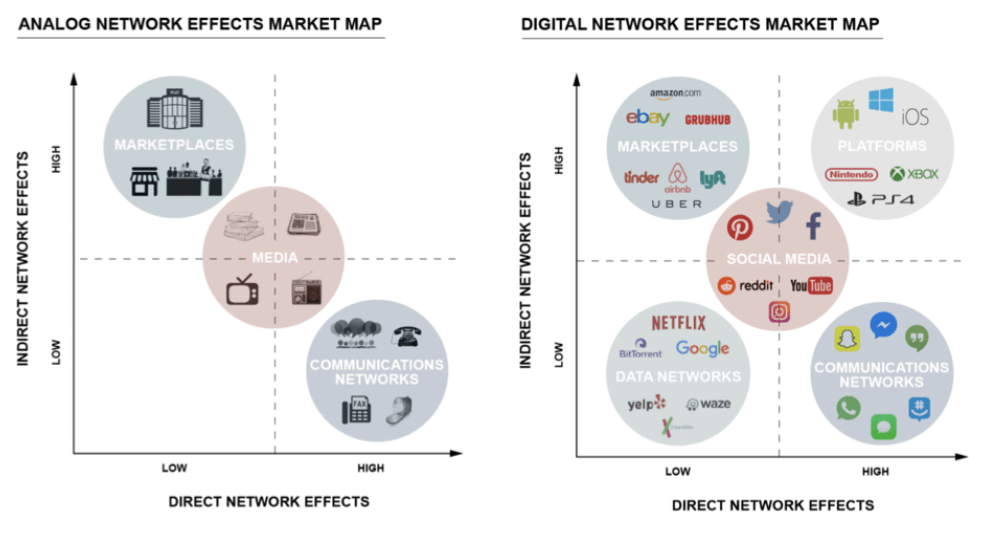
Critics claim that digital markets are different because they have network effects. Network effects are when a service becomes more valuable to each individual user as more users join the network. Telephones are a classic example. A telephone is only valuable insofar as there are other people who also own telephones. A similar dynamic exists for many tech platforms. There are also “indirect” network effects, where one group of customers cares about how many people are in another, distinct group of customers.

For example, operating systems such as iOS and Android need to cater to two different groups — smartphone users and app developers. Smartphone users want to use operating systems that have a lot of apps. App developers want to develop apps for operating systems that have a lot of users. It’s a virtuous cycle. And if there are high switching costs for users or if there are large platform-specific investments that developers need to make, then the equilibrium number of competitors in the market might be only one or two firms.

There are three important facts about network effects to keep in mind. First, network effects are nothing new. As shown in the chart above, many legacy markets have network effects, including fax machines, newspapers, television, shopping malls, and even nightclubs. Second, while network effects can be a source of market power, they can also create large consumer benefits. Breaking up incumbent networks would also destroy these benefits along with dispersing market power, as users lose the positive spillovers from having everyone on the same platform. Lastly, network effects also work in reverse. If a large network begins to lose users, it can quickly unravel as the service becomes less valuable to the remaining users.

Myth #5: “Big Tech is killing the startup ecosystem”

Some Big Tech critics believe the companies create a “kill zone” around their businesses. The hypothesis is that the Big Five are so dominant in their respective markets, no venture capitalists will fund startups to compete with them. Over time, as the tech giants grow and branch out into new markets, we should expect the startup ecosystem to shrivel up and die. This theory is contradicted by numerous prominent examples, including Shopify competing successfully with Amazon and TikTok with Facebook.

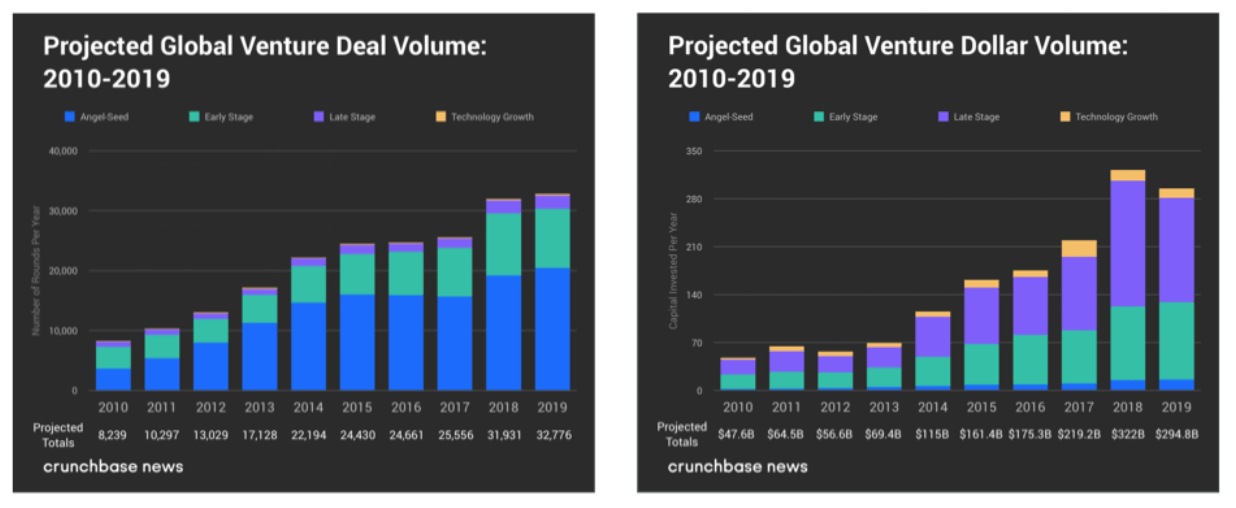
The data on the overall venture capital investment tells a different story. The number of venture capital deals in 2019 reached an all time high of 32,776. The total dollar value of those deals was just slightly off the all time high set in 2018. It seems more likely that startups will die from suffocating on cash than thirsting for liquidity (every Sotbank unicorn investment comes to mind).

And while there is some evidence that venture capitalists are slightly less likely to invest in startups directly competing in a core market for tech giants, this story from Will Rinehart about Google’s founding shows that competition from startups often starts in one narrow market and expands from there:

Google faced a similar environment when it was trying to get off the ground in the late 1990s. Ram Shriram, one of the earliest investors in Google, recently recalled that “I went up and down Sand Hill and could not get a single VC to get a check at the time. The reason? They said search was taken.” Michael Moritz, another early investor in Google, confirmed Shriram’s sentiment and continued by explaining that, “Companies start off with a very narrow focus, and they do one small thing very well, and then they become the best at it, and then they gradually expand.”

As startups get bigger and search for new opportunities for growth, they might increasingly cast their eyes on the cash flows currently enjoyed by Big Tech.

Myth #6: “Big Tech companies only compete in one market”

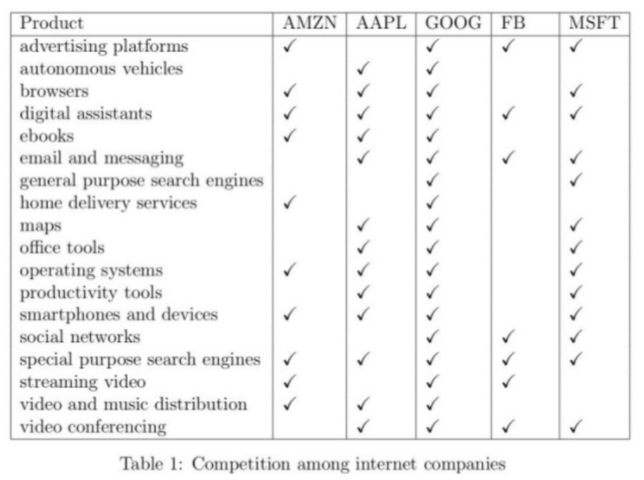
An underrated source of competition for the tech giants is each other. While each of the Big Five has its core area of strength, they are constantly making incursions on each other’s territory and jockeying for position. As the table shows, for every product or service, there are at least two Big Tech companies offering a competing service (and in many markets it’s four companies). The latest example of this: Google lowered its commission fees to zero on products sold via the ‘Buy on Google’ checkout option and started allowing retailers to use third-party payment and order management services like Shopify. All in the pursuit of challenging Amazon in e-commerce.

Myth #7: “Data is a significant barrier to entry to competing with Big Tech”

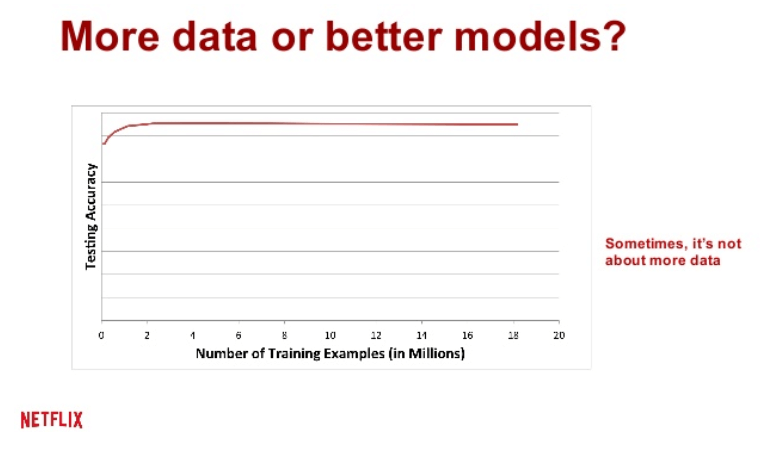
People like to say that “data is a barrier to entry.” But the barrier is much smaller than many think. When data is used as an input for an algorithm, it shows rapidly diminishing returns, as the charts collected in a presentation by Google’s Hal Varian demonstrate. The initial training data is hugely valuable for increasing an algorithm’s accuracy. But as you increase the dataset by a fixed amount each time, the improvements steadily decline (because new data is only helpful insofar as it’s differentiated from the existing dataset).

As the chart above shows, using a real world case of a machine learning algorithm in production at Netflix, adding more than 2 million training examples had very little to no effect. That means the key differentiator is often the quality of the model, not the quantity of data used to train it. And how do you engineer a better model? By hiring top-level machine learning scientists. In the end, the binding constraint is still the humans.

As I’ve written previously, data is not “the new oil.” Data is not like a commodity. It is more akin to a public good — non-rivalrous and non-excludable. For example, if you tell someone your birthday — a discrete piece of personal data — you can’t exclude them from sharing it with other people. And by telling them you have not diminished some finite supply of “birthday tellings.” That piece of information can be shared over and over. And since data is a quasi-public good, that means it is likely underprovided by the market. Private companies can’t capture the full benefits of investing in collecting, processing, and using data. If anything, policymakers should be concerned with how they can promote the safe sharing of more data rather than less (by making it more excludable).

Myth #8: “Stock market concentration is at an all-time high due to Big Tech”

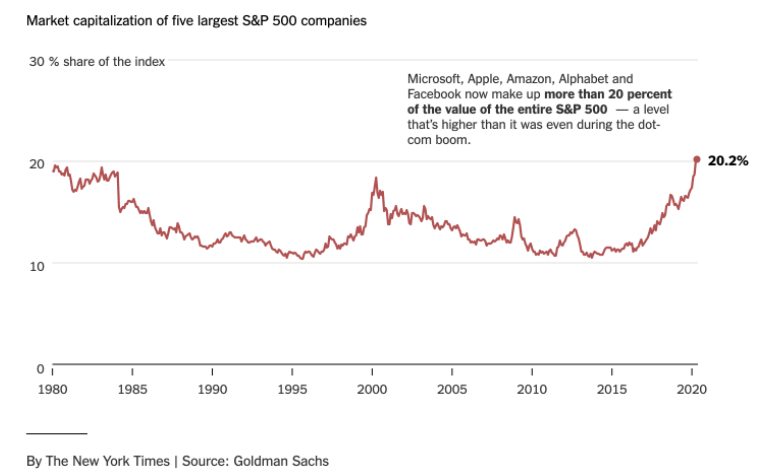
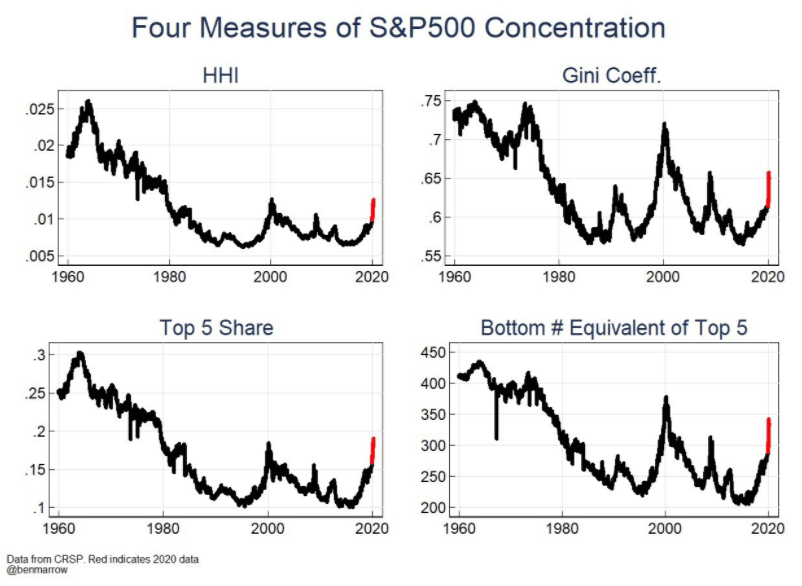
The New York Times and the Financial Times have published articles recently sounding the alarm about the rising concentration in public markets, as measured by the share of the S&P 500 accounted for by the five largest companies in the index (currently Microsoft, Apple, Amazon, Google, and Facebook). The takeaway from these pieces is that concentration is at an all-time high and that it’s unsustainable. But the charts that accompany these articles always seem to start around 1980. What happens if you extend them back further to get more historical context?

As you can see, concentration in the 1960s and 1970s was much higher than it is today. It was normal for the top 5 largest companies to account for more than 20% of the S&P 500, and they even exceeded 30% around 1965. The current level of concentration is not a historical outlier.

Myth #9: “The American public hates Big Tech (‘techlash’)”

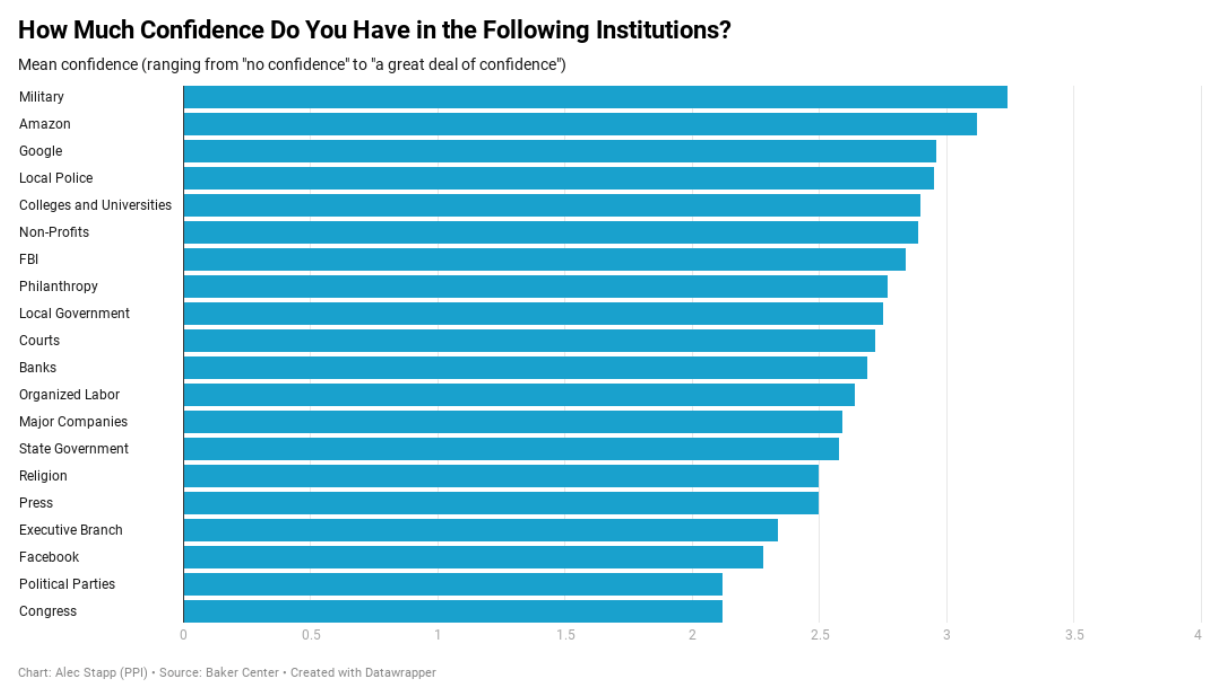
In survey after survey, Americans say they approve of the tech companies, trust them more than companies in other industries, and don’t think politicians should prioritize regulating them more. According to a survey from The Verge, 91% of Americans have a favorable view of Amazon; 90% have a favorable view of Google. According to a poll by the National Research Group, 9 in 10 Americans have a better appreciation for tech during the pandemic. As shown in the chart below, when Georgetown University surveyed Americans on which institutions they had the most confidence in, Amazon and Google ranked second and third respectively, only behind the military. The institution Americans have the least confidence in? Congress.

Myth #10: “It was obvious that some approved Big Tech acquisitions were anticompetitive”

Some critics have claimed that Big Tech engages in “killer acquisitions” and anticompetitive mergers intended to acquire and maintain a monopoly position in the market. This NYT article points out that Google has made 270 acquisitions and Facebook has made 92 acquisitions. The large numbers are supposed to be taken as prima facie evidence of a competition problem. But many of these acquisitions are really just “acqui-hires,” or when one company purchases another for its engineering talent rather than its proprietary technology. As Ben Thompson points out, these exits act as a safety net that encourages entrepreneurs to be more risky in their ventures: “[I[t might have been easier to simply apply for a job at Google or Facebook, but being handed one because you worked for a failed startup reduces the risk of going to work for that startup in the first place.”

Acquisitions are also an essential part of a healthy startup ecosystem. Startups generally have two methods for achieving liquidity for their shareholders: IPOs or acquisitions. According to the latest data from Orrick and Crunchbase, between 2010 and 2018 there were 21,844 acquisitions of tech startups for a total deal value of $1.193 trillion. By comparison, according to data compiled by Jay R. Ritter, a professor at the University of Florida, there were 331 tech IPOs for a total market capitalization of $649.6 billion over the same period. Those liquidity events reward investors and employees for taking risks and incentivize the next round of startup financing.

But the main problem with labeling past acquisitions “anticompetitive” — even if they were reviewed by antitrust authorities and explicitly approved at the time —  is hindsight bias. Because Instagram now has more than a billion users and is arguably a more valuable asset to Facebook than its legacy social network, critics are implicitly claiming that Instagram would have experienced the same success as an independent company. In other words, its success was a foregone conclusion.

Nothing could further from the truth. A cursory review of the historical record makes it clear how much doubt there was at the time about the wisdom of acquiring a photo-filtering app for $1 billion. Instagram had just 30 million users and zero revenue. The company had raised money at a $500 million valuation the day before Zuckerberg made the $1 billion offer. On late night TV, Jon Stewart joked about the acquisition: “A billion dollars of money? For a thing that kind of ruins your pictures? The only Instagram worth a billion dollars would be an app that instantly gets you a gram.”

A CNET article by Molly Wood titled “Facebook buys Instagram…but for what?” had this conclusion:

I still feel like there are more questions than answers to why this price tag makes sense. I hope Facebook isn’t getting distracted by hipster buzz or the photo-sharing bubble, especially at a time when its business decisions need to be as sound as possible to shore up future investor confidence. Don’t spend those billions before you’ve got them, guys.

The same is true for other Big Tech acquisitions. When it comes to a prospective merger, the tech companies are damned if they do, damned if they don’t. If it fails, people call it a “killer acquisition.” If it succeeds, people say the company took out a future competitor.

Conclusion

One of the biggest misnomers in the antitrust discourse is that people presume all monopolies are illegal. According to the FTC,

[I]t is not illegal for a company to have a monopoly, to charge “high prices,” or to try to achieve a monopoly position by what might be viewed by some as particularly aggressive methods. The law is violated only if the company tries to maintain or acquire a monopoly through unreasonable methods. For the courts, a key factor in determining what is unreasonable is whether the practice has a legitimate business justification.

Of course, based on the evidence presented earlier, it is far from clear that the tech companies have even a legal monopoly in any antitrust product market, let alone an illegal monopoly acquired via exclusionary conduct. But it is self-evidently true that the Big Five have been wildly successful and have become dominant in their respective core areas. Upon reviewing the totality of the evidence, the more likely explanation for their size is that they’ve created some of the best products in the market and are more efficient at delivering what consumers want than their competitors.

Given the facts of the market, why would Congress choose to hold a hearing about Big Tech and antitrust at a time like this? Antitrust regulators have been serving as effective watchdogs of actual anti-competitive conduct and should continue to do so in the future. There may be room for behavioral remedies in tech that strike a better balance without blowing up our most valuable and innovative companies. But, of course, that requires more focus on the boring procedural work of careful antitrust analysis — and that doesn’t make good TV.

SEC in Focus: Lack of Diversity Among Asset Managers

In July 16 the Securities and Exchange Commission (SEC) hosted a  on improving diversity and inclusion within the asset management industry.

The SEC doesn’t have a long history of using its powers to focus on diversity, but SEC Chairman Jay Clayton  an optimistic note: “We should continue to ask ourselves how we want participation and representation in our markets to evolve, at all levels,” Mr. Clayton said at the meeting.

But government can’t do it alone. To wit- just 69 of 1,367 entities surveyed by the SEC in 2018  of their diversity policies and practices, according to the agency.

Some diversity advocates  the SEC to increase pressure by declining to meet with firms that ignore its diversity surveys.

While the increase of these discussions by the government is welcome, withholding access to your government is never a good idea.

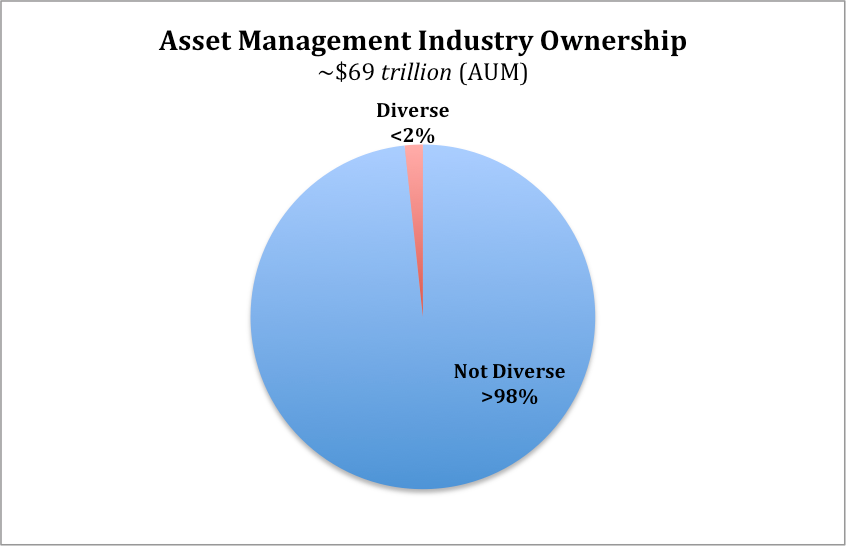
One chart explains the reason the SEC hosted this discussion

Image for post

Why is this chart so important? It speaks to opportunity — which is the essential precondition of equality. Simply put, how can we expect investment capital to flow to minority and women entrepreneurs if it’s not flowing through the hands of diverse capital allocators?

Congressional Red Alert: Local governments need help — ASAP

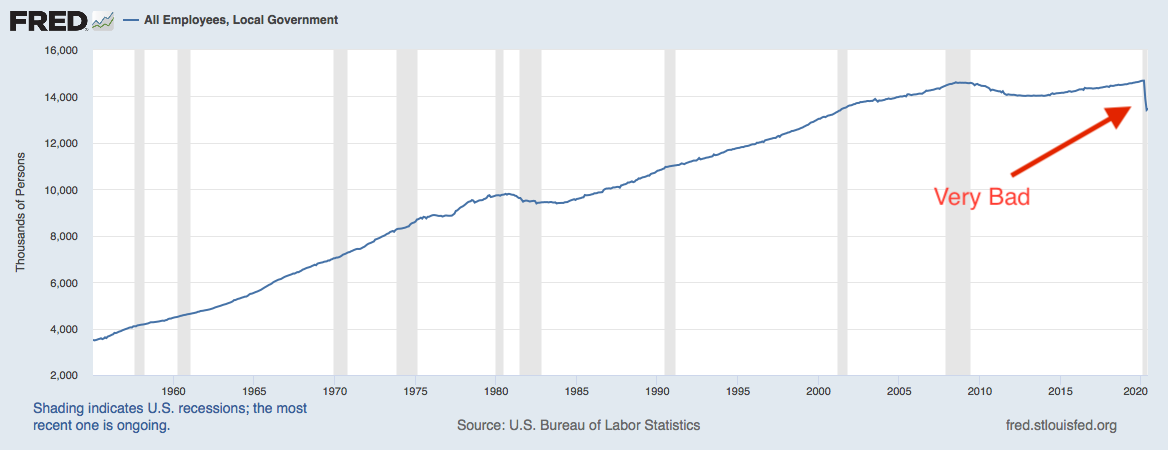
Still not convinced this recession is different? Take a look at this graph from the Federal Reserve of St. Louis:

Image for post

This chilling drop-off is one of several reasons to get emergency funding directly to states and cities in the next stimulus package. The chart dates back to 1955 and shows that local governments who are hemorrhaging money are shedding jobs at a record pace. (Previous recessions are shaded)

In March 2020, local governments employed nearly 14.7 million people. Two months later that number dropped to 13.4 million with more cuts expected soon. Those job losses moved across various sectors including fire, police, teachers, and frontline healthcare workers.

How Amazon advances clean energy goals, while nurturing innovation and shareholder capital

Amazon announced it has  with , a global non-profit working with business to accelerate the clean energy transition.

This push by Amazon is reflective of a larger trend by cash rich companies and is an important focus by businesses that have significant resources to allocate. If you dig closer, you will find more and more of these proposals have a capital investment component in clean energy technology. From the press release:

Climate Pledge signatories will explore investment opportunities, including through Amazon’s Climate Pledge Fund, in companies whose products and services will facilitate the transition to a zero-carbon economy.

New York uses green infrastructure investment to get its economy back on track

Amid a massive economic crisis on the heels of serving as America’s first Covid-19 epicenter, New York’s Governor Andrew Cuomo has  with plans for an historic solicitation of renewable energy via offshore wind farms. Combined with a $400 million multi-port public/private infrastructure investment, these actions are key components to get New York State’s economy back on track and progressing towards its mandate to secure 70% of its electricity from renewable sources by 2030.

“During one of the most challenging years New York has ever faced, we remain laser-focused on implementing our nation-leading climate plan and growing our clean energy economy, not only to bring significant economic benefits and jobs to the state, but to quickly attack climate change at its source by reducing our emissions.” Gov. Cuomo said.

Glaring omission in the CARES Act commission highlighted

Thornell, et al, make a pretty convincing case in  that the oversight commission for the CARES Act as currently constructed, is problematic to help get money needed to the  of minority-owned businesses, hardest hit since the crisis began and overlooked in previous stimulus packages. Why? There are no minorities on the current commission. The solution according to the authors? Add more members to the commission, and this time- include minorities.

From the piece: “No requests were made of the Treasury Department and Federal Reserve Board to explore the array of economic implications for communities of color or inquire about possible strategies to address them. The Treasury and the Fed wield powerful economic tools to manage the pandemic’s devastation on businesses, workers’ livelihoods, family savings, and consumer confidence.”

Agreed. I highlighted similar inclusive governance challenges in an op-ed for  in April arguing why Biden needs some diversity in key economic cabinet posts that have never been led by a minority.

Meanwhile… “Inside the Klubhouse”

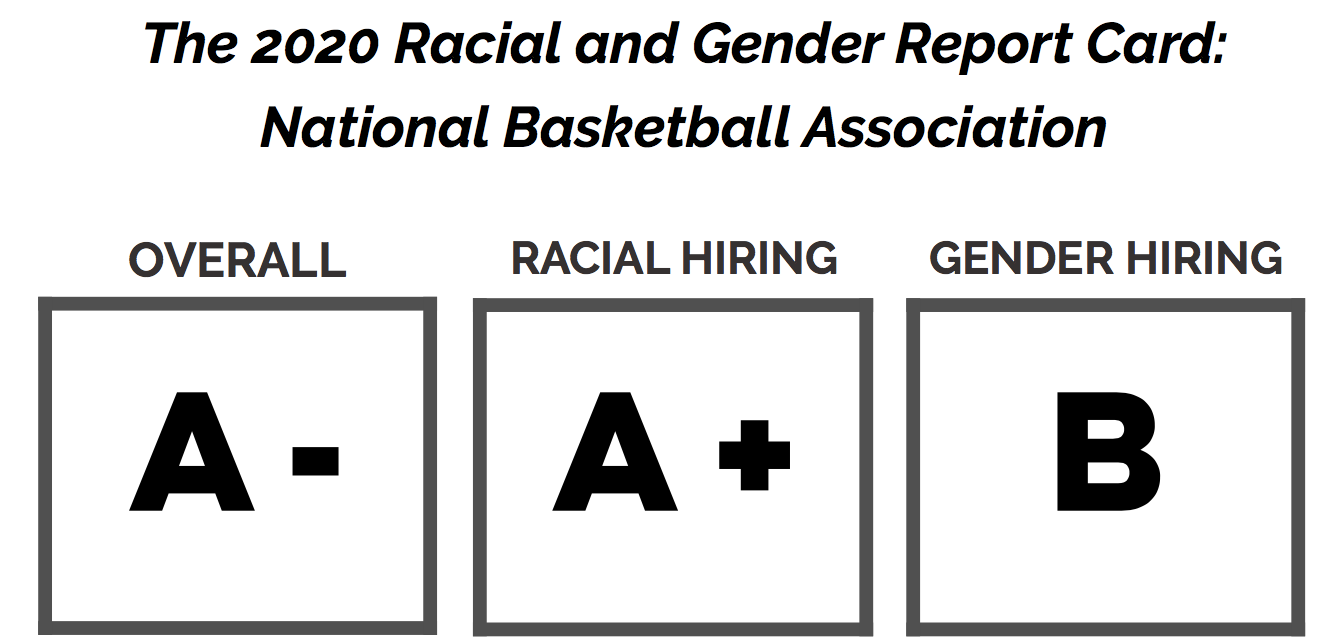
The Institute for Diversity and Ethics In Sport (TIDES) at the University of Central Florida last week released its  for the NBA. Commissioner Adam Silver, owners, and players have been longtime leaders on social issues among all mainstream sports, so these results are no surprise:

Image for post

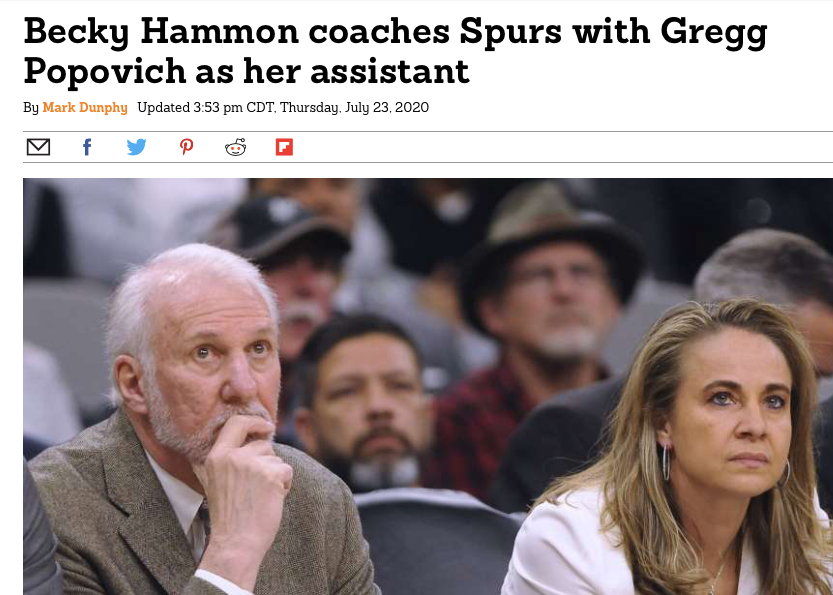
Case in point from the  last week. Coach Gregg Popovich, a 5x Champion, top 3 all time, future hall of fame coach, swapped roles with assistant coach Becky Hammon, who took over head coaching duties for the Spurs against the Milwaukee Bucks.

Image for post

Should we abolish tax returns? A conversation with Sen. Bob Kerrey

Former Senator Bob Kerrey joins the Center for New Liberalism and the Progressive Policy Institute’s Paul Weinstein and Alec Stapp to discuss whether or not the US government should adopt return-free filing for individual taxes.

The participants will discuss the costs and benefits of return-free filing relative to our current voluntary tax filing system, the main problems with our current tax system, and whether or not return-free filing would reduce tax evasion.

Investment Heroes 2020

This post has been updated to include additional data, as well as updating our original preliminary estimate of Microsoft’s capital expenditures to reflect their since-released 10-K report.

Given the ongoing pandemic, capital investment is more important than ever before. Hundreds of billions of dollars of investment by broadband providers enabled the U.S. Internet to respond magnificently to soaring demand when the pandemic hit. On the other hand, some of the sectors that have struggled the most—such as medical equipment and supplies and food production and processing—have suffered from a shortfall of investment.

To emphasize the importance of capital spending for wages and growth, each year the Progressive Policy Institute publishes our list of U.S. “Investment Heroes:” the companies who are investing the most in America. Currently, accounting rules do not require companies to report their U.S. capital spending separately. To fill this gap in the data, we created a methodology using publicly-available financial statements from non-financial Fortune 150 companies to identify the top companies that were investing in the United States.

Table 1 below provides the top 25 non-financial companies, ranked by U.S. capital expenditure in the latest fiscal year through June 30, 2020. Table 2 below provides the top 25 nonfinancial non-energy companies, ranked by U.S. capital expenditure in the latest fiscal year through June 30, 2020 (Our methodology is described in last year’s report. In particular, page 15 of that report describes adjustments made for particular companies). 

We note that 10 out of the top 11 companies in Table 2 are either broadband providers or tech/ecommerce companies. Out of those ten, the broadband providers invested $52 billion in the United States in their most recent fiscal year, while the tech/ecommerce companies invested $84 billion.

Table 1. U.S. Investment Heroes: Top 25 Nonfinancial Companies by Estimated U.S. Capital Expenditure
Rank Company ESTIMATED 2019 U.S. CAPITAL EXPENDITURES (Millions USD)*
1 Amazon.com $19,306
2 AT&T $18,520
3 Alphabet $18,037
4 Exxon Mobil $16,580
5 Verizon Communications $16,058
6 Intel $13,416
7 Facebook $12,457
8 Duke Energy $11,122
9 Microsoft $11,073**
10 Comcast $10,467
11 Chevron $10,062
12 Apple $9,772
13 Walmart $7,904
14 Southern $7,880
15 Exelon $7,248
16 Charter Communications $7,195
17 Ford Motor $6,414
18 Energy Transfer $5,960
19 Marathon Petroleum $5,374
20 Delta Air Lines $4,936
21 ConocoPhillips $4,907
22 General Motors $4,899
23 United Parcel Service $4,793
24 FedEx $4,647
25 Enterprise Products Partners $4,532
Top 25 Total $243,560
*Based on most recent fiscal year as of June 30, 3030
**Originally estimated based on 7/22/20 earnings report. 

Revised estimate based on 2020 10-K report

Data: Company financial reports, PPI estimates


Table 2. Non-energy U.S. Investment Heroes: Top 25 Nonfinancial Companies by Estimated U.S. Capital Expenditure
Rank COMPANY ESTIMATED 2019 U.S. CAPITAL EXPENDITURES (Millions USD)*
1 Amazon.com $19,306
2 AT&T $18,520
3 Alphabet $18,037
4 Verizon Communications $16,058
5 Intel $13,416
6 Facebook $12,457
7 Microsoft $11,073**
8 Comcast $10,467
9 Apple $9,772
10 Walmart $7,904
11 Charter Communications $7,195
12 Ford Motor $6,414
13 Delta Air Lines $4,936
14 General Motors $4,899
15 United Parcel Service $4,793
16 FedEx $4,647
17 United Continental Holdings $4,528
18 American Airlines Group $4,268
19 Walt Disney $4,024
20 CenturyLink $3,628
21 HCA Healthcare $3,537
22 Union Pacific $3,453
23 Kroger $3,128
24 Target $3,027
25 CVS Health $2,457
Top 25 Total $201,945**
*Based on most recent fiscal year as of June 30, 3030
**Originally estimated based on 7/22/20 earnings report. 

Revised estimate based on 2020 10-K report

Data: Company financial reports, PPI estimates


(Analysis by Elliott Long and Michael Mandel).

Credit Rating Agencies: Sending A Clear Signal

INTRODUCTION 

The Covid-19 pandemic has sent the global economy and financial markets into an unprecedented crisis. The path of the downturn and recovery is difficult to discern. Some companies and nations are likely to survive and prosper, while others will struggle indefinitely.

In this context, bond markets will be looking to rating agencies to objectively assess the changing prospects of bond issuers, both private and public. Even the Federal Reserve is counting on the rating agencies—the Fed’s own rules for which bonds it can purchase under the new Primary Market Corporate Credit Facility explicitly reference the ratings produced by major nationally recognized statistical rating organizations (“NRSRO”).1 

Can the credit rating agencies be trusted to do a good job analyzing the credit prospects of borrowers in the downturn? Will the resulting rating actions balance the needs of investors, issuers, and the financial markets? Will ratings downgrades unnecessarily make the economic and financial situation worse? 

Before the virus struck, two independent advisory committees at the SEC in the United States were in the process of examining the business and compensation models of credit rating agencies such as Moody’s Investors Service and S&P Global. The issue was whether their “issuer pays” business model gives them an incentive to inflate the initial ratings of corporate bonds and other securities, or an incentive to slow-walk necessary ratings downgrades in tough times. Several meetings were held at the SEC in 2019 and 2020 to discuss alternative compensation models that might not have the same conflicts of interest.

But despite these criticisms, the strengths of the current model of fixed income credit ratings— built around transparency and reputation—are often overlooked.

The market for ratings for fixed income securities has developed a set of incentives and institutions that consistently produce strong signals that are useful for market participants, even in uncertain times.

This paper examines the pluses and minuses of the “issuer pays” model of credit ratings. The current model helps solve two information problems simultaneously. First, it’s hard for financial intermediaries such as mutual funds and life insurance companies to assess all the different bonds that they might invest in. Second, it’s difficult for individuals who trust their money to these financial intermediaries to monitor the soundness of their portfolios. Well-understood ratings by an independent rater address both problems.

We compare the issuer-pays to alternative models, such as “investor pays” and government-sponsored ratings. We conclude that despite potential conflict of interest problems, the “issuer pays” produces a stronger and less biased signal for market participants. We look back at the 2008-2009 financial crisis and see that ratings were inversely correlated with 10-year default frequencies even in the disrupted residential mortgage-backed securities (RMB) and collateralized debt obligation (CDO) markets, just as they should be.

We also address the knotty question of “procyclicality”—whether the rating agencies are too lenient in good times and then compensate by being too tough when the credit market turns down. We look at the recent evidence and suggest that there’s no reason to believe that the alternative business models do a better job than the “issuer pays” model in generating useful information in downturns. 

We then set the business model and practices of the credit rating agencies in a broader context. In every part of the economy, the Information Age has made an exponentially increasing amount of data available to everyone. The difficult problem is extracting useful signals from the noise, especially when some market participants are actively taking advantage of opportunities to manipulate data, or to create false signals. 

The credit ratings market, based on the issuer pays model, seems to have a way to consistently produce high quality and more accurate ratings that give strong and useful signals to market participants. Another benefit of independent credit rating agencies is that they set a global language – a global standard of comparison. This is especially important at times of stress, like now, when credit facilities need to be set up quickly. 

Finally, we ask the important policy question of whether the “issuer pays” model provides any useful lessons for other areas of the economy struggling with extracting signal from noise, such as journalism and safety certification of new products. 

BACKGROUND 

Why do credit rating agencies exist? Whose interests do they serve? Bond issuers, from small companies to giants, sell a wide variety of fixed income securities. These are mostly bought by financial institutions such as banks, mutual funds, and insurance companies, who are functioning as financial intermediaries. For example, the 2019 financial accounts report from the Federal Reserve shows that out of the $14 trillion in corporate bonds, only $937 billion are held directly by U.S. households and nonprofits.2 That’s less than 7 percent. Households invest in corporate bonds indirectly, through financial intermediaries. They own shares in bond mutual funds, which in turn own corporate bonds. Or they have paid for life insurance, and the life insurance companies invest in turn in corporate bonds.

Here is a schematic diagram that shows the flow of money supporting the fixed income markets. The role of the credit rating agencies is to help solve not one but two information problems. First, financial intermediaries like mutual funds and life insurance companies want to have some way of assessing the riskiness of the bonds they are buying from the issuers.

Obviously they do their own analysis. But it’s also helpful to have an independent source of ratings, since the issuer has an incentive to minimize potential risks.

In theory, financial intermediaries could do without the ratings agencies, if they are willing to put enough money into analyzing every bond. However, fully shifting the bond riskiness assessment to the financial intermediaries wouldn’t solve and might even worsen the second information problem: The financial intermediaries buying the bonds have an incentive to understate the riskiness of their portfolio for households, other investors and regulators. Moreover, households and regulators generally do not have the resources to independently assess the riskiness of the portfolios of the financial intermediaries. Most households and retail investors, of course, are not direct users of credit ratings. But indirectly ratings provide guardrails for financial intermediaries such as life insurance companies, guiding which bonds they can invest in and reassuring buyers of life insurance policies that their money will be safe.

In effect, the ratings do double duty. They are used by the bond buyers to assess the riskiness of the bonds. In addition, they are used by households and regulators to assess the riskiness of the portfolios of the financial intermediaries as well. Any alternative to the current business model has to take into account both uses. (Figure 2).

HOW THE RATING PROCESS WORKS

Under the current model, the issuer of a bond pays the rating agency or agencies for the initial rating of a security, as well as ongoing ratings. Different rating agencies use different lettering schemes, but there is widespread agreement about what counts as investment grade bonds and what counts as speculative grade.

More precisely, the rating is an assessment that the bond can withstand a particular level of economic stress. For example, S&P lays out a chart that says that a AAA-rated bond can withstand a downturn on the level of the 1929 Great Depression.3

Unfortunately, no one, including the credit rating agencies, can forecast how deep the pandemic-related economic downturn can go.

As it heads into 1929 territory, it’s possible that some top-rated corporate bonds may default. Even under less stressful circumstances, the rating agencies cannot predict how the global economy or financial markets will perform.

Moreover, we can reasonably expect sectorspecific shocks that affect bonds in one sector differentially. For example, the current coronavirus crisis has the potential to cause significant downgrades of bonds issued by travel companies such as airlines and hotels. Meanwhile residential mortgage-backed bonds got hit hard during the 2008-09 financial crisis.

Given the unpredictability of the financial markets and the economy, the rating agencies can reasonably be expected to assess relative riskiness within a sector.

Table 2 is based on the performance summaries that the credit rating agencies are required to supply to the SEC annually. We looked at the tenyear period starting with 2006, the year before the financial crisis started, and focused on the performance of ratings issued for the RMB and CDO markets. These are two of the sectors that were disrupted the most in the 2008-09 financial crisis. We combined the data for Moody’s and S&P Global.4,5

We see that for these two important sectors, the rating on a security in 2006 is inversely correlated with the frequency of defaults 10 years later. The higher the initial rating, the lower the frequency of defaults.

THE FINANCIAL CRISIS OF 2008-09

Under the current model, the issuer of a bond pays the rating agency or agencies for the initial rating of a security, as well as ongoing ratings. Different rating agencies use different lettering schemes, but there is widespread agreement about what counts as investment grade bonds and what counts as speculative grade.6

In response, the Dodd-Frank Act of 2010 called for the SEC to study alternatives to the “issuer pays” business model, as well as other regulatory reforms. In addition, the Department of Justice, in combination with some state attorneys general, launched lawsuits accusing S&P and Moody’s, in particular, of defrauding investors.

The lawsuit against S&P was settled in 2015, focusing on a small number of incidents where internal procedures weren’t followed.7 A similar lawsuit against Moody’s was settled in 2017, with the rating agency agreeing to do a better job following its published rating procedures.8 In neither case was there sufficient evidence for a finding of fraud.

POTENTIAL BIAS

The obvious bias in the issuer pays model is that the ratings agencies compete to offer issuers better ratings. To put it another way, an issuer can engage in “ratings shopping” by choosing to pay the agency that offers the higher rating.

But study after study has shown much less evidence of rating shopping than one might expect. Most bond buyers only want to invest in securities that are rated by multiple agencies. That means rating agencies are under less pressure to boost ratings.

It is true that among single-rated securities or tranches, there is evidence that bond issuers are choosing the agency that offers the higher rating, as one might expect. One study found that for mortgage backed securities, “outside of AAA, realized losses were much higher on single-rated tranches than on those with multiple ratings, and yields predict future losses for single-rated tranches but not for multi-rated ones.”9

However, it turns out that bond buyers are not stupid. When they see a single-rated security, they are less likely to trust the rating than if it has been rated by multiple rating agencies. One 2019 study found that “bonds with upwardbiased ratings are more likely to be downgraded and default, but investors account for this bias and demand higher yields when buying these bonds.”10

In other words, the combination of the rating and the number of raters—both publicly observable pieces of data—produces useful information for participants in the bond market. In other words, the bias is partly self-correcting.

MITIGATING THE BIAS

Still, it is clear that credit rating agencies face conflicts of interests, much like other participants in financial markets. Accounting auditors face pressure to give good grades to their clients. Investment banks face pressure to overstate the potential of the initial public offerings that they help bring to market. And even regulators face conflicts of interest, since a typical career path often leads out of government to the regulated industry.

Like these other institutions, internal controls at the rating agencies can help mitigate the bias towards higher ratings. That includes internal separation of sales and analysis, so that the people assigning a rating to a bond are not in direct contact with the issuer of the bond. In addition to internal controls, credit rating agencies are heavily regulated around the world. That includes annual exams in the U.S. by a regulator who has significant authority to take action if any violations occur—including revoking a credit rating agency’s license to operate.

Even with these internal controls, though, the real mitigating institutions are transparency and reputation.

Transparency

The agencies assess the creditworthiness of the bonds according to published and detailed methodologies.11 In fact, there is literally nowhere else in the private sector that gives this level of transparency into the intellectual property of an organization, or that so rigorously documents their internal methodology for making decisions (imagine a newspaper committing itself publicly for how it chooses stories or does reporting, including reporting on advertisers). From the perspective of users of the ratings, the public nature of the ratings methodologies is essential. On transparency, one of the key benefits of an issuer-pays system is the fact that allows ratings to be released publicly – meaning they’re scrutinized every day by all corners of the market, the media, and academia. The ratings agencies cannot be judged on the performance of the ratings they issue, because of the uncertain effects of future events. But they can be judged on whether they follow their published methodologies.

Reputation

The other institution that mitigates bias is the need to preserve reputation. Credit rating agencies know that credit booms always end in a recession or credit crisis. The exact nature of the crisis can’t be predicted—the concept of a global pandemic, even if acknowledged within the realm of possibility, was part of very few reasonable scenarios. But when the crisis comes, credit rating agencies can be sure that their rating decisions will be challenged ex poste.

Their initial rating decisions will be criticized for being excessively sanguine. Their ratings downgrades will be attacked for either being too slow (leading to investors being misled) or too rapid (potentially undermining the economic viability of a bond issuer). All of their internal decision-making processes will be scrutinized and investigated.

This sort of intense scrutiny is only reasonable. Rating agencies do all of their work out in the open. They issue public ratings, and the performance of the ratings is visible as well. It’s not possible to investigate all of the bond issuers, so the ratings agencies are a proxy. They are an easy target, and that’s a good thing.

One can think of this as a long-term equilibrium where the rating agencies make good profits during the boom periods assigning ratings.

During the downturn it’s revealed how well their ratings performed. In addition, after the inevitable investigations, the rating agencies can expect that their internal rating process will be revealed as well. They therefore have a strong incentive not to cut corners and preserve their reputation so that they can survive the investigations of the downturns.

Indeed, issuers will not use the ratings if investors don’t trust in their independence and the strength of the models. In fact, demand for the use of certain credit rating agencies comes from the performance of their ratings over time and the ongoing judgment of investors.

ALTERNATIVE COMPENSATION MODELS

Is there a better way? Dodd-Frank charged the SEC with examining alternative business models for ratings agencies, since issuer pays has an obvious conflict of interest. Meeting in late 2019 and early 2020, the SEC’s Fixed Income Market Structure Advisory Committee looked at the question, in the words of SEC Chairman Jay Clayton: “Are there alternative payment models that would better align the interests of rating agencies with investors?”12

Economists, regulators, and financial market participants have suggested a variety of alternative compensation models designed to reduce conflicts of interest while still maintaining the critical function of the ratings agencies. A 2012 report from the GAO identified seven possibilities, though several had never been tried in the real world. At the end of the day, the only plausible alternatives are some form of “investor pays” and random assignment.

Investor Pays

One option is to require the investor to pay for ratings, like a subscriber fee. More precisely, it’s better to say that “financial intermediaries pay” since financial intermediaries such as mutual funds, pensions, and life insurance companies own the majority of fixed income securities.

The shift to “financial intermediaries pay” removes one conflict of interest, at the cost of creating two more. On the one hand, at the time of issue, it’s better for the bond buyer if the rating is cautious, so that the bond will be priced lower and pays a higher yield. On the other hand, financial intermediaries prefer that the rating agencies are slow to downgrade, to make their portfolios look better to final investors and regulators.

It’s also true that there are fewer financial intermediaries than bond issuers. Moreover, financial intermediaries tend to have the resources to do their own analysis if needed. They are therefore less dependent on the rating agencies, and have less need for the information.

In the end, there is no compelling case that the “investor pays” model is superior to the “issuer pays” model. Moreover, it’s hard to see how an “investor pays” model would work without strict government rules.

Random assignment

The critics who worry about issuers shopping for ratings keep coming back to the same solution: Random assignment of rating agencies to new bond offerings. When an issuer wanted to have a bond rated, they would apply to a central organization that would randomly assign a credit rating agency off of a list of approved agencies. The agency would then get paid for its work at a fixed rate.

In effect, the “random assignment” compensation model turns credit ratings into a government-run utility using “fixed price” contractors. As with all government-run utilities, there would be pluses and minuses.

On the one hand, random assignment reduces or eliminates the ability of issuers to shop for better ratings, which is the intention. That means rating agencies would not have an incentive to artificially boost ratings.

But as in the case of “investor pays,” eliminating one problem creates two new problems. First, under the random assignment compensation model, rating agencies have no incentive to put effort into producing high quality ratings, since they get picked randomly even if they do just an average job. Credit rating agencies would be investing the money in innovation. As a result, the random assignment approach may produce ratings that are less biased but also less accurate. Moreover, there might be an incentive to set ratings artificially low to avoid downgrades.

The second and related problem is deciding which rating agencies are on the approved rotation list—which ones are eligible, and which ones need to be removed for bad performance. That requires a government “gatekeeper” to assess the short-term and long-term performance of each agency and which ones are “good enough” to be on the list.

There are two approaches to assessing performance of rating agencies. One is to look at measurable outcomes—for example, the frequency of defaults and large downgrades. These must be measured over an entire credit cycle, so it’s tough to see how they can be applied in the short run. Moreover, any “objective” measure will be gamed by new rating agencies that want to get on the list.

The other approach is to set up a standard that is based on minimum capabilities. That is, the government gatekeeper would add to the list any rating agency that has enough licensed analysts and published methodologies. The result is that more competition is likely to lead to worse quality ratings.

There’s one final important point. One of the biggest and most politically fraught rating decisions is how to assess sovereign debt, and in particular the debt offerings of the U.S. government. With the government as the gatekeeper for the random assignment list, there’s likely to be pressure on rating agencies not to downgrade government debt even if appropriate. The conclusion is that the shift to a random assignment system is likely to produce new unknown biases in ratings.

PROCYCLICALITY

One charge levelled against the current “issuer pays” model is that it leads to “procyclicality.” If ratings were procyclical, that would mean that the rating agencies go too easy on issuers in good times, and then are forced to be tough and downgrade bonds in bad times. In this way, say the critics, ratings procyclicality can end up making the booms bigger and the downturns worse.

However, the evidence for ratings procyclicality is, to put it mildly, mixed. A July 2020 report from the SEC observed that “ratings downgrades are generally lagging indicators of cost of debt capital. Moreover, consider the issue of whether rating agencies have been giving “too high” ratings to corporate borrowers in recent years. In a February 2020 report, the OECD directly addressed that question, comparing the pattern of ratings by one credit rating agency in 2017 with 2007. The report found that at the same rating level, borrowers in 2017 had a higher level of debt relative to various measures of cash flow and earnings.

By itself, that result suggests that credit rate standards had gotten easier in 2017 compared to 2007. However, the report then admits that low interest rates made it easier for corporate borrowers to cover their debt payments in 2017 compared to 2007, providing evidence that credit standards had not gotten easier.

In truth, the procyclicality argument is a bit of a red herring. When the credit cycle turns down, credit rating agencies are stuck no matter what they do. If they are conservative and cautious about downgrading bonds, they are accused of protecting their issuers. If they downgrade aggressively, they are accused of making the recession worse. The cries are especially loud when sovereign debt issued by governments is downgraded, since such a move has a broad effect on the ability of governments to raise money.

Moreover, there’s no evidence that the alternative compensation models would do any better. Under the “investor pays” model, the rating agencies will come under strong pressure from investors to not downgrade the bonds in their portfolios in downturns, making ratings untrustworthy at precisely the moment they are needed the most. And as we point out in the previous section, under the “random assignment” model, any rating agency that downgraded the government might find itself out of the rotation in the future.

OTHER APPLICATIONS OF ISSUER PAYS

For all their flaws, independent credit ratings agencies, paid by issuers, produce a strong and useful signal in a noisy information environment. It isn’t perfect, but the ratings perform well, and users are able to adjust for potential conflicts of interest. The combination of transparency and reputation seem to create sufficient incentives to make it worthwhile for the credit rating agencies to take their job seriously and produce information that issuers, financial intermediaries, and households and regulators can’t do without.

In the broader sense, one gets a sense that the current “issuer pays” credit rating system is actually a pretty decent way of solving a difficult problem that occurs across the economy—certifying the quality of products and services. An independent third party is paid by the producer or manufacturer of the product or service to do the certification (“issuer pays”). One key is that the payment has to be large enough that the certifying organization has an incentive to maintain their reputation.

Certification of electric equipment

Indeed, the “issuer pays” model turns out to be applicable to other areas of the economy where information is important. For example, certification of electrical equipment and other products for safety is an area that is increasingly important these days. The top U.S. “certification agency” is UL LLC, an organization founded in 1894 as the Underwriters’ Electrical Bureau, and operated until 2012 as the non-profit Underwriters Laboratory.13

UL’s business model is to charge companies with new products to get certification for meeting safety standards, typically promulgated by Underwriters Laboratory, in order to get the UL certification. There are other certification organizations in the United States, such as Intertek Testing Services NA, Inc., based in Illinois. But UL is the leader.

For many products, there’s no legal requirement to have a UL certification, but many larger retailers won’t sell the product without. Certification for products used in the workplace is mandated by OSHA, which publishes a list of approved testing laboratories.14 In addition, the government sometimes mandates that particular products cannot be sold in the United States without UL certification. That was true in 2016 for hover boards, for example, when the CPSC banned any hover board that didn’t have a UL certification.15

As with credit rating agencies, issues regularly arise about the objectivity of UL certification.16 Moreover, as UL has extended its work to certify a wider variety of products, questions have arisen about its capabilities. Nevertheless, the “issuer pays” model in product safety certification seems to be functioning well.

Indeed, the European Union, which on the surface uses a “self-certification” model, seems to be heading towards “issuer pays.” The selfcertification model uses the CE mark, which means that the manufacturer or retailer is taking responsibility that the product meets EU standards.17 But in many product areas the company must also get the approval of what’s known as a “notified body,” which is the equivalent of a certifying authority.18

Unfortunately, the European system has been criticized for being too lax.19 Gradually they have been moving closer to a pure “issuer pays” model, with more products requiring certification by notified bodies.

Rating of journalist organizations

One area where third-party rating is just getting started is the news business. Companies such as Facebook and Twitter have been criticized for allowing too much ”fake news” on their platform—low quality news sources that spread misinformation. On the other hand, if they start exercising too much control, they are accused of censorship and monopoly power.

The obvious solution is for the platforms to use an independent third party. Indeed, we’ve started to see a rise of for-profit companies that rate the reliability of news sources. The leading one so far is NewsGuard Technologies, founded in 2018 by Steven Brill and Gordon Crovitz, formerly publisher of the Wall Street Journal. NewsGuard ranks news sources on nine different criteria, such as “avoids deceptive headlines” and “does not repeatedly publish false content.” 20

The demand for journalistic ratings comes in part from the threat of government regulation. European countries, in particular, have passed laws to control “fake news.”21 Companies such as Facebook, Google, Microsoft, Mozilla, and Twitter have signed onto the European Commission’s voluntary Code of Practice on Disinformation, which commits them to take certain steps to control fake news.22

So far, the NewsGuard business model is “user pays.” As the company says, “NewsGuard’s revenue comes from Internet Service Providers, browsers, search engines and social platforms paying to use NewsGuard’s ratings.” For example, Microsoft is paying a licensing fee to NewsGuard to incorporate the ratings into Microsoft’s Edge browser.23 In addition, individuals can subscribe to the service for a small monthly fee. It’s not clear how many other platforms are paying, especially since the ratings are publicly available.

Over time, platforms may gravitate towards only featuring news sources that get satisfactory grades from at least two independent raters. That opens the possibility of an “issuer pays” model where news sites pay a fee to get rated, perhaps proportional to their web traffic. This has the advantage that the ratings are public and available to everyone.

CONCLUSION

Since the 2008-2009 financial crisis, critics have worried about the biases built into the “issuer pays” compensation model for credit ratings agencies. Now that the Covid-19 crisis has placed the credit markets under great stress, these questions are once again coming to the fore. But as we show in this report, nobody has been able to come up an alternative compensation model that is clearly better. There’s no reason to believe that the issuer pays compensation model will get in the way of the necessary effective and independent third party assessment of default probabilities under extreme uncertainty.

Indeed, in the Information Age, the “issuer pays” approach for credit ratings may serve as a good model for other parts of the economy, because it generates a clear signal. We identified another sector, product certification, where “issuer pays” is the dominant model despite its inherent biases. We also consider whether the “issuer pays” model could be applied to certify the quality of journalist organizations, an exceptionally important problem that has been difficult to solve.
To Open or Not To Open: Educational Equity Under COVID

The Reinventing America’s Schools Project sponsored an engaging discussion entitled “To Open or Not To Open: Educational Equity Under COVID.”

Over 4,000 parents, educators, advocates, funders, journalists, and policy makers registered to hear from experts in teaching, parental engagement, system leadership and health on how to equitably reopen schools in the fall.

Our moderator and panel discussed the health, policy, and budgetary factors school systems should consider before making a decision grounded in educational equity for all students.

The Reinventing America’s Schools Project was glad to sponsor such an important conversation at this time. Thanks to Alma Vivian Marquez, George Parker, Paul Vallas, and Dr. Leana Wen for joining our Deputy Director Curtis Valentine!

Watch here.

Opinion: Bridgeport schools must do more to prepare for fall

Bridgeport Public School students were in trouble before the pandemic shuttered schools in March. Each year, BPS students take the “Smarter Balance” state tests. On the 2019 test, not a single BPS school recorded 50 percent of its students meeting or exceeding expectations for their grade level in reading, with the exception of two select enrollment magnet schools.

At seven BPS schools, fewer than 20 percent of students scored at grade level in reading, with just 10 percent of students proficient at Cesar Batalla School, and just 9.5 percent meeting or exceeding expectations at Luis Munoz Marin Elementary. Scores in math were no better — in many cases, they were worse.

What does this look like when we turn the statistics into living, breathing children? Well, from those seven BPS schools with fewer than 20 percent of students scoring at grade level, the state counted a total of 3,466 student test scores. Of those 3,466 kids, only 444 of them had learned what they should have by that point in their schooling. The vast majority, 3,022 kids, are behind, and had not learned what they need to succeed at more challenging coursework in the next grade.

This spring, the pandemic closed BPS before students could take the state test, to see if they had done any catching up since the previous year. Since 1906, researchers have been studying the “summer slide,” or, the amount of learning students lose over summer when schools are closed. One of the biggest studies in recent times showed that students can forget as much as 25 to 30 percent of what they learned the previous year over the roughly 10 weeks of summer vacation. This year, if schools really do open as scheduled, BPS students will have been out of the classroom for 24 weeks — a solid six months.

In a normal year, there would be no reason to expect the massive numbers of BPS students who are behind would do better in the following grade without some kind of intervention, like tutoring, remedial work in summer school, and so on. In this very abnormal year, with its huge gap in continuous learning, BPS has a heightened responsibility to marshal every available resource to reach its already-behind students and ensure they do everything humanly possible to give them the attention and instruction to which they are entitled.

Read the full piece here.