How Ecommerce Creates Jobs for American Workers and Saves Time for American Families

This past weekend a Wall Street Journal piece quoted me on ecommerce jobs:

One economist who has looked at these trends has concluded something surprising: When you include all the jobs in fulfillment, delivery, and related roles, e-commerce has created more jobs between 2007 and January 2020 than bricks-and-mortar retailers lost, says Michael Mandel, chief economic strategist at the Progressive Policy Institute, a think tank. Since January, employment in this sector has fallen, but Dr. Mandel believes that as consumer spending recovers, so will employment in this area.

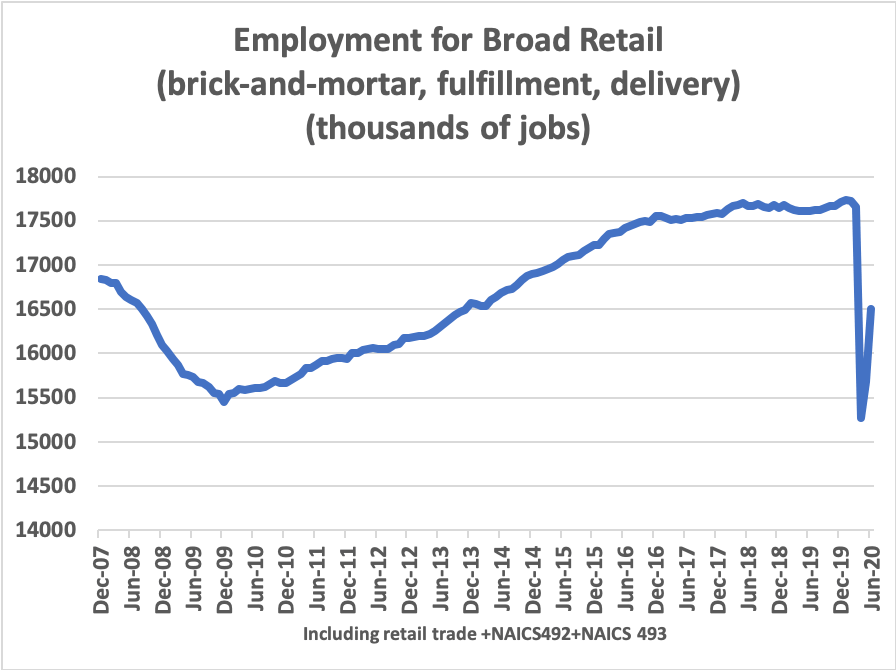
I thought I would give some of the statistical backup. I calculated total jobs in brick-and-mortar plus ecommerce by adding retail trade, couriers and messengers (NAICS 492)(local delivery) and warehousing and storage (NAICS 493)(ecommerce fulfillment).  This total was still rising in early 2020, before the pandemic hit, with the peak coming in January 2020.

Between December 2007, the previous business cycle peak, and January 2020, ecommerce industries created 900K more jobs than were lost in brick-and-mortar retail. We can see the total in this chart.

Total jobs went up because unpaid hours that Americans used to spend driving to the mall, parking, wandering through stores, waiting on line to pay, and driving home are now being transferred to the paid sector.

How many hours are being saved? Each year the BLS does a survey called the American Time Use Survey. It shows that average consumer shopping hours per person, excluding groceries and gasoline,  fell by 27%, from roughly 144 hours per year in 2007 to roughly 105 hours per year in 2018. Presumably this decline was driven by ecommerce.


The implication: Summed over the whole U.S. population, ecommerce saved American families 10 billion hours per year in 2018. 

The conclusion: More jobs for American workers, more time for American families.

Release: In Gig Economy Space, New Report Shines Light on Regulatory Improvements for Independent Workers

Independent workers face a dilemma where they cannot currently receive benefit payments from companies without risking their independent status.

WASHINGTON, D.C. – A new report from the Progressive Policy Institute examines the possibility of creating a way to regulate platforms that would preserve the flexible nature of independent workers and the benefits to our economy at large while continuing to protect both workers and consumers. The flexibility of platforms will play a critical role in helping the U.S. labor market recover more quickly from the COVID recession.

The new report finds that companies that do business with independent workers can’t provide benefits because that would turn them into employees, an outcome that the overwhelming majority of these workers do not want. But independent workers providing benefits for themselves incur a much bigger tax burden than they would face as an employee.

Key findings from the report include:

  • According to a recent report from Edelman Research & Upwork, 51% of respondents said there is no amount of money where they would definitely take a traditional job; 
  • During recessions, unemployment insurance benefits received swell far out of proportion to taxes paid in, as the federal government typically appropriates more money to beef up unemployment insurance;
  • One estimate from the Berkeley Research Group concluded that switching the status of app-based drivers to full-time employees would reduce the number of drivers by 80 to 90 percent in California.

The new report identifies four prongs in which there is a ‘better way’ to revamp the current system tax treatment for independent workers: straighten out the current tax code, simplify the dividing line, apply a baseline level of benefits, and implement a cafeteria style plan.  

Straightening out the current tax code would require independent workers to deduct healthcare and retirement contributions from the earnings calculation for the self-employment tax. In order to simplify the dividing line, an independent worker would have to reach a certain number of hours contracting with a particular company or platform, then the worker would be entitled to a required set of tax-advantaged benefits.

To apply a baseline level of benefits, companies would be able to offer benefits to independent contractors without worrying that they would be reclassified as employees at either the state or federal level. The cafeteria plan would allow independent workers to choose from a variety of pre-tax benefits, including health insurance, paid time off, and retirement savings.

Policy recommendations include:

  • Construct a new regulatory framework that explicitly recognizes a middle ground of independent workers who can receive benefits from the (multiple) companies they contract with;
  • Straighten out the tax treatment of benefits so that independent workers are on a level playing field with employees;
  • Require a baseline level of benefits and protections for independent workers, including a cafeteria style plan;
  • Install a uniform national standard for determining who is an independent worker.

“A separate and important question is whether the new regulatory regime would be opt-in or mandatory,” said author Michael Mandel, the chief economic strategist at PPI. “If companies do not opt in, they would remain subject to existing legal tests for determining worker classification.”

View the report by clicking here.

Regulatory Improvement for Independent Workers: A New Vision

One of the biggest productivity advances in recent years has been the use of platforms to connect buyers and sellers at lower cost. Platforms offer less rigid contractual arrangements, expanded earnings opportunities for workers and access to essential goods and services for underserved communities. Overall, platforms generate win-win economic activity which benefits everyone. 

The flexibility of platforms will play a critical role in helping the U.S. labor market recover more quickly from the Covid recession. In most economic recoveries, companies have been apprehensive about making the commitment to hire given lingering economic uncertainty. That has typically made employment a lagging indicator in recoveries. By contrast, platforms will make it easier for workers to scale up hours worked gradually as the economy expands, which will boost consumer spending and demand, which will in turn boost employment. 

The big question, though, is how to regulate platforms in a way that preserves the flexible nature of the work and the benefits to our economy at large, while continuing to protect both workers and consumers. The Progressive Policy Institute believes strongly in the importance of regulation for a well-functioning market economy. Yet we have long advocated for “regulatory improvement” as essential for accelerating growth and job creation.

Regulatory improvement is very different from deregulation. Too many sectors of the economy have overlapping and contradictory layers of regulation that get in the way of productivity gains and rising incomes. At the same time, there may be parts of the economy where new rules are necessary. In this case, platform businesses need to step up and provide a baseline level of benefits to their workers.

The labor market, in particular, is struggling with a 20th century regulatory framework imposed on a 21st century economic structure. The first 1099 was issued in 1918 and the first W-2 in 1944. To this day the labor market is artificially divided into “employees” and “independent workers”, including freelancers, sole proprietors and other self-employed workers. The dividing line is quite complicated and, in some cases, almost impossible to understand, with different federal and state agencies following different rules for establishing the dividing line. This patchwork of conflicting regulations creates enormous business uncertainty, reducing the incentive to create new work opportunities.

In the current regulatory framework, workers classified as “employees” are subject to a completely different regulatory regime than independent workers, including rules for scheduling and hours worked, working conditions, minimum wages and who pays Social Security and Medicare taxes. Employees are subject to employers’ control in every aspect of how they do the job, which for many low-income workers means shift work tied to a single company, which sets the exact hours. Employees typically get certain benefits, such as workers compensation and unemployment insurance, which are generally paid for by payroll taxes, and possibly access to other benefits, such as group life insurance, defined contribution retirement plans, and employer-sponsored health insurance or health savings accounts (HSAs).

Independent workers have a unique flexibility that employees do not enjoy at all. In the same survey, 51% of respondents said there is no amount of money where they would definitely take a traditional job. Part of the explanation may be that independent contractors simply aren’t able to work under the terms of normal employment; in fact, 46% say they could not have a traditional job due to personal circumstances (e.g., health or caregiving duties).

But in exchange, independent workers, almost by definition, are not allowed to get benefits from the companies that they do business with. As an IRS publication states:

Businesses providing employee-type benefits, such as insurance, a pension plan, vacation pay or sick pay have employees. Businesses generally do not grant these benefits to independent contractors.

Unfortunately, the current tax system systematically penalizes independent workers who try to provide their own benefits and companies that want to help these workers maintain flexibility while accruing appropriate benefits or protections. For example, as we explain below, most independent workers have to pay FICA taxes on the money they contribute to their tax-deferred Individual Retirement Accounts (IRA), Simplified Employee Pensions (SEP) or solo 401k accounts. By comparison, the contribution of employers to employee retirement accounts is exempt from both employer and employee FICA taxes. This saving can be worth thousands of dollars. The same or similar problems show up with other benefits as well. 

This puts independent workers into a catch-22 situation. The companies that they do business with can’t provide benefits because that would turn them into employees, an outcome that the overwhelming majority of these workers do not want. But independent workers providing benefits for themselves incur a much bigger tax burden than they would face as an employee. 

There are two solutions to this problem for independent workers. One is to double down on the historical dichotomy between employees and independent workers and make the distinction even more rigid. This “Procrustean Bed” solution is best exemplified by which imposes rigid tests on who can be classified as an independent contractor. Basically, it forces companies to turn many of their independent contractors into employees, which would lead to the loss of these workers’ flexibility and control over their hours and who they can work for. In the gig economy space, this would almost certainly mean set schedules and the inability to work on more than one platform. Minimum wage rules and other employment regulations would lead to reduced service at certain times of day or in certain geographical areas.

The other alternative is to improve the position of independent workers by creating a new regulatory regime that extends them important new benefits, while still allowing the flexibility that self-employed workers choose. 

This new regulatory regime would have several important features. 

  • It would straighten out the tax treatment of benefits so that independent workers are on a level playing field with employees.
  • It would require a baseline level of benefits and protections for independent workers, including a cafeteria style plan with a menu of options for workers to choose what makes the most sense for them.
  • It would have a uniform national standard for determining who is an independent worker. One possibility is that companies would have no control over hours of work, and no non-compete agreements. 

A separate and important question is whether the new regulatory regime would be opt-in or mandatory. We lean towards opt-in, as discussed below.

The Structure of Benefits 

What benefits are U.S. employers actually paying to their employees? Table 1 below summarizes the distribution of benefits for full-time and part-time workers for the 2018-2019 period, based on BLS data. Note that part-time workers get a significantly small share of their compensation in benefits compared to full-time workers. Moreover, almost half of the benefit “package” for part-time employees comes through the legally mandated “benefits” such as employer tax payments for Social Security and Medicare, much of which independent workers already pay on their own. 

In general there are two problems with independent workers providing their own benefits. First, as we will see, the tax laws are written in such a way as to be biased against independent workers compared to employees, especially when the independent workers file on Schedule C. Second, if the businesses hiring the independent workers try to provide benefits, that’s taken as prima facie evidence that the independent workers are really employees, which the overwhelming majority of self-employed workers typically do not desire to be. 

Example 1: Retirement Savings

We already mentioned that the current tax system systematically penalizes independent workers who try to provide their own benefits. Let’s begin with retirement. Suppose that an employer wants to contribute $1000 to an employee retirement plan such as a 401k. That employer contribution is deductible from the employer’s business income and does not incur Social Security or Medicare Taxes for either the employer or the employee, as long as certain rules are met. 

Now suppose a company gives that $1000 to an independent worker who is filing as a Schedule C sole proprietor or single-person LLC. They deposit the $1000 in their IRA, SEP, or solo 401k account as a tax-deferred retirement contribution. The independent worker gets to deduct this contribution from their federal income tax (line 15 or line 19 on schedule 1). 

However, the independent worker has to pay both the employee and employer FICA tax, minus the net impact of the deductibility of the employer share (Schedule SE and line 14 on schedule

1). So, for example, if the independent worker’s marginal federal income tax rate is 22%, they end up paying a bit under 13% on the $1000, rather than 0%.

In other words, the independent worker is penalized on the retirement savings side. And the company can’t offer to bring the independent worker into the company’s plan without classifying the worker as an employee. 

Example 2: Healthcare Benefits

 A similar disparity holds in the case of healthcare benefits. If an employer contributes $1000 to a health insurance plan for their employee, that contribution is deductible from the employer’s business income and exempt from both employer and employee FICA taxes (within limits). And the contribution does not count towards the employee’s taxable income. 

That same $1000, paid directly to the independent worker, can also be used to finance health insurance. In many circumstances, that spending on self-employed health insurance can be deducted from taxable income (Line 16 on schedule 1). However, the independent worker still must pay employer and employee FICA taxes on that $1000, minus the deductibility of the employer share. As before, if the independent worker’s marginal federal income tax rate is 22%, they end up paying just under 13% on the $1000, rather than 0%. 

Example 3: Workers’ Compensation

Workers compensation is basically an insurance policy that covers employees for on-the-job accidents or injuries. Workers comp benefits are typically not taxable, and workers comp premiums are deductible from business income. Depending on the particular state, independent workers with no employees are usually not required to purchase workers’ comp for themselves. Such individual policies can be quite expensive, so many independent workers go without. But going without workers comp or occupational accident insurance, runs the risk of being exposed to large medical bills and a significant loss of income if workers are injured on the job. On the other hand, if the company provides worker compensation to an independent worker, that runs the risk of having them reclassified as an employee, which is not the outcome self-employed workers want. 

Example 4: Unemployment Insurance 

Under ordinary circumstances, the U.S. unemployment insurance system is a fairly small part of benefits. Depending on the year, average state and federal premiums for unemployment in the private sector amounts to between 0.5% and 0.9% of compensation. In 2018—a low-unemployment year–that came to only about $40 billion, on an annual basis. By contrast, unemployment benefits received in 2018 came to only $27 billion. Unemployment insurance premiums are deductible from business income, while unemployment benefits are subject to income taxes but not to FICA taxes. 

On the other hand, during recessions, unemployment insurance benefits received swell far out of proportion to taxes paid in, as the federal government typically appropriates more money to beef up unemployment insurance. In 2009 and 2010, for example, unemployment benefits rose to over $130 billion annually. Because of these special payments, unemployment benefits paid out over this last business cycle (2008-2019) exceeded unemployment insurance taxes paid in by more than $100 billion, none of which went to independent workers. 

However, the discussion around unemployment insurance for independent workers is different now than it would have been even six months ago. The Pandemic Unemployment Assistance (PUA) covered self-employed workers and small businesses, and showed that it was possible to provide “income insurance” for independent workers in hard times outside of the conventional unemployment insurance structure. 

So let’s focus for now on how to provide “income insurance” for independent workers in normal, non-recession circumstances. The key is that independent workers need a cushion not just against economic shocks, but personal shocks such as illness or family needs. One solution is for employers to contribute to a pot of money for the independent worker that could be used for a variety of different purposes. Like unemployment insurance premiums, the contributions to the fund should be tax-deductible.

One variant of income insurance that could apply to independent workers is income averaging for tax purposes. Because of the progressivity of the income tax code, allowing independent workers and employees to average between good years and bad years could significantly reduce the average tax bill, and cushion the effects of fluctuations. Income averaging was available to taxpayers whose income spiked up until 1986, when it was eliminated by that year’s tax reform (it is still available to farmers and fishermen). 

The Wrong Approach

The key goal is to make independent workers better off. One potential solution, as noted in the introduction, is to double down on the historical dichotomy between independent workers and employees. California, which went into effect on January 1, 2020, is the exemplar of this approach. This codifies and expands the “ABC test” which says that a worker is an employee unless they meet all of the following conditions: (A) “the individual is free from direction and control,” applicable both “under his contract for the performance of service and in fact,” (B) “the service is performed outside the usual course of business of the employer,” and (C) the “individual is customarily engaged in an independently established trade, occupation, profession, or business of the same nature as that involved in the service performed.”

Under this extremely stringent test, some independent workers would need to be reclassified as employees. This reclassification is incompatible with business models predicated on independent workers, and as a result, many businesses have cut ties with California-based workers or shut down operations in California entirely. Under the new classification, it’s not illegal per se to allow an employee to completely decide which work opportunities to accept and to set his or her own days and hours (without any intervention from the business), but it’s certainly doesn’t fit the way employers typically operate.

As a response to this new law, California independent workers have been laid off en masse. In its news coverage of the passage of AB-5, Vox published an article with the headline “Gig workers’ win in California is a victory for workers everywhere.” Its reaction as a business, however, was quite different. A couple months later, the parent company Vox Media laid off 200 freelance writers right before the holidays (and right before the law went into effect on January 1). Deliv, a Menlo Park-based crowdsourced, crowd-shipping, same-day delivery startup, severed its relationship with 591 drivers a few months after it went into effect. 7-Eleven halted new California franchises. One estimate from the Berkeley Research Group concluded that switching the status of app-based drivers to full-time employees would reduce the number of drivers by 80 to 90 percent in California.

A Better Way

An alternative is to construct a new regulatory framework that explicitly recognizes a middle ground of independent workers who can receive benefits from the (multiple) companies they contract with. 

As we noted above, would have to address three main issues. 

  • It would straighten out the tax treatment of benefits so that independent workers are on a level playing field with employees.
  • It would require a baseline level of benefits and protections for independent workers, including a cafeteria style plan.
  • It would have a uniform national standard for determining who is an independent worker. One possibility is that companies would have no control over hours of work, and no non-compete agreements. 

A separate and important question is whether the new regulatory regime would be opt-in or mandatory. We lean towards opt-in given the wide variety of independent contractor arrangements that exist (e.g., doctors, realtors, etc.). If companies do not opt in, they would remain subject to existing legal tests for determining worker classification. 

Note that our proposal is very different from the “marketplace contractor” laws passed in states such as Florida. Such laws merely specify that certain on-demand workers are to be treated as independent contractors. However, they do not fix the federal tax laws that unfairly penalize benefits for independent workers. They also do not specify baseline levels of benefits and protections. 

Straightening out the tax code

As documented in this paper, the current tax treatment of benefits systematically favors employees over independent workers. Sole proprietors and single-member LLCs that file via Schedule C pay a substantial tax penalty for attempting to access the same benefits employees get. That needs to be fixed. For example, when a self-employed worker contributes to an SEP, that contribution should be exempt from payroll taxes. The tax fix here would be a simple one, allowing independent workers to deduct healthcare and retirement contributions from the earnings calculation for the self-employment tax. 

The companies need to step up here, too. A company should be able to contribute to an independent worker’s retirement or health accounts without triggering additional tax consequences, just as would happen for an employee. This would require a modification to current law governing benefits.

Simplifying the dividing line

The dividing line between independent workers and employees should include whether the company contributes to benefits for the independent worker. To the contrary, in this new category, once a worker reached a certain number of hours contracting with a particular company or platform, the worker would be entitled to a required set of tax-advantaged benefits —for example, portable benefits including paid leave, retirement savings accounts and contributions towards an individual’s health insurance premiums. All workers should be covered by occupational accident insurance for on-the-job injuries. On the other hand, companies would be forced to allow workers in this third category the freedom to choose their hours as well as work for other companies in the same industry. In other words, control over hours or non-compete agreements. 

Baseline level of benefits

The exact level of benefits required in the new category would have to be considered carefully. The optimal mix of benefits will create an option that is preferable to current rules for many companies and workers, creating a win-win proposition. The flexibility, in particular, will be attractive to many workers.

We note that it’s especially important to design the benefits package to help low wage workers. For example, one could imagine zero-cost banking as part of the package in order to link the unbanked to the financial system. These zero-cost bank accounts would be designed to be portable and would be subsidized by the companies with which the worker contracts. 

Companies would be required to choose, on a year by year basis, whether they treat their independent contractors under this new category. This choice would allow companies to offer benefits to independent contractors without worrying that they would be reclassified as employees at either the state or federal level, while preserving the flexibility and independence that are synonymous with independent contractor status. And independent contractors would be on a level playing field with the tax-advantaged employee benefits.

How the cafeteria style plan would work

The cafeteria plan would allow independent workers to choose from a variety of pre-tax benefits, including health insurance, paid time off, and retirement savings. These benefits would be tied to the individual, not the job, making them truly portable. Plans would be managed by a qualified benefits provider. If an independent contractor ceases work for one company, they do not lose any accrued benefits from that relationship. Companies pay the equivalent of a certain share of the worker’s earnings into a dedicated account for pre-tax benefits. There is no required match from the beneficiary – the cost is fully borne by the business and nothing comes out of workers’ pockets. The independent contractor accrues benefits in proportion to the amount of money earned on the platform.

Independent workers can choose to use these funds towards individual health insurance premiums. They can also choose to add the money toward paid leave or retirement. Individuals access the paid leave benefits by self-certifying that they have experienced a qualifying event, such as falling sick, needing to take care of a family member, or living under a state of emergency. Since there is no separation event for an independent contractor similar to an employee being laid off an employer, there needs to be a cutoff when this short-term insurance plan converts into a cash benefit. For example, at the end of the year, the unused benefit funds could be rolled into a retirement savings account.

In order to prevent a patchwork of state and local laws from developing, the new federal law needs to include preemption. This new regulatory model — in particular the social insurance component — is critical to solving market failures. To take one illustrative example, consider the negative externalities created during a pandemic. In the case of a contagious disease, one individual’s actions (such as wearing a mask) directly affect the likelihood of others getting infected. Similarly, there is a public interest in ensuring independent contractors aren’t financially pressured to work when they’re feeling sick. The government needs to create a new regulatory framework that incentivizes private sector companies to fund benefits programs such as sick leave or paid leave to reduce the recurrent negative spillovers in labor markets.

Cost

Obviously this new regulatory regime extends certain tax breaks now enjoyed by employees to independent workers as well, which incurs some hit to tax revenues. But note that the alternative solution to the independent contractor problem—redefining the dividing line so that more independent workers are reclassified as employees—also incurs a hit to tax revenues. Reclassification of independent workers as employees costs the federal government FICA tax revenues on employer contributions to healthcare and retirement plans. In addition, reclassification significantly reduces the amount of work (and therefore the amount of taxable worker pay) overall. 

Consider, for example, business payments for health insurance. As we saw earlier, for independent contractors who file a Schedule C, those health insurance payments can be typically deducted from taxable income, but not from the payroll tax base. By contrast, business payments for health insurance for employees are not subject to the payroll tax. So, legislation that forces independent workers into employee status ends up reducing payroll tax revenues, all other things being equal. This would reduce the public funds available for vital social insurance programs. 

This is not a final answer on the cost question, of course. But it does mean to get a good cost estimate, it’s necessary to compare apples to apples. Critically, businesses should incur the full cost of participating in the new framework we are proposing.

Conclusion

Independent workers face a dilemma where they cannot currently receive benefit payments from companies without risking their independent status. Meanwhile, they cannot provide benefits for themselves without being unfairly penalized by the tax code relative to employees.

Previous attempts at the state level to define a new category of “marketplace contractors” has not fixed this dilemma, because they did not address disparities in the tax treatment of benefits. Nor did they create a baseline benefit package that companies must provide. 

We suggest that it is possible to design a new regulatory regime that is a win-win proposition. It makes independent workers better off by making it easier for them to either get benefits from a company or provide the benefits for themselves, while still retaining the flexibility that is an essential attraction of independent work for most. At the same time, by allowing companies to opt into this new regulatory regime, it ensures that companies have an alternative to a patchwork of state regulations if they are willing to offer a baseline package of benefits. 
Return Free Filing Won’t Fix What’s Wrong With America’s Tax System

Because of COVID-19 Tax Day moved this year from April to July. That means the debate over the supposed panacea to the convoluted process of filing taxes – a return-free filing system (RFF) – is now making its annual appearance, albeit four months late.

The return-free filing idea has been around for a longtime and is currently in practice in Denmark, Sweden, Spain, and the United Kingdom (among other countries), places with limited or no tradition of voluntary compliance. If the U.S. government adopted RFF, the Internal Revenue Service (IRS) would estimate your taxes by using information from a mix of sources (depending upon the system) including employers, financial institutions, other third parties, and in some cases the individual taxpayer themselves. Proponents say (in effect) let the government do your taxes and spare you the burden of hiring a tax preparer, purchasing commercial tax software, or trying to do it yourself.

That sounds alluring, but it’s important to underscore the limits of what an RFF system could achieve and what it would not. For example, an RFF would not eliminate the $1.6 trillion in tax incentives that benefit primarily wealthier taxpayers. Nor would it raise revenue to build new roads, rail, or schools; support scientific research; pay down public debts; make the tax code fairer and more progressive; or, help us close our $458 billion annual tax gap (the difference between what is owed in taxes versus what is paid).

Rather, pursuing return-free filing is a way to avoid the hard choices needed to revamp our tax code to promote economic fairness and growth. It would put the burden of contesting initial tax determinations on the filers rather than on the IRS, fundamentally reversing the presumption of the tax system today. And, if truly voluntary, it is unlikely to have a significant impact on the way most Americans complete their taxes. In California, which proponents often cite as a good example of how an effective return-free filing can be implemented only about 90,000 people used “Ready Return” in any given year of that experiment (despite the some two million Californians that were annually offered the government-prepared tax returns) — putting into serious doubt the idea that a federal return-free filing system could be voluntary and actually achieve the purported national benefits it proponents claim will occur.

In fact, moving away from a voluntary tax filing system would actually worsen many of the problems that an RFF system is supposedly designed to fix — accuracy, tax evasion, and simplicity. Furthermore, were the U.S. to implement an RFF system, it would eliminate the moment of financial planning and review that is tied to the self-return process, and as the only time each year many households take stock of their finances, has an intrinsic value for American families.

Accuracy

As tax codes around the world have become more complex, many countries that are currently using RFF systems are increasingly finding it necessary to re-engage taxpayers in order to ensure accuracy. In the introduction to a 2017 report by the UK’s All-Party Parliamentary Taxation Group on Pay-As-You-Earn (PAYE), the RFF system utilized by the United Kingdom. Ian Liddell-Grainger, the Chair of this non-partisan policy committee and a Conservative Member of Parliament, noted that:

(Given) the changing nature of the workforce, a growing self-employed community and the complexity of our current system leading to significant overpayments…It is my firm belief that we need to involve the taxpayer in this process. It is them who can improve the accurate flow of information throughout the fiscal year.

The Parliamentary report found that as a result of a number of economic changes since the creation of PAYE, approximately one-third of British taxpayers were effectively filing their own taxes via a process known as Self-Assessment — negating much of the “will save the taxpayer time” rationale for a RFF system. The report cited a number of reasons for the increase in Self-Assessments, including a rising number of self-employed workers; a more mobile workforce; and an increase in tax code complexity driven in part by the growth in tax incentives.

Unfortunately for the PAYE system, these trends are likely to worsen over time given the growth in globalization and the growing mobility of the workforce.

The PAYE report also noted that error rates had been rising significantly in the United Kingdom, costing the government and taxpayers billions over the years. This counters another rationale for RFF — that no-file systems reduce the error rate and the thus help close the size of the tax gap. The parliamentary analysis points to exactly the opposite outcome in the real-world experience of their RFF in practice.

Tax Evasion

While unintended error is one major source of the tax gap, another is the intentional underreporting of income subject to tax — or tax evasion.

Some have argued that RFF systems could help reduce the tax gap because it would reduce underreporting. In a 2006 paper on return-free filing, Austan Goolsbee, former Chairman of the White House Council of Economic Advisers under President Obama, cites a 1996 General Accounting Office (GAO) report that concluded that a no-file system could help the Internal Revenue Service significantly reduce its number of “underreported” cases.

In a 2010 paper, economists Jeffrey Eisenach, Robert Litan, and Kevin Caves took a contrary view. They argued that the adoption of an RFF tax system would not have any impact on the U.S. tax gap, adding that it would

“do virtually nothing to reduce under- reporting on individual tax returns, because almost all under-reporting is associated with types of income that would make filers ineligible to use RFF in the first place.”

In fact, the authors contend that RFF might actually make the tax gap larger, since taxpayers who receive completed tax returns that understate their actual tax liabilities are not likely to challenge the IRS’s errors in their favor. Even Joseph Bankman, a longtime advocate of RFF, has explicitly acknowledged it could lead to greater opportunities for taxpayers to underpay what they owe.

In a 2017 article in Propublica, Bankman noted there were multiple ways taxpayers could benefit from an RFF system and stated that “If there’s a mistake that goes in your (the taxpayer’s) favor, maybe you don’t call attention to it.”

Supporting this argument is data on tax evasion in countries with return-free systems compared with the U.S, which relies on voluntary citizen compliance.

According to the Tax Policy Center (TPC), 36 countries permit return-free filings for some taxpayers. This is typically accomplished in one of two ways. In the pay-as-you-earn systems used in Japan, Germany, and the United Kingdom, the government calculates tax withholding to match the amount of annual taxes due. Most citizens, particularly those whose income is derived from a single employer, never even see a tax return.

Other nations like Belgium, Spain, and Denmark, use what’s called a pre-populated return. Employers report individuals’ income directly to the government, which then sends the taxpayer a pre-filled return he or she just has to verify.

In Table 1 we compare tax evasion rates in 13 countries — six that use pay-as-you-earn systems in which the government calculates withholding, six that pre-populate returns with information provided by employers, and one, the United States, where citizens file their own tax returns. (Tax evasion data was not available for all 36 countries using RFF)

The average rate of tax evasion as a percentage of GDP for the 12 countries on this list was 1.45. For those countries that have pay-as-you-earn systems, the average was 1.35. For those with a pre-populated return system, the average level was 1.71. In contrast, the level of tax evasion for the United States as a percentage of GDP was only 0.1.

While many other factors need to be taken into account when looking at what is responsible for the different levels of tax evasion by country, including trust in government, complexity of the tax code, type of taxation (income tax, sales tax, etc.), and effective rate of taxation, it is nevertheless of interest that the U.S. had a significantly lower level of tax evasion as measured by GDP than those countries that utilized either system of return free filing.

Simplicity

Proponents of return-free filing say it would greatly simplify the process of filing taxes. Goolsbee argued in 2006 that moving to a return free filing system would save taxpayers 225 million hours of tax compliance time.

However, it’s doubtful that such savings would materialize in the United States. We have a very complicated tax system. Governments at the federal, state and municipal levels all have taxing authority.

The federal tax code, moreover, is encumbered with $1.6 trillion worth of tax incentives for a vast array of activities. And because we have a large number of self- employed workers and two-income families, moving to an RFF system would still necessitate a great deal of taxpayer involvement to ensure accuracy, completeness, and fairness.

Adopting an RFF would not address the growing complexity of the U.S. tax code. In fact, if an RFF system works as its proponents argue, it would leave the status quo in effect – an inefficient tax code riddled with tax breaks that disproportionately benefit wealthy taxpayers at the expense of working class families.

As PPI has long contended, what America really needs is a comprehensive overhaul of
the tax code, not an army of government tax collectors doing your taxes for you. In addition to big changes in what we tax and restoring progressivity, radically streamlining the tax code is the right way to make our government more user-friendly and to reduce the time and money citizens spend on filing their taxes.

Financial Planning

One often overlooked benefit of America’s tradition of voluntary tax compliance is that it educates citizens about their financial condition.

Ironically, filing one’s taxes provides a window of opportunity during which Americans can review their financial history from the prior year and reassess their needs for the future — such as how much to save for retirement.

But shifting to an RFF system would eliminate or reduce that educational moment. As former Senator (and co-chairman of the National Commission on Restructuring the IRS) Bob Kerrey noted in an article for Time Magazine entitled “Beware of Simple Solutions to the Tax Code:”

“Perhaps the worst aspect of the simple return is that it reduces or eliminates
one of the most important activities that occur during the tax-filing season: individual financial review and planning. Calculating how much we owe in taxes is an unpleasant activity, but it is also central to understanding our personal financial situation and planning our financial futures — and often the only time all year that the average family looks at its finances.”

As exasperating as it can be, doing your own taxes, and understanding you family’s financial relationship with government, is more worthy of a free and self-reliant citizenry than delegating that responsibility to government tax collectors. We shouldn’t reduce taxpayer engagement in their own financial affairs simply to avoid the hard work of passing and implementing real tax reform. The impact of greater taxpayer disengagement from their own personal finances is not an inconsequential consideration as a matter of national economic policy. To the contrary, numerous analyses of the national savings rate and financial literacy underscore the need for more personal engagement in one’s financial affairs—not less.

Conclusion

Nobody enjoys paying taxes, and the U.S. tax system leaves a lot to be desired. It is overly complex, wasteful, does not raise enough revenue to cover the needs of its citizens, and tilts toward the interests of the wealthy. Moving to a return free filing tax system would not address any of those problems. If policymakers want to reduce the amount of time taxpayers spend on filing taxes, they should be not be distracted by magical panaceas, but rather aim their sights on creating a simpler, more efficient and fairer tax system that promotes economic growth and equity.

Statement on the Passing of Congressman John Lewis

Farewell to a Freedom Rider.
Rep. John Lewis was an authentic American hero. From the Freedom Rides to the march on Selma Bridge, he repeatedly and courageously put his life on the line in the struggle to dismantle Jim Crow segregation in the South. As leader of the Student Non-Violent Coordinating Committee, Lewis and his colleagues wielded the moral power of non-violent resistance to awaken the nation’s conscience and pave the way for the landmark Civil Rights victories of the 1960s.
John Lewis continued to serve his country in Congress, where his moral courage and inspirational leadership made him a beloved and revered figure. America will miss his prophetic voice.
###

Teacher-centric is good, but student-centric is better

But the “unity” task force left out some important voices. It included both presidents of the two largest teachers’ unions, as well as several vocal critics of public charter schools. Excluded from the task force was any representative of the 3.3 million mostly Black and brown families who depend on charter schools for equitable access to quality education. In fact, no Black education stakeholders, other than Rep. Marcia Fudge (D-Ohio), were given a seat at this particularly important table — a puzzling omission against the backdrop of current events, not to mention the Obama-Biden administration’s strong backing of charters.

Given its makeup, it’s no surprise that the task force report trots out the oft-refuted canard that charter schools “undermine” traditional schools. The National Education Association (NEA) used identical language in a 2017 policy statement pledging “forceful support” for limiting charter schools. “The growth of charters has undermined local public schools and communities, without producing any overall increase in student learning and growth,” the NEA claimed.

Read the full piece here.

PODCAST: Should we abolish tax returns? A conversation with Sen. Bob Kerrey

As millions of Americans rush to file their tax returns, former Senator Bob Kerrey joined the Center for New Liberalism and the Progressive Policy Institute’s Paul Weinstein and Alec Stapp to discuss whether or not the US government should adopt return-free filing for individual taxes. The participants discussed the costs and benefits of return-free filing relative to our current voluntary tax filing system, the main problems with our current tax system, and whether or not return-free filing would reduce tax evasion.

FICO rolls out new credit scoring model

Consumers are getting turned down for all sorts of financial products, from personal and auto loans to credit cards. The Wall Street Journal, using Equifax data, reports that credit card approvals totaled 483,000 in the week ending May 10, down from 856,000 in the week ending March 22. To compare to the year prior, weekly card approvals in 2019 “rarely fell below 1.2 million,” according to The Wall Street Journal.

But as banks are tightening their lending requirements, a new tool is trying to prevent lenders from cutting off consumers’ access to credit.

Fair Isaac Corp., the data analytics company behind the FICO credit score, has just launched the FICO Resilience Index, a new scoring model designed to help lenders better assess consumers’ sensitivity to financial stress by looking at their capacity to survive financially though a downturn.

“The FICO Resilience Index, used in conjunction with a FICO Score, allows card issuers to limit access less than they otherwise would have because they can now identify borrowers who are more resilient to the economic downturn,” Sally Taylor, VP of FICO Scores, tells CNBC Select.

FICO defines resilient borrowers as “consumers that are more likely to pay as agreed in the event of a recession.”

The new scoring model ranks consumers’ resiliency on a scale of 1 to 99. The higher your score, the higher the risk you will default on your payments; the lower your score, the more likely you are to make on-time payments even when the economy experiences a downturn.

Read the full piece here.

This piece was originally published on CNBC by Elizabeth Gravier on June 29, 2020.

Economic Impacts of a Moratorium on Consumer Credit Reporting

Two bills introduced in Congress, H.R. 6370 and S. 3508, ‘‘Disaster Protection for Workers’ Credit Act of 2020’’ would impose a moratorium on credit reporting of “adverse information” for the duration of the coronavirus crisis. Credit scores are an integral part of the consumer credit underwriting process as their power to predict the likelihood of borrower default is well-established empirically. Consequently, lenders have come to heavily rely on the integrity and information content of credit scores as a critical measure of a borrower’s creditworthiness.

Economic theory suggests that in the absence of viable mechanisms to effectively distinguish between high and low risk borrowers, lenders will ration credit. Under a credit reporting moratorium, the reliability of credit scores to distinguish between borrower risks would come into question. Lenders would respond to the proposed credit reporting moratorium by raising minimum credit score requirements and/or raising borrowing rates as a credit uncertainty premium to offset the risk they face from the moratorium. During the 2008 financial crisis, lenders raised credit score minimums on FHA loans, for example, beyond those set by the agency as a response to uncertainty over indemnification provisions that posed significant costs to lenders. And today, during the coronavirus, a number of Ginnie Mae originators have raised credit scores to blunt some of the risk they face due to requirements to pass-through mortgage payments to investors, including those in default or subject to forbearance.

Read the full piece here.

This piece was originally published on Chesapeake Risk Advisors, LLC by Clifford Rossi on June 17, 2020.

WEBINAR: What Worked: Remote Instruction During COVID-19

When America’s schools abruptly closed in March, few had strategies for keeping students engaged. Watch RAS Associate Director Tressa Pankovits, as she moderated a 90-minute interactive discussion with CRPE and Public Impact analysts who co-presented comprehensive new data on how school systems performed, and top educators shared how their teams excelled under pressure.

Panelists include:

Bree Dusseault, Practitioner-in-residence at the Center on Reinventing Public Education

Lyria Boast, Vice president for data analytics and a senior consulting manager at Public Impact

Joyanna Smith, DC Regional Director at Rocketship Public Schools

Amy D’Angelo, Regional Superintendent, Achievement First Charter Schools

Brian Riddick, Principal at Butler College Prep, of Noble Network of Charter Schools

Moderator: Tressa Pankovits, Associate Director, Reinventing America’s Schools Project

Our educator panelists described their fast pivot from the classroom to the cloud, and they shared their strategies for ensuring distance learning was effective, including setting high expectations and relentless student engagement. They dissected lessons learned, and examined pitfalls to avoid in the coming school year.

Watch here.

PPI Statement on the FDA’s Modified Risk Assessment of IQOs

PPI strongly supports science-based regulatory policy, no matter where the evidence leads us. This means tackling tough problems with an open and pragmatic mind to achieve the best possible outcomes. Moreover, we place a high premium on clear communication of information relevant for public health, especially in today’s turbulent times.

From that perspective, we applaud the FDA’s authorization of “the marketing of Philip Morris Products S.A.’s “IQOS Tobacco Heating System” as modified risk tobacco products (MRTPs).”

These are the first tobacco products to receive what the FDA calls an “exposure modification order.” That permits “the marketing of a product as containing a reduced level of or presenting a reduced exposure to a substance or as being free of a substance when the issuance of the order is expected to benefit the health of the population.”

In other words, the FDA specified precise language that the manufacturer could use, including that “switching completely from conventional cigarettes to the IQOS system significantly reduces your body’s exposure to harmful or potentially harmful chemicals.”  And that’s a good thing!

The Uneven Distribution of Pain: Healing the Broken Labor Market

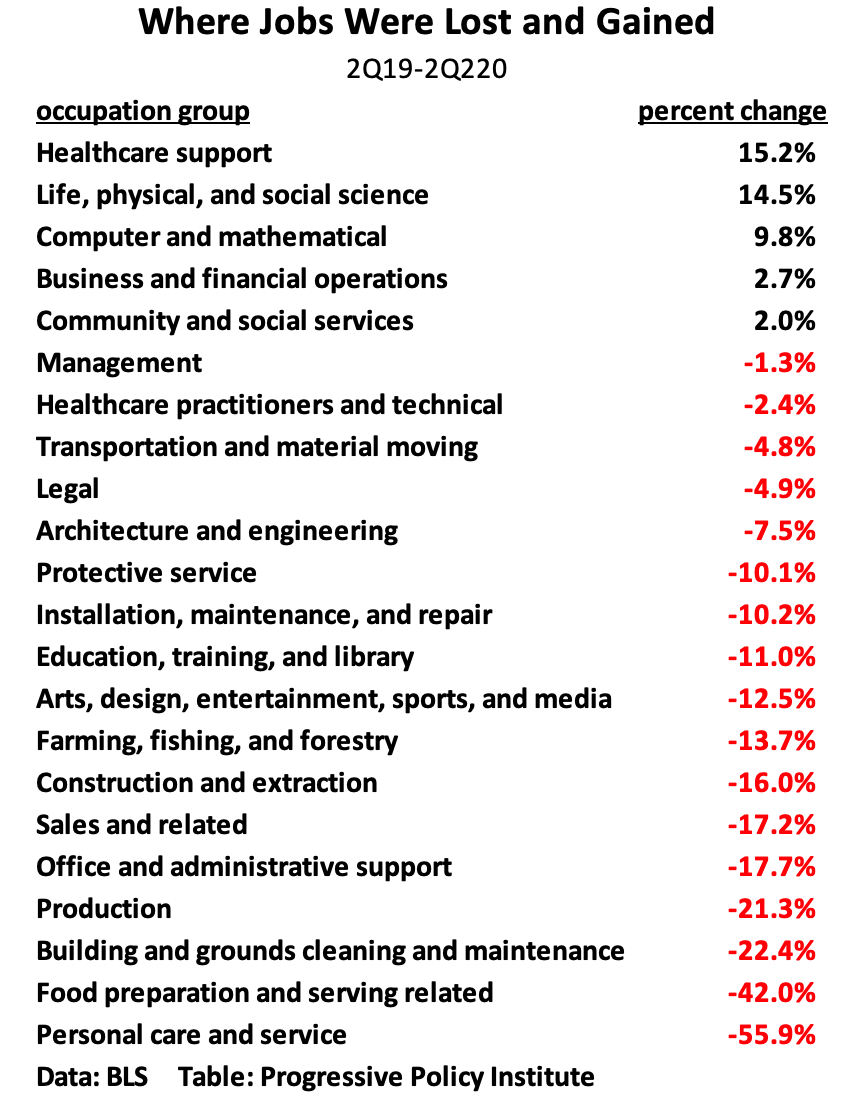
The Covid recession is the most uneven economic downturn in history. Take a look at the following table, which we calculated from last Thursday’s employment data.


The table compares occupational employment in the second quarter of 2020 with the second quarter of 2019.  On the one hand, some occupations, like computer and mathematics-related jobs, have seen a significant employment gain over the past year of almost 10%. On the other hand, food preparation  and personal care jobs  saw an almost inconceivable plunge in excess of 40%.  Production jobs are down more than 20%.

This differential frames the economic task ahead.  How can we make sure that these workers, detached from the labor force, can find new jobs quickly when the economy starts to recover? Moreover, many of the businesses where they were formerly employed are likely to have disappeared as the country continues to stagger under the pandemic.

PPI has identified several policy prescriptions that can help. Just to summarize here:

First, policymakers must make it easier for the small businesses that survive to quickly expand to fill the void, especially in the hard-hit restaurant and personal care industries. Elliott Long describes how adopting a “startup tax credit” can help encourage small businesses to grow. Designed like the earned income tax credit, but only for businesses, the startup tax credit helps give small companies a boost in the right direction. In addition, state and local governments need to be wary of regulations that make it harder for companies to expand.

Second,  the U.S. has to adopt policies to encourage shorter supply chains and  manufacturing entrepreneurship, It should be a national imperative to help small manufacturers adopt digital technologies that make them more flexible and able to compete with foreign suppliers, and then connect them up with larger buyers.

Third,  any economic recovery and infrastructure legislation should include large investments in clean manufacturing, as Paul Bledsoe of PPI has advocated in a recent report.  That means many more production and construction jobs building  electric vehicles, charging stations and other elements of green technology, while upgrading all of our essential infrastructure.

Fourth, digital technologies can help connect up workers with open jobs much faster. We’ll be writing more about that soon.

The UK Online Ad Market

Last year I did a paper entitled The Declining Cost of Advertising: Policy Implications. Not surprisingly, I was intrigued by the new report from the Competition and Markets Authority in the UK, entitled Online platforms and digital advertising market study . I’m still going through the report, which exceeds 400 pages, not including multiple appendixes.

But I just want to highlight one important point. The report repeatedly alludes to the impact of advertising on consumer prices for goods and services. For example:

The costs of digital advertising, which amount to around £14 billion in the UK in 2019, or £500 per household, are reflected in the prices of goods and services across the economy. These costs are likely to be higher than they would be in a more competitive market, and this will be felt in the prices that consumers pay for hotels, flights, consumer electronics, books, insurance and many other products that make heavy use of digital advertising.

But here’s the thing—ad spend in the UK, measured as a share of UK GDP, is more or less flat over the past thirty years (chart below). There’s no evidence that the burden on advertisers or consumers has increased because of the arrival of Google and Facebook to the UK ad market.  Indeed, it may have gone down a bit,  comparing the 1.1% peak in 2019 with the 1.2% peak in 2000, before Facebook existed and when Google advertising was first getting started.


Given how many places ads appear these days, it’s reasonable that advertising in the UK has become much more intensive over time–that is, in real units advertising has grown faster than overall real UK GDP. If so, then the shift to digital advertising has coincided with a fall in the price of advertising relative to other UK goods and services. The easiest interpretation, at least for me, is that advertisers are consistently getting a bigger bang for their buck from digital advertising, without paying more in total.

A Transatlantic Digital Trade Agenda for the Next Administration

CAN A NEW DEMOCRATIC ADMINISTRATION RECONSTRUCT DIGITAL TRADE POLICY WITH EUROPE FROM THE ASHES OF TTIP?

As the global leader in digital trade, the United States has a big stake in ensuring that international rules facilitating its continued expansion are put in place.

The Obama Administration’s bold agenda to establish these rules across Europe and the Asia-Pacific did not yield lasting success, with the failure of the Transatlantic Trade and Investment Partnership (TTIP) negotiations and the Trump Administration’s withdrawal from the Trans-Pacific Partnership (TPP). Nonetheless, the key elements of US digital trade policy enjoy bipartisan policy support, providing a promising basis for the next Democratic administration to re-engage with Europe, our biggest digital trading partner.

Part 1 of this issue brief explains why international rules are needed to protect and facilitate digital trade. Part 2 describes the turbulent past decade in transatlantic trade relations and the growing importance of US digital trade with Europe. Part 3 explains why the US government and the European Union (EU), during TTIP negotiations, were unable to agree on a digital trade chapter, including a key provision guaranteeing the free flow of data. Finally, Part 4 suggests how two parallel sets of trade negotiations beginning early this year — between the EU and the United Kingdom (UK) and between the United States and the UK — may help a future US Administration end the transatlantic stand-off over digital trade.

1. THE CASE FOR DIGITAL TRADE AGREEMENTS

The United States leads the world in the fast-growing digital economy.1 Digital services include not just information and communications technology (ICT) but also other services which can be delivered remotely over ICT networks (e.g. engineering, software, design and finance).2 Although trade in digital services is hard to measure precisely, there is no mistaking that it has become one of the fastest-growing areas for the United States internationally. In 2017, all types of digital services made up 55% of all U.S. services exports, and yielded 68% of the U.S. global surplus in services trade.3 The beneficiaries of this burgeoning area of trade are not just the U.S. technology giants, but also many smaller and medium-sized companies that develop and sell digital services or use ICT networks for marketing products to consumers.

More than a decade ago, the Office of the US Trade Representative (USTR) recognized the US comparative advantage in digital services trade and began to pursue binding rules with a number of foreign governments. TPP negotiations were the first major step in this direction. The TPP agreement signed by the Obama Administration included provisions designed to protect against practices harmful to digital trade. It prohibited:

  • Customs duties and other discriminatory measures on digital products like e-books, movies, software and games;
  • Requirements that data or computing facilities be localized in the foreign jurisdiction;
  • Discriminatory treatment of crossborder data flows;
  • Obligations to use local technology, content, or suppliers;
  • Discriminatory foreign standards or burdensome testing requirements; and
  • Requirements for disclosing source code and algorithms.

TPP also included facilitative measures:

  • Requiring governments to adopt measures to protect against on-line fraud and guard consumers’ personal information;
  • Promoting cooperative approaches to cybersecurity; and
  • Facilitating the use of electronic authorizations and signatures for e-commerce, electronic payments, and other on-line applications

President Trump’s decision to withdraw the United States from TPP left US digital services companies exposed to these harmful practices in the Asia-Pacific region. From the perspective of liberalizing and expanding US digital trade, it was a spectacular own goal.4 However, USTR quickly set out to partially mitigate its effect by seeking bilateral trade accords with some TPP signatories. Digital chapters in the updated Korea-US Free Trade Agreement (KORUS), the new US-Mexico-Canada Free Trade Agreement (USMCA), and, most recently, the Japan-US Digital Trade Agreement largely duplicate the TPP’s digital trade provisions.

2. THE TRANSATLANTIC TERRIBLE TEENS

Transatlantic trade politics also has seen its share of drama over the past decade. The comprehensive TTIP negotiations begun in 2013 badly backfired. Popular fears of US corporate domination flared across Europe, the EU’s member states failed to back the project enthusiastically, and progress between US and European Commission negotiators on the many subject-matter chapters proved glacial. As the Obama Administration came to an end, TTIP talks were quietly shelved.

The Trump Administration’s trade agenda for Europe has been strikingly different. It has concentrated on rectifying the sizeable US deficit in merchandise trade with the EU, which reached an estimated record high of $168 billion in 2018.5 The President demanded that the EU, which is solely responsible for the bloc’s international trade relations, address the imbalance in such areas as steel, aluminum and automobile trade. (He also somewhat mystified Germany by insisting that it negotiate directly with the United States to reduce the U.S. goods trade deficit.) The US Government determined that a number of jurisdictions including the EU had engaged in trade practices unfair to US steel and aluminum, and imposed higher tariffs on these imported products as a consequence; higher tariffs on European autos so far remain a threat.

In the summer of 2018, European Commission (then-)President Jean-Claude Juncker managed partly to defuse transatlantic tensions by agreeing to negotiate with the United States on increasing EU purchases of US-made industrial goods and on related regulatory standard.

Juncker also committed to greater European purchases of US natural gas and soybeans. Trump in return agreed not to proceed with unilateral tariff increases for the time being. Since the advent of new EU leadership late last year, USTR Robert Lighthizer and his Commission counterpart Philip Hogan have stepped up efforts toward reaching, before the 2020 US presidential election, a limited accord in the areas identified by Trump and Juncker.

Throughout the decade, the volume of goods and services trade across the Atlantic has continued to grow steadily. The United States and the European Union are still each other’s largest trading partners. US goods exports to the EU grew to $293 billion in the first eleven months of 2018, a 13% increase over the previous year.6 US exports of all types of services to the EU reached a record $298 billion in 2017, resulting in a $66 billion surplus in 2017.7 European countries comprise four of the top ten export markets for US services, and in 2017 the Union as a whole absorbed 37% of US services exports.8

Despite the continuing growth in trade, the next Democratic administration will inherit a transatlantic trade policy environment characterized by an unusually high level of tension and distrust. TTIP’s failure appears to have stifled any impulses in Washington and Brussels simply to resume the slog towards a comprehensive trade agreement. Still, there are good reasons for Democrats to not abandon the work begun on digital trade during the TTIP negotiations.

3. THE US DIGITAL TRADE IMPASSE WITH EUROPE

Since Trump’s trade ambitions with the EU remain firmly focused on the goods deficit, the question of whether the United States should resume direct digital services trade negotiating efforts with Europe seems likely to be deferred till the next administration. From an economic perspective, the case for US re-engagement is compelling. In 2017, the United States exported $204.2 billion in digital services to Europe, generating a surplus in this area of more than $80 billion.9 International data flows, measured in terms of capacity for data bandwidth, also are heavily skewed in a transatlantic direction. Cross-border data transfers between the United States and Europe, by this measure, are 50% higher than those between the United States and Asia.10 In sum, the transatlantic area is the world’s largest for digital trade.

During TTIP negotiations, the United States proposed language close to TPP digital trade provisions, but the EU objected to a number of them. One of the most important was a US proposal to guarantee cross-border ‘free flow’ of electronic information for business purposes, and to put bounds on the extent to which European public policy measures relating to personal privacy could serve as an exception to unrestricted data flows.

The United States proposed that public policy exceptions be allowed, but that they be subjected to long-established World Trade Organization (WTO) disciplines. These WTO rules allow for exceptions for legitimate public policy objectives, so long as they do not constitute arbitrary or unjustifiable discrimination or disguised restrictions on trade, and they are narrowly tailored to achieve a public policy objective.11 Alleged breaches could ultimately be addressed through a formal dispute settlement system, if necessary.

The EU regarded the US proposal as an attack upon its unfettered discretion to apply its privacy laws to data moving across the Atlantic, and it rejected the possibility of any discipline based upon WTO rules. The EU’s rejection of objective limits on its potential public policy measures leaves it free to invoke privacy rules as a basis to discriminate against US digital service providers or to protect local competitors. The issue remained firmly deadlocked when TTIP negotiations were set aside.12 Since then, the United States and the EU have not re-engaged bilaterally on digital trade rules.

Both governments are among the eighty countries participating in a low-profile multilateral negotiation on electronic commerce (e-commerce) launched a year ago under WTO auspices, however.13 In Geneva, the United States has tabled a similar proposal to its TTIP and TPP language; the EU so far has not managed to offer a counter-proposal. For the time being, it seems unlikely that the WTO negotiations will yield quick success in settling the disagreement between the EU and the United States and other like-minded countries on regulatory limits to the free flow of data.14

A new Democratic Administration should engage bilaterally with the EU to see if there might be scope for a targeted digital trade agreement, but without softening its insistence on a rigorous free flow of data obligation. Agreeing with the EU on the proper scope for public policy exceptions should not be an impossible task, as WTO rules provide a useful framework. Moreover, it is conceivable that the new leadership of the European Commission at some point will consider jettisoning its insistence on a selfjudging privacy exception, in favor of language more consistent with international trade law.

4. BREXIT AND DIGITAL TRADE

Following Britain’s January 31 departure from the European Union, it now has embarked on the urgent task of negotiating its future economic relationship with the EU. Brexit notwithstanding, the EU will remain the UK’s principal trading partner; 45% of overall UK exports in 2018 were destined for the Continent.15 At the end of 2020, however, if no accord is reached, EU tariffs and quotas on UK exports would revert to much higher WTO tariff levels, which would have a damaging effect on UK-EU trade.

In addition to fixing tariff levels, Britain and the UK also must agree on the extent to which the UK will continue to adhere to EU regulations in a host of areas – for example, workers’ and consumers’ right, the environment, and antitrust. Many observers expect the UK-EU talks on these non-tariff barriers to be difficult and drawn out, likely stretching beyond the 2020 deadline. Despite continuing tough UK rhetoric, the parties may well settle for a ‘phase one’ agreement on goods tariffs, and grant themselves an extension into 2021 or beyond to complete the rest of a comprehensive agreement.

Setting the terms for digital trade with the EU will be particularly important for Britain. UK services exports to the EU yielded a £77 billion surplus in 2018, more than offsetting a deficit in goods trade.16 Approximately three-quarters of Britain’s data flows are with EU countries17, making harmonization with the Continent on privacy regulation crucial for its thriving data-dependent businesses, such as financial services.

In its negotiating mandate for the future economic partnership agreement with the UK, the EU specifically calls for provisions facilitating digital trade, but also indicates an intention to “address data flows subject to exceptions for legitimate public policy objectives, while not affecting the Union’s personal data protection rules.”18 The UK’s counterpart negotiating mandate similarly calls for measures to facilitate the flow of data to and from the EU, and expresses an ambition to go beyond the digital trade provisions in the EU’s trade agreements with other countries.19

The Union previously had pledged to decide before the end of 2020 whether the UK’s postBrexit privacy protections are ‘adequate’ in relation to those on the continent; an adequacy determination would be by far the most favorable and efficient legal basis for data flows across the Channel.20 The EU should have leverage in this separate negotiation, and as a result the UK’s future data protection regime should remain generally close to the EU’s General Data Protection Regulation (GDPR). An adequacy finding is not a foregone conclusion, however, as Britain may be reluctant to alter its wide-ranging surveillance laws.21

The United States is also a very important trading partner for the United Kingdom, accounting for 15% of Britain’s total trade.22 Nearly a fifth of Britain’s exports head across the Atlantic, more than double the share it sends to Germany, its next-biggest trading partner.23 US services trade with the United Kingdom exceeds goods trade, and is growing; US services exports measured $74.1 billion in 2018, generating a surplus of $13.3 billion that year with Britain.24 There are more transatlantic undersea cable connections transmitting data directly between the United States and the United Kingdom than with the rest of Europe combined.25 Foreign affiliates of U.S. multinationals supply more information services in the United Kingdom than in any other European country.26

The Office of the US Trade Representative and the UK Department for International Trade started negotiations on a bilateral trade agreement in May. The United States seeks a comprehensive agreement with the British, including a chapter on digital trade in goods and services and cross-border data flows modeled on the most recent U.S. bilateral successes with other countries.27 The United Kingdom’s negotiating objectives with the United States are broadly consistent with the United States perspective on digital trade.28 They specifically mention the importance of preserving UK data protection rules in an agreement with the United States.29 The United States officially attaches the highest priority to these negotiations and aims to complete them in 2020.30 Privately, US officials acknowledge that the United Kingdom will have to give greater priority this year to redefining its all-important trading relationship with the EU, before US-UK talks can advance definitively.

The most that US and UK trade negotiators may be able to deliver this year is a partial agreement setting tariffs and quotas for goods. A new Democratic administration would be well-advised to build upon whatever progress is achieved with the UK this year, and to give particular priority in the future to agreement on digital trade. The latter could even take the form of a stand-alone agreement on digital trade, as was done in the Japan – United States Digital Trade Agreement, if a comprehensive US-UK trade agreement proves a longer-term prospect.

The United States and the United Kingdom should be able to make rapid progress on many aspects of a digital trade agreement. Historically, both governments have shared a philosophical commitment to open international trading regimes. Both have highly developed digital economies and leading-edge digital services companies. Each favor free data flows and opposes data localization measures. Intangible factors including similar legal traditions also could speed talks.

The long arm of the European Union will constrain the United Kingdom’s negotiating room on digital trade with the United States, however. The EU may insist that, as part of the price for adequacy, the UK agree not to undermine the Union’s position on data flows in any of the UK’s future trade agreements with third countries. The United States, for its part, presumably would take the same position on this issue as it took in TTIP – that legitimate privacy measures are those permitted under WTO principles rather than by EU fiat.

Still, in the short term, the United States may be better off tackling this tough issue with the United Kingdom than seeking to resolve it bilaterally with the EU. The British are in a tough negotiating position: they must find a way forward on data flows with both the EU and a range of important third country trading partners. UK negotiators will need all their creative legal talents to find a way through this intersection of digital trade and privacy law. If they succeed, the payoff in a settled legal landscape for digital trade across both the Channel and the Atlantic eventually could be substantial. Brexit has generated considerable trade uncertainty, but it also ultimately could yield dividends for digital trade.

Privacy Wars: Peril and Promise for Transatlantic Data Transfers

Authored by Ken Propp, Professor of European Union Law, Georgetown University Law Center; Senior Fellow, Atlantic Council; PPI Fellow

In May 2013, Edward Snowden publicly disclosed a trove of highly-classified information about US signals intelligence programs around the world, unleashing a torrent of outrage both in the United States and abroad.  Nowhere did his revelations have a bigger impact than in Europe, where the extent of activities conducted by the US National Security Agency, sometimes with the cooperation of foreign intelligence services, came as a huge shock.

European Union officials were chagrined — and a little flattered — to learn that internal conversations with their overseas delegations had been intercepted.  German headlines trumpeted the alleged tapping of Angela Merkel’s personal cellphone.  Snowden’s revelations sharply disrupted the generally cooperative character of US-EU relations. “It seemed that the entire well of US-EU relations had been poisoned by the fallout from the Snowden affair,” the US Ambassador to the European Union during the period has written, citing its political impact on negotiations over a potential transatlantic free trade agreement, among other effects.

In Brussels, the evident scale of NSA surveillance was perceived as a challenge to ‘data protection’, the extensive body of privacy law that is one of the EU’s signature regulatory initiatives.  Snowden’s disclosures provoked an almost existential crisis in Europe about whether privacy protection even mattered.  Not long after, European privacy activists went to court to challenge the legitimacy of data transfers to the United States, in a series of cases that rumble on to this day. Their efforts have upended one US-EU data transfer agreement, the Safe Harbor Framework, and now threaten to do the same for the successor Privacy Shield, as well as for contract-based privacy protections.

The political impact in Europe of the Snowden revelations inevitably has diminished over the past seven years.  Today Europeans worry as much about weak privacy standards in authoritarian countries as about US surveillance practices.  In addition, as governments around the world struggle to overcome COVID-19, they see data-tracking technologies as a key part of the solution – and worry less about the attendant privacy risks.  Indeed, European governments are embracing data-tracking to a far greater extent than is the United States.

The forthcoming ruling by the European Court of Justice (ECJ)in the Snowden-legacy cases – due to be handed down on July 16 — has the potential to do more than reopen old wounds. Even more ominously, it may cause disarray in transatlantic digital commerce – at a time when governments cannot afford further economic damage.

A new Democratic Administration would be forced to confront the unresolved challenges of keeping data flowing across the Atlantic. How should the US Government respond if the ECJ again finds US privacy protections against surveillance of Europeans’ personal information to be insufficient? Is it finally time for the United States to directly challenge Europe’s efforts to impose its privacy rules on US national security data collection? Is there still room for compromise? Could a comprehensive US privacy law be part of the solution? 

Privacy Rules in Transatlantic Commerce

The European Union prides itself on regulating commerce in a manner that is extremely solicitous of potential harms to individuals. It follows the ‘precautionary principle’, under which a product may only be introduced onto the European market if it can be proven to present no risk to consumers. Applying this standard is harder in the case of services than goods, especially when a service is provided from abroad and entails the transfer of personal data outside of Europe.

The EU’s data protection law, the General Data Protection Regulation (GDPR), provides a way to minimize the risk that individuals’ personal data will be misused when it is transferred abroad. It does so by establishing a ‘border control’ regime for data transfers from Europe. An international data transfer may only occur if there is a legal arrangement in place “to ensure that the level of protection of natural persons guaranteed by this Regulation is not undermined” in other jurisdictions.  In other words, a European can rest assured that a company processing his or her data abroad does so in broad conformity with the EU’s privacy rules.

Data has become a central commodity in transatlantic – and global – commerce of all types, not just for services which are delivered using information and communications technology. When a European consumer makes purchases a good from a US online marketplace, his or her personal data travels to America through undersea cables as part of the transaction. Multinational companies are constantly shifting personal data around the globe, for services as mundane as personnel management. Global data transfer rates expanded more than 40 times over the decade between 2005 and 2014, and continue to grow rapidly, particularly across the Atlantic.  Cross-border data transfers between the United States and Europe are 50% higher than those between the United States and Asia.

A company importing personal data from Europe into the United States typically chooses between two principal transfer methods, outlined in the GDPR, for guaranteeing the continuity of privacy protection. One is to subscribe to the privacy principles set forth in the US-EU Privacy Shield framework.  More than 5300 companies – many small- and medium-sized businesses among them — have done so.  The EU deems data transfers made by these companies to the United States to afford an ‘adequate’ basis of privacy protection. The US Commerce Department monitors signatory companies’ compliance with the Privacy Shield principles, and the Federal Trade Commission (FTC) has authority to enforce against those that fail to honor their commitments. 

A company’s main alternative to joining the Privacy Shield is to insert into individual contracts for data transactions certain standard privacy protection clauses that have been pre-approved by European data protection authorities (DPAs). In other words, a data importer outside the EU assumes a contractual obligation to handle data in conformity with the privacy terms laid down by the exporter inside the Union. Companies, especially larger ones, widely use standard clauses to transfer personal data from Europe to many parts of the world, not just across the Atlantic. European DPAs enforce compliance with standard privacy clauses.

Privacy Rules and National Security Surveillance Collide

The Privacy Shield, while popular with companies, rests on a shaky legal foundation. It was hurriedly negotiated between Washington and Brussels after the ECJ in 2015 had effectively invalidated its predecessor, the 2000 Safe Harbor Framework. The court did so in response to a petition from Austrian privacy activist Max Schrems, who had read Edward Snowden’s allegations that US social networks were providing foreigners’ communications to the NSA, and believed (without any supporting evidence) that his own Facebook communications had made their way to Fort Meade.

Facebook at the time was using the Safe Harbor Framework as the legal basis for its data transfers from the Continent. Schrems pointed out that a provision in the Framework in fact excused a company from complying with its privacy protections if confronted by a US national security agency’s demand for personal data. Such demands, the ECJ decided, permitted the NSA “to have access on a generalized basis to the content of electronic communications,” and “must be regarded as compromising the essence of the fundamental right to respect for private life…” contained in the EU’s Charter of Fundamental Rights. The ECJ went on to find deficiencies in a number of other features of Safe Harbor, including its failure to provide aggrieved individuals with a right of effective redress for violation of its provisions.

Schrems’ case represented the collision of two worlds – the straightforward one of companies transferring personal data for purely commercial purposes, and the shadowy one of governments obtaining these communications for purposes of protecting national security. It shone a spotlight on the United States, not only because American internet platforms dominate the data transfer business worldwide, but also because US intelligence agencies operate on a much larger scale than do European counterparts. 

The EU’s negotiations with the United States to remedy the deficiencies of the Safe Harbor faced legal as well as political hurdles.  Since the EU Charter of Fundamental Rights is effectively the equivalent of the US Bill of Rights, ECJ judgments applying its provisions have the character of constitutional jurisprudence.  The European Commission, the EU’s executive arm, must scrupulously respect the Court’s holdings, and has only as much international negotiating room as the judges have allowed.

The Privacy Shield remedied some of the ECJ’s criticisms of the Safe Harbor Framework. It strengthened the privacy principles, beefed up the roles of Commerce and the FTC in overseeing compliance, and created an administrative channel for Europeans to complain to an ombudsperson in the State Department if they suspected that the NSA was sifting their personal information. 

The United States even sought to address European concerns about national security surveillance.  A pair of letters appended to the Privacy Shield from Office of the Director National Intelligence (ODNI) General Counsel Robert Litt described recent changes to the US legal framework for signals intelligence.  Litt highlighted the Obama Administration’s issuance, in the Snowden aftermath, of a policy directive (PPD-28) that extended partial privacy protections to foreign nationals and limited the NSA’s bulk collection of certain types of personal data.  He also pushed back on the ECJ’s impression that America’s national security data collection efforts were vast. “Bulk collection activities regarding Internet communications that the US Intelligence Community performs through signals intelligence operate on a small proportion of the Internet,” Litt wrote. What US negotiators steadfastly refused to do, however, was to agree to any further limits on their government’s wide-ranging legal authority to surveil Europeans’ communications.

Europe’s privacy activists were distinctly unimpressed by the new, improved transatlantic data transfer arrangement. Soon after the Privacy Shield took effect, a French group filed suit against it in the ECJ. Max Schrems separately chose to refocus his sights instead on standard contract clauses, the alternative transfer mechanism which Facebook, like many companies, had adopted in the interval following the collapse of the Safe Harbor Framework.  Schrems observed that standard clauses – like the Safe Harbor — also excuse a company from its privacy protection obligations when confronted by a foreign national security agency’s demand for personal data.  He therefore claimed that standard clauses were equally deficient from the perspective of EU fundamental rights. His reformulated complaint gradually made its way back to the ECJ.

Thus, the EU court was presented with parallel challenges to the two major data transfer mechanisms in use with the United States, each case posing similar underlying questions about US surveillance law and practices. At the ECJ’s hearing last summer on Schrem’s challenge to standard contract clauses, the lead judge in the case, Thomas von Danwitz of Germany, also posed questions addressing the validity of Privacy Shield. Suddenly the prospect appeared of the ECJ issuing one judgment deciding the US surveillance issues common to both.  US companies which depend on transatlantic data transfers realized they could be facing the perfect storm.

Reckoning Day at the ECJ

In the first stage of deciding an important case like this, a senior court jurist known as an Advocate General (AG) issues an opinion exhaustively analyzing the issues and recommending a resolution. Some months later, the judges release a final judgment, which usually – but not necessarily — follows the AG’s recommendation. The 97-page opinion of AG Henrik Saugmandsgaard Øe of Denmark, issued on December 19, 2019, generated equal measures of relief and alarm for the US government and companies.

Øe first examined whether standard contractual clauses used for transatlantic commercial data transfers measured up to the EU’s fundamental rights standards. He acknowledged that they foresaw the possibility of a foreign data importer being ordered to turn over data to its host government for national security reasons. However, Øe added, the European data exporter, once notified by the foreign importer of the local government’s demand, in turn could ask the relevant EU member state DPA to prohibit the affected data transfer outside the Union from happening.   He therefore advised the judges not to take the “somewhat precipitous” step of reaching a broad conclusion about whether standard clauses sufficiently protected Europeans’ privacy rights until a DPA had had an opportunity to consider the particular circumstances of an NSA demand to Facebook. If the ECJ adopts Øe’s perspective, Facebook and the many other companies using standard clauses in transatlantic commerce will, at a minimum, have bought some time, until national DPAs can assess the clauses’ effectiveness in contested cases.

Had the Advocate General stopped there, his opinion would have been embraced as a reprieve for a principal means of transatlantic data transfers. But Øe then went on to analyze the validity of the Privacy Shield itself, paving the path for Judge von Danwitz and his colleagues to decide the merits of both transatlantic data transfer instruments in one combined judgment, if they so choose.

The AG did find Privacy Shield to be an improvement over the Safe Harbor Framework in certain respects. In particular, he concluded that NSA surveillance conducted under the authority of the Foreign Intelligence Surveillance Act (FISA) did not amount to ‘generalized access’ to the content of electronic communications, since intelligence officials must apply selection and filtering criteria before accessing personal data.  If the ECJ agrees, one of the important factual errors it made in the first Schrems judgment will have been corrected.

However, Øe criticized numerous other features of US surveillance law and of the Privacy Shield. He was alarmed by the US government’s extensive reliance on non-statutory surveillance authorities such as Executive Order 12333.  He similarly was concerned that privacy protections for non-Americans conferred by PPD-28 could be undone by executive fiat (as indeed President Trump was rumored to be considering early in the current Administration).  The AG likewise was unimpressed by the powers of the State Department ombudsperson to operate as an administrative remedy for Europeans, pointing out that the office lacks both investigative powers and independence from the executive branch. It is hard to avoid the conclusion that the Advocate General regards data transfers under the Privacy Shield as failing fully to guarantee EU privacy rights.

The ECJ’s judgment will be handed down on July 16.  Most observers agree that the court will find deficiencies in the transatlantic data transfer regime, but they diverge on how far it will go. Will the judges assess only the validity of standard contract clauses, as the Advocate General urges, or will they go beyond to draw conclusions about the Privacy Shield as well? If the court finds Privacy Shield wanting, will the arrangement effectively be invalidated with immediate effect, as occurred in the case of the Safe Harbor? Or might the ECJ instead grant the European Commission a reasonable interval to renegotiate the Privacy Shield with the United States?

Towards a US Strategy for Ending the Privacy Wars

Ever since the Snowden allegations erupted, American companies have looked in vain for a lasting legal foundation for vital transatlantic commercial data transfers. The US Government’s own frustration also occasionally has emerged into public view. In the wake of the Schrems judgment’s sharp criticism of US surveillance practices, President Obama pointed to the deafening silence from European governments on the important role US intelligence plays in protecting Europe’s national security:

…a number of countries, including some who have loudly criticized the NSA, privately acknowledge that America has special responsibilities as the world’s only superpower; that our intelligence capabilities are critical to meeting these responsibilities; and that they themselves have relied on the information we obtain to protect their own people.

If the ECJ again rules against transatlantic data transfer mechanisms, it is not hard to imagine a US Administration concluding that negotiated solutions with Europe have not worked and turning to a confrontational posture.  It certainly has the tools. The Executive Branch could turn off intelligence sharing with European allies and wait for the yelps from their security services to reach Brussels.  Alternatively, US internet platforms might be quietly urged temporarily to stop providing the services that Europeans daily depend on.

US companies surely would press the Administration to pursue a further negotiated privacy arrangement with the European Union, however.  Some ECJ objections to US surveillance laws could be addressed through Congressional action and reflected in a revised Privacy Shield.  But not all judicial criticisms would have a reasonable prospect of Congressional remedy – so it is important that the court not overreach.

The ECJ might, for example, find that important and long-established US surveillance authorities embedded in executive order rather than statute do not measure up to European fundamental rights norms. The court also could demand specific changes to US bulk surveillance practices, such as the methods the US intelligence community uses for selecting and filtering which tranches of personal data to scrutinize. It is difficult to foresee Congress being sympathetic to such concerns, particularly in the current turbulent era of transatlantic relations. 

The ECJ might well also point to the need for the United States to strengthen the institution of the ombudsperson as an arbiter of Europeans’ complaints about surveillance of their personal data.  Congress should sympathetically consider making the ombudsman independent of executive branch influence and granting it autonomous investigative powers as well.  There is in fact an existing agency within the US government well-suited to take on such a remedial function — the Privacy and Civil Liberties Oversight Board (PCLOB).  Congress could grant the PCLOB, a small but respected independent agency currently charged with privacy oversight of US counter-terrorism laws, the additional authority and resources to scrutinize national security access to personal data transferred to the United States for commercial purposes.

The ECJ additionally may confirm Advocate General Øe’s doubts about the legal durability of PPD-28.  Transforming privacy elements of this directive into the form of a statute would greatly strengthen European confidence that they cannot easily be undone.  Congressman Eric Swalwell (D-CA) in fact proposed this step in an unsuccessful amendment to the 2018 bill reauthorizing Section 702 of the Foreign Intelligence Surveillance Act.  Legislating portions of PPD-28, together with strengthening surveillance oversight by an independent ombudsperson, would go a long way towards overcoming European legal objections to the Privacy Shield and standard contract clauses.

Beyond these concrete steps, the very act of the US Congress passing comprehensive privacy legislation would be persuasive evidence to Europe and the rest of the world that the United States takes seriously key privacy principles such as limits on consent and on use of data, and redress.  Congress in recent years indeed has inquired into the GDPR, taking testimony from leading European privacy regulators about how their experience could inform US comprehensive legislation.

Most importantly, enacting a comprehensive US privacy law would present a credible case to Brussels that transatlantic privacy protections are broadly congruent, even if they inevitably diverge in some respects.  No longer would the US Government be condemned to repeated, piecemeal attempts to disprove alleged deficiencies in its system of privacy protection.  Instead, the EU and the United States finally could develop a definitive regime for transatlantic commercial data transfers based on reciprocal respect for each other’s legal systems.

Congress showed it could exercise global leadership on international data transfers when it enacted the 2018 CLOUD Act to allow law enforcement authorities rapid and efficient access to electronic evidence located abroad.  Foreign authorities may only obtain e-evidence located in the United States if their requests meet due process standards comparable to the rigorous ones of US criminal law.

Ever-larger portions of the future transatlantic economy will run on data flowing in both directions.  If the United States and Europe are definitively to end the privacy wars that intermittently have flared between them, the protections that accompany the transatlantic movement of personal data must become a two-way street as well. 

PPI_Privacy-Wars-Issue-Brief