Press Release: “Even With New Pay-Fors, Bernie’s Agenda Still Has A $25 Trillion Hole”

WASHINGTON— After repeated calls for Bernie Sanders to put pen to paper on the costs for his extraordinary campaign pledges, his magic math simply doesn’t add up.

Ahead of tonight’s Democratic Debate in Charleston, South Carolina, Sen. Bernie Sanders has published a new document where he claims to fully cover the costs of his gargantuan expansions of federal programs. But an independent review by the Progressive Policy Institute finds that these numbers can’t be taken at face value.

“Sanders wants voters to reward him for proposing a left-wing wishlist of spending increases and take him at his word that taxes on billionaires will pay for it, but the math just doesn’t add up,” said Ben Ritz, Director of PPI’s Center for Funding America’s Future. “Sanders has already embraced every tax increase on wealthy Americans imaginable and still comes up several trillions of dollars short.”

Key highlights from Ritz’s analysis include:

  • Sanders has now proposed over $53 trillion of new spending over the next 10 years – an amount that would roughly double the size of the federal government.
  • The document Sanders published last night, along with others released earlier in his campaign, claim to collectively raise less than $43 trillion in new revenue – meaning that he’s at least $10 trillion short. But these revenue projections are well outside the mainstream of what independent analysts estimate.
  • More realistically, if Congress were to adopt every single revenue option Sanders has offered for consideration, it would fall nearly $25 trillion short of his proposed spending increases over the next decade – leaving a gap nearly equal to the total value of all goods and services produced by the U.S. economy in one year.

“At a time when President Trump has plunged the nation into trillion-dollar deficits as far as the eye can see, the worst thing Democrats could do is let him off the hook by nominating a candidate who is promising them the same kind of voodoo economics on a far greater scale,” Ritz said.

As Democrats debate tonight in South Carolina, will the moderators finally press Senator Sanders on whether middle-class and young Americans will be willing to accept the burden of financing a revolution through dramatically higher taxes or a doubling of government debt?

For a complete analysis, read the full article on Forbes.

Ritz for Forbes: “Even With New Pay-Fors, Bernie’s Agenda Still Has A $25 Trillion Hole”

Vermont Sen. Bernie Sanders has made some extraordinary promises in his campaign for president, including free health care, a federal jobs guarantee, universal forgiveness of all student debt, and radical expansions of nearly every government program from Social Security to housing subsidies. When asked at a CNN town hall last night how he would pay for this gargantuan expansion of government, Sen. Sanders presented moderator Chris Cuomo with a new document that Sanders claimed detailed how he would pay for his proposals. But don’t be fooled: these numbers still don’t add up, and Sanders should be pressed to explain his magic math at tonight’s debate.

The first problem is that the list of Sanders’ proposed spending increases is incomplete. Sanders has proposed costly plans for K-12 education, expanding disability insurance, paid family leave, and more that were not accounted for in the new document. He also grossly understates the cost of his Medicare for All plan by citing a flawed analysis that neglected to incorporate the costs of specific benefits Sanders proposes, such as universal coverage for long-term services and supports, and failed to account for how offering universal health-care benefits more generous than those offered by any other country on earth would increase utilization of health services.

Sanders and his surrogates regularly claim that critics are wrong to focus on how much Medicare for All increases government costs because it would reduce the total cost of health care. But independent analyses from the Urban Institute and Committee for a Responsible Federal Budget have concluded that even with the aggressive price controls he has proposed, Sanders’ Medicare-for-All framework would actually increase national health expenditures by up to $7 trillion. Sanders himself also admitted in a 60 minutes interview this weekend that his Medicare-for-All plan would likely cost around $30 trillion, yet the list of “options” Sanders has offered to pay for them (options which, it should be noted, he has never explicitly endorsed enacting together) would together cover less than 60 percent of that amount by the Sanders campaign’s own accounting.

Read the full piece here

Lewis for Newsday: “Finding Common Ground on Net Neutrality”

Even before impeachment gained momentum, Americans overwhelmingly
agreed that our country is “on the wrong track” and disapproved of the
performance of the president and Congress. That’s largely because,
even on issues where there is broad public agreement, the legislative
and executive branches have been unable to find sensible solutions.

Exhibit A is an issue that should be about technology, not ideology:
broadband policy. Over two decades, most Americans have come to agree
about the basic principle of “net neutrality.” That’s the common sense
idea that all internet traffic must be treated equally, and no company
should be able to block or throttle online traffic in order to gain a
competitive leg up.

But still, some progressives insist on all-or-nothing over-regulation
of the internet, while some conservatives contend that the best thing
the federal government can do is nothing at all. Thus, in a textbook
case of the partisans shouting down the pragmatists, Congress has been
unable to craft consensus legislation that would make net neutrality
the law of the land and a source of certainty for consumers, startups
and internet providers.

Read the full op-ed here.

Gold for The Hill: “Is Wall Street more accountable than Major League Baseball?”

It’s too early to predict the fallout from the Houston Astros cheating scandal. But one thing is already clear: The players who participated and drove the signal-stealing scheme will not be fined or suspended. Following an internal investigation, Major League Baseball Commissioner Rob Manfred concluded that with the wide scope of players involved, and the reality that many have now moved to other teams, taking disciplinary action against players would be “difficult and impractical.”

Meanwhile, Citigroup, a global banking behemoth, just suspended the head of its lucrative High Yield Bond division in London for repeatedly skipping out on his lunch bill.

Pushing the envelope to gain an edge has always been ingrained in baseball’s culture, from pine tar to spitballs. Now, with the advent of modern technology and exponentially larger revenue and payrolls, the pressure to cheat is stronger than ever. The same can be said (and quite often has been said by some leading presidential candidates) about Wall Street.

Read the full piece here.

Blog: Trump’s Proposed Budget Would Eliminate the Federal Charter Schools Program

President Trump, in yesterday’s 2021 budget address, called for cutting the U.S. Department of Education budget by 8 percent. That is obviously terrible, but it is, at least, less than the 12 percent he wanted to axe in 2019 or the 10 percent reduction he called for in 2020.

Slashing eight percent of the federal education budget equals a $6.1 billion cut. Trump proposes to convert the lion’s share of that to a federal tax credit of up to $5 billion a year for donations to “scholarship programs.” The “Education Freedom Scholarship” (EFS) would gift individuals and domestic businesses with a federal tax credit for money they give to state-approved scholarship-granting organizations that offer scholarships to private schools, including religious schools. Most of these private schools are not accountable to state governments for their performance, despite accepting the public money.

But Trump’s real 2021 fiscal malpractice is his proposal to collapse all current grant programs into lump sum block grants that states can spend as they see fit. This includes the federal Charter School Program (CSP), which helps fund new chartered public schools.

Charter schools are publicly funded but operated by private organizations, most of them non-profits. They do not charge tuition, and they must be authorized and renewed by a state approved body—usually a government agency, state board of education, local school board, or public university. Almost all are open enrollment, meaning they cannot choose their students and must hold lotteries when demand exceeds space. 

Because they operate free of school district bureaucracy, charters can innovate and design classrooms that meet their students’ needs. Numerous studies have proven that they generate positive results for their students, especially low income, minority children. Most charter teachers choose not to unionize, so the teachers unions detest them, and their attacks have politicized the issue. 

Which brings up an important point about Trump’s timing. This year, 11 states will elect their governor, while 44 states will hold elections for one or both of their legislative houses. Block-granting the federal CSP would pour gasoline on the political fire that has raged over charter schools in the states. By their own reporting, the American Federation of Teachers (AFT) and the National Education Association (NEA) spent a combined $93.3 million on politics in 2017− and that was an off year. In 2020 it is staggering to imagine what they will spend—and the pressure all that money will put on politicians running for office. There couldn’t be a worse moment to dissolve the CSP and turn its resources over to state elected officials. 

The National Alliance for Public Charter Schools says CSP is especially important to small or single-site schools, which have little access to resources. Many of those are run by African-American or Hispanic educators seeking to create alternatives for students trapped in failing inner-city schools that are constrained by bureaucratic rules and inflexible union contracts. If Trump’s budget were to pass as presented, these educators would be cut off at the knees, and the five million students who are on charter school waiting lists would suffer. They would have no choice but to remain trapped in failing schools, or to hope for a voucher and that a private school admitted them. Congress must push back hard against Trump’s disastrous vision for the future of education. 

Blog: Policymakers Should Look to Accelerate the Spread of the App Economy

The failure of the app intended to collect results from the Democratic caucuses in Iowa wasn’t the best advertisement for the App Economy. But we have to remember that apps play a central role in the economy.

As part of a global project measuring the size of the App Economy, we estimated the U.S. App Economy to have 2.246 million App Economy jobs as of April 2019. That’s an increase of 30 percent from our December 2016 estimate of 1.729 million jobs.

Many of them are at large corporations in tech hubs like the Bay Area, New York City, or Austin. But App Economy jobs aren’t exclusive to the tech sector or major cities. In fact, a growing number have seeped into smaller metro to rural areas, the physical industries, as well as startups.

For instance, as of February 2020, small IT firm Four Nodes was hiring a mobile application developer with experience in Android in Camden, Delaware. Kent Displays, which makes e-writing displays, was looking for a mobile app developer in Kent, Ohio. Federal Home Loan Bank of Des Moines was searching for a lead IT service desk analyst with knowledge of Android and iOS in Des Moines, Iowa. Television broadcasting company CBS was seeking a frontend engineer with experience in iOS and or Android development in Louisville, Kentucky.

In terms of App developing companies, Little Rock-based Apptegy is an education technology startup that allows administrators to tailor how they market their school. Leawood, Kansas-based Farmobile allows farmers to collect and share data with agronomists and other farmers. And Fargo, North Dakota-based WalkWise uses a walker attachment to track fitness data and send alerts using its mobile app.

Indeed, the ability to code from anywhere coupled with apps’ integration with the physical world (which accounts for roughly 80 percent of the economy) has democratized opportunity in these areas for businesses and consumers alike. And the Internet of Things, which will enable individuals and companies to use mobile apps to interact with physical objects and processes such as their home, cars, equipment, and warehouses, only promises to increase the interaction between apps and the physical world.

Here are some examples of App Economy jobs in the physical industries: as of February 2020, agricultural merchandiser Tractor Supply Company was hiring a mobile apps IT architect in Brentwood, Tennessee. Medical device company Medtronic was looking for a senior software quality engineer with experience in iOS and Android in Chanhassen, Minnesota. Manufacturing company IDEX was searching for a QA test engineer with knowledge of iOS or Android in Huntsville, Alabama. As of January 2020, ecommerce company SupplyHouse.com was seeking a senior Android developer in Melville, New York.

From this perspective, apps play a critical role in spreading the information revolution beyond the traditional metro hubs and tech sector. They serve as an important means to unlocking growth for smaller metro and rural areas, the physical industries, and startups.

Marshall for NY Daily News: “Mayor Pete’s cross-cutting appeal: Why Buttigieg is really the one to watch”

Sen. Bernie Sanders narrowly took first in the New Hampshire primary, and Sen. Amy Klobuchar rode a wave of last-minute support to a surprisingly strong third-place finish. But the prize for most impressive performance goes to Mayor Pete Buttigieg, who came in second. More than the other candidates, he displayed the kind of broad, cross-cutting support the Democrats’ eventual nominee will need to unite a fractious party.

The outcome left the campaigns of Sen. Elizabeth Warren and former Vice President Joe Biden on life support. They finished fourth and fifth respectively, and picked up zero delegates. Two longshots, Sen. Michael Bennet and entrepreneur Andrew Yang, packed it in yesterday after barely registering in New Hampshire.

Following a lackluster showing in Iowa, Warren appears to be the “betwixt and between” candidate — neither the favorite of liberals nor moderates. Nor has she done particularly well with her presumed base of college-educated women. At this stage, it’s hard to see what she could do to start clicking with these voters.

Biden’s precipitous fall from frontrunner status suggests that his high national poll numbers may have reflected familiarity more than popularity. However, they did allow him to clog the center lane, blocking the way of other moderate candidates. If Biden doesn’t win a solid majority of black voters in South Carolina, he’s done.

Read the full piece here.

Ritz for Forbes: “Trump’s Busted Election-Year Budget”

After signing nearly $5 trillion of new debt into law since taking office, President Trump’s Fiscal Year 2021 budget proposal provides the clearest look yet at how he intends to govern if re-elected in November. The ironically titled “Budget for America’s Future” is anything but: it proposes to slash critical public investments that lay the foundation for long-term growth, double down on reckless tax cuts for the rich, undermine health-care and safety-net programs for millions of Americans, and leave the nation on a path of trillion-dollar deficits as far as the eye can see.

The Trump administration claims its proposals would put the federal budget on a path to balance by 2035, but this relies upon economic assumptions that are downright absurd. The Office of Management and Budget projects real gross domestic product will grow more than a full percentage point faster than does the non-partisan Congressional Budget Office every single year between 2020 and the end of the projection period. That annual difference may not sound like a lot, but it adds up: the Trump administration’s fiscal estimates depend on the U.S. economy producing nearly $25 trillion more in output over the next decade than CBO projected in its most recent budget and economic outlook.

These outlandish economic growth projections enable the Trump administration to claim that it will raise $3.1 trillion more in revenue over the next decade relative to CBO’s baseline, when in reality the administration is proposing tax cuts that would actually reduce revenue. Trump proposes to extend the individual income tax cuts created by the GOP’s 2017 tax law past their scheduled expiration in 2025. But interestingly, even as Trump proposes to extend tax cuts for wealthy individuals, his budget would not extend the few expiring business provisions that some economists believe could potentially increase domestic business investment. This omission is further evidence that Trump is underestimating the cost of his policies while overestimating the boost they would give to economic growth.

Read the full piece here.

A New Chapter: The Neoliberal Project Joins PPI

Nearly three years ago, the earliest iteration of the Neoliberal Project came about. It was in the form of a forum where economics undergraduate students could gather to discuss economics and the policy implications of the field. We called the forum r/neoliberal. We didn’t name our forum that to make a political statement from the outset, but because we wanted to poke fun at people who had previously called us that word. But quickly, people began joining at a far greater rate than we ever expected. They weren’t joining to discuss econometrics, as we originally intended. People were joining because they desired a place to discuss policymaking online that wasn’t captured by left or right-wing populists. We were radical incrementalists – as we called ourselves – and it was different from anything else out there. We knew we were onto something, and created the Neoliberal Project to launch new initiatives and house them all under one banner. 

Since then, we have launched a Twitter account that now boasts 34k followers, a meetup network in 20 cities with thousands of attendees, a podcast with over a quarter of million downloads, dozens of Facebook groups and Exponents, our magazine and newsletter. We ran the Neoliberal Project with next to no money for much of its existence. Website and travel expenses had to come out of our own pockets. Everyone who has contributed to the Neoliberal Project up until this point as done so as a volunteer. I’m eternally grateful to those people, who are the only reason where we here today.

I’m proud to announce a new chapter of the Neoliberal Project today. Today, we are officially joining the Progressive Policy Institute (PPI). PPI is a storied think tank based in Washington, DC that traces it origin back as the brain trust of the Bill Clinton administration and now works with pragmatic Democrats to solve today’s toughest solutions. 

RELEASE: Young Neoliberals Link Up With PPI

WASHINGTON— The Neoliberal Project, a fast-growing network of young pragmatists, is joining forces with the Progressive Policy Institute.

“Over the last several years, we have built the Neoliberal Project into an online community of politically engaged young individuals who are pushing back against the ideological extremes that put our country in peril,” said Colin Mortimer, the Neoliberal Project’s executive director.

“Now we are proud to join one of the most storied think tanks in the country, as we develop and advocate for a radically pragmatic agenda for change our country so urgently needs,” he added.

The Neoliberal Project attracts the next generation of people who identify with the liberal values on which America has built the world’s most vibrant and diverse democracy: competitive markets, robust public investment, a strong welfare state, and social pluralism and tolerance. Previously a part-time volunteer organization, the Project boasts a Twitter account with 34,000 followers, meetup networks in 20 cities, a podcast with over a quarter of million downloads, dozens of Facebook groups and pages and Exponents, a magazine and newsletter.

“PPI is thrilled to team up with the Neoliberal Project,” said Will Marshall, President of PPI. “The Neoliberal Project brings a fresh voice to the nation’s political conversation — thousands of enterprising thinkers, writers, and doers who are determined to lean against the forces that our polarizing America. They fill a vacuum in our politics for a pragmatically liberal alternative to right-wing populism and democratic socialism.”

Adds PPI Executive Vice President Lindsay Lewis, “The Neoliberal Project has created a grassroots network of new leaders to support and reinforce the work of like-minded political leaders at all levels of government.”

Colin Mortimer joins PPI as Director of the Neoliberal Project and economic policy analyst, alongside Jeremiah Johnson, director of the project’s podcast and digital programming, who joins as a non-resident PPI Fellow.

For more background and details, read this post on Medium. CONTACT: media@ppionline.org, 202-525-3926

###

The Progressive Policy Institute is a catalyst for policy innovation and political reform based in Washington, D.C. Its mission is to create radically pragmatic ideas for moving America beyond ideological and partisan deadlock.

Founded in 1989, PPI started as the intellectual home of the New Democrats and earned a reputation as President Bill Clinton’s “idea mill.” Many of its mold-breaking ideas have been translated into public policy and law and have influenced international efforts to modernize progressive politics.

Today, PPI is developing fresh proposals for stimulating U.S. economic innovation and growth; equipping all Americans with the skills and assets that social mobility in the knowledge economy requires; modernizing an overly bureaucratic and centralized public sector; and defending liberal democracy in a dangerous world.

Cuomo Scores Win-Win with Tipped Wage Rule

In a perfect example of unintended consequences, restaurant workers are pushing back against a nationwide campaign by labor advocates intended to raise their wages. They worry that the advocates’ push will cost them more in lost tips than they’ll gain in mandated wage increases – and cut their income overall. 

These workers have found an ally in New York Governor Andrew Cuomo, who has come up with a sensible compromise that strikes a balance between overdue increases in the minimum wage and protecting workers who rely on tips.

Under federal law the minimum “cash wage” for tipped workers is $2.13 an hour, with tips making up the rest of workers’ pay. If tips don’t bring the worker up to the full federal or state minimum wage (whichever is higher), the employer is required by law to make up the rest. However, advocates’ “One Fair Wage” campaign aims to eliminate the tipped wage at the state level. 

Seven states – California, Nevada, Alaska, Oregon, Washington, Montana, and Minnesota – have eliminated the tipped wage, requiring employers to pay the full minimum wage plus tips. This has drawn furious protests from both restaurant workers and owners, who say it means lower pay and lost jobs. 

A 2018 survey by restaurant platform Upserve found that workers overwhelmingly – by 97 percent – prefer the tipped system to the full minimum wage. In Maine and Washington, D.C., restaurant workers led efforts to reverse laws passed under pressure from the One Fair Wage campaign. 

Enter Governor Cuomo. In December, Cuomo’s Labor Department issued an order eliminating the tipped wage for some service sector occupations such as nail salon workers, hairdressers, and valet parking attendants, while retaining it for the restaurant industry. Cuomo’s rationale was to combat wage theft in those industries with the highest risk, while preserving the tipped wage system for restaurant workers who earn more than they would receiving the full minimum wage.

It’s been a popular move. Data from the Bureau of Labor Statistics show the annual median wage of waiters and waitresses, including tips, to be higher in New York than every state that has eliminated the tipped wage, and the annual median wage of bartenders to be higher in six of the seven states.

As PPI wrote in 2018, studies have shown that raising the tipped wage does not increase wages for restaurant workers because diners often end up tipping less. For instance, Census Bureau economist Maggie Jones found that raising the tipped minimum wage “increase[s] that portion of wages paid by employers, but decrease[s] tip income by a similar percentage.” Concern about declining tips and lower wages is why many restaurant workers have opposed an increase in the tipped minimum wage. 

Restaurateurs also favor the tipped wage, as it enables owners to succeed in an industry with notoriously razor thin profit margins of 3 to 5 percent. Many owners cite having to close or cut hours (and thus wages) if faced with higher labor costs from raising or eliminating the tipped wage. When San Francisco increased its minimum wage from $13 an hour to $14 an hour in July 2017, bar owner Miles Palliser was forced to close after 5 years. “I think that the dramatic rise in minimum wage definitely affected us at the Corner Store and probably all three of our places in some fashion,” he told the San Francisco Chronicle at the time.

Governor Cuomo’s compromise is a win-win for both restaurant workers and owners. Other states should follow New York’s example.

Statement on the Passing of James “Jim” Kiss

“The PPI community mourns the death last week of Jim Kiss. Jim was “present at the creation” of PPI in 1989. He served not only as a founding member of our Board of Trustees but also as an enthusiastic recruiter of other prominent figures. Jim was the quintessential “New Democrat” – optimistic, forward-looking, pragmatically progressive and a fervent believer in the power of ideas to change the nation’s political trajectory.  The gregarious kid from Philadelphia loved baseball and the Democratic Party and carried on until the end a lively conversation about politics with a wide network of highly accomplished friends and admirers.

I was lucky to count Jim as both a friend and a mentor in the arts of public relations and communications. We at PPI will miss him, and we extend our condolences to Jim’s beloved wife, Jeanne Marie, and many friends in his adopted state of Georgia.”

Will Marshall, PPI President and Founder

Marshall for The Daily Beast: “Who’s Cheering for Bernie Sanders to Win Monday? Young Lefties-and Donald Trump”

Senate Republicans turned President Trump’s impeachment trial into a farcical exercise in partisan whitewashing. That leaves the job of canceling Trump’s reality show presidency to U.S. voters.

A heavy responsibility thus lies on Democratic caucus and primary voters as they start selecting their party’s nominee next week. If they make the wrong choice, it means four more years of Trump’s corrosive assaults on reason, democracy, and basic human decency. For many, the right choice will require setting aside their ideological druthers and picking the candidate most likely to beat Trump in the Electoral College.

It’s hard to know at this point which candidate is most electable. It’s easier to say who isn’t—and Sen. Bernie Sanders tops the list. Despite the devotion he inspires among young left-wing activists, the self-avowed socialist is too far outside the U.S. political mainstream to be considered anything but the longest of long shots against Trump.

Read the full op-ed here.

Low-Income Borrowers and the Auto Loan Market

Executive Summary

Some are concerned that subprime auto loans – which offer higher interest loans to riskier borrowers – pose a threat to the stability of the global economy in much the same way that the subprime mortgage market contributed to the Great Recession. Democratic presidential candidate Elizabeth Warren, in particular, has raised the warning flags as part of her campaign. But these worries are ill-founded and based on misleading data and faulty analogies.

In particular:

  • Auto loans account for a relatively small percentage of the increase in nonfinancial debt over the past five years;
  • Americans are spending less of their budgets on car purchases today, including finance charges, than they were before the recession;
  • Low-income households saw motor vehicle purchases and finance charges fall from 8.5 percent of household budgets in 2000 to 4.9 percent in 2018;
  • Over the past five years, the share of new auto loans going to low-credit borrowers has remained relatively constant. There are no signs that low-credit borrowers are either being frozen out of the market or becoming too large a share of loans;
  • Newly delinquent auto loans, as a percentage of current balances, have been falling over the past two years; and
  • Subprime auto loans differ significantly from subprime mortgages in key respects that make them less likely to pose a serious threat to financial stability

Risk-based pricing of auto loans appears to be working so far, keeping low-income borrowers in the market without driving up delinquencies or to low-income consumers, while not posing the same risk that the subprime mortgage market.

Introduction

To purchase a vehicle, Americans with low or non-existent credit scores often use auto loans with higher interest rates than loans to prime borrowers. Some market watchers have indicated concern about “subprime” auto-loan trends and the potential for a crisis similar to the subprime mortgage crisis that heralded the last recession.

The subprime mortgages and the related mortgage-backed bonds remain the classic case of a poorly executed financial innovation. The initial impetus behind the idea was a good one. Housing is a key element of middle-class wealth, so expanding the system of mortgage finance to help lower-income households buy homes seemed like a positive. However, the subprime mortgages and bonds were designed in such a way that they assumed rising housing prices. When housing prices started to fall, the subprime mortgage system collapsed and contributed to the financial crisis.

Will subprime auto loans create the same problems? In a recent essay, Democratic presidential candidate Senator Elizabeth Warren raised the warning flag:

Auto loan debt is the highest it has ever been since we started tracking it nearly 20 years ago, and a record 7 million Americans are behind on their auto loans — many of which have similar abusive characteristics as pre-crash subprime mortgages1 .

Warren is not alone in her worries. In late 2016, for example, the Office of the Comptroller of the Currency warned that auto-lending risk was increasing and that banks (and other investors in securitized assets) did not have sufficient risk-management policies in place. Fed Governor Lael Brainard pointed to subprime auto lending as an area of concern in a May 2017 speech, while analysts worried about “deep subprime” auto loans2. Some groups used the term “predatory” auto lending.3

But these concerns are misplaced. As we will show later in this paper, the statistic cited by Senator Warren does not reflect the current state of the auto loan market, as it includes old loans from much weaker economic times. Perhaps most fundamental to understanding the problem with drawing a parallel between the mortgage crisis and today is the fact that subprime mortgages and subprime auto loans are very different products.

Naturally, lower-income households with low credit scores or limited credit history may have fewer financial resources and be inherently riskier borrowers. Moreover, the fact that motor vehicles depreciate over time means that the collateral for the loan becomes less valuable.

Nevertheless, the ability to own a car and, therefore, access credit is crucial for this population. Risk-based pricing charges low- rated borrowers higher interest rates, but in return, offers them the opportunity to borrow money to buy a vehicle that might otherwise be financially inaccessible.

For many lower-income households, their vehicle is the single biggest asset they own.

While vehicles do not appreciate in value as homes do, vehicles are income-producing assets in the sense that they are often essential for commuting to work, especially in non-urban areas. As one report noted, “Owning a car is the price of admission to the economy and society in much of America.”4

 In this paper, we analyze the auto loan market, paying particular attention to auto loans made to low-income Americans and to people with bad credit. We find that:

  • Auto loans account for a relatively small percentage of the increase in nonfinancial debt over the past five years;
  • Americans are spending less of their budgets on car purchases today, including finance charges, than they were before the recession;
  • Low-income households saw motor vehicle purchases and finance charges fall from 8.5 percent of household budgets in 2000 to 4.9 percent in 2018;
  • Over the past five years, the share of new auto loans going to low-credit borrowers has remained relatively constant. There are no signs that low-credit borrowers are either being frozen out of the market or becoming too large a share of loans;
  • Newly delinquent auto loans, as a percentage of current balances, have been falling over the past two years; and
  • Subprime auto loans differ significantly from subprime mortgages in key respects that make them less likely to pose a serious threat to financial stability.

Risk-based pricing of auto loans appears to be working so far, keeping low-income borrowers in the market without driving up delinquencies or threatening the financial system. We conclude that the subprime auto loan market is beneficial to low-income consumers, while not posing the same risk that the subprime mortgage market did before the financial crisis. While it will be instructive to observe subprime auto loan trends going forward, current trends do not indicate significant instability concerns in this market.

Recent Patterns in Debt Accumulation

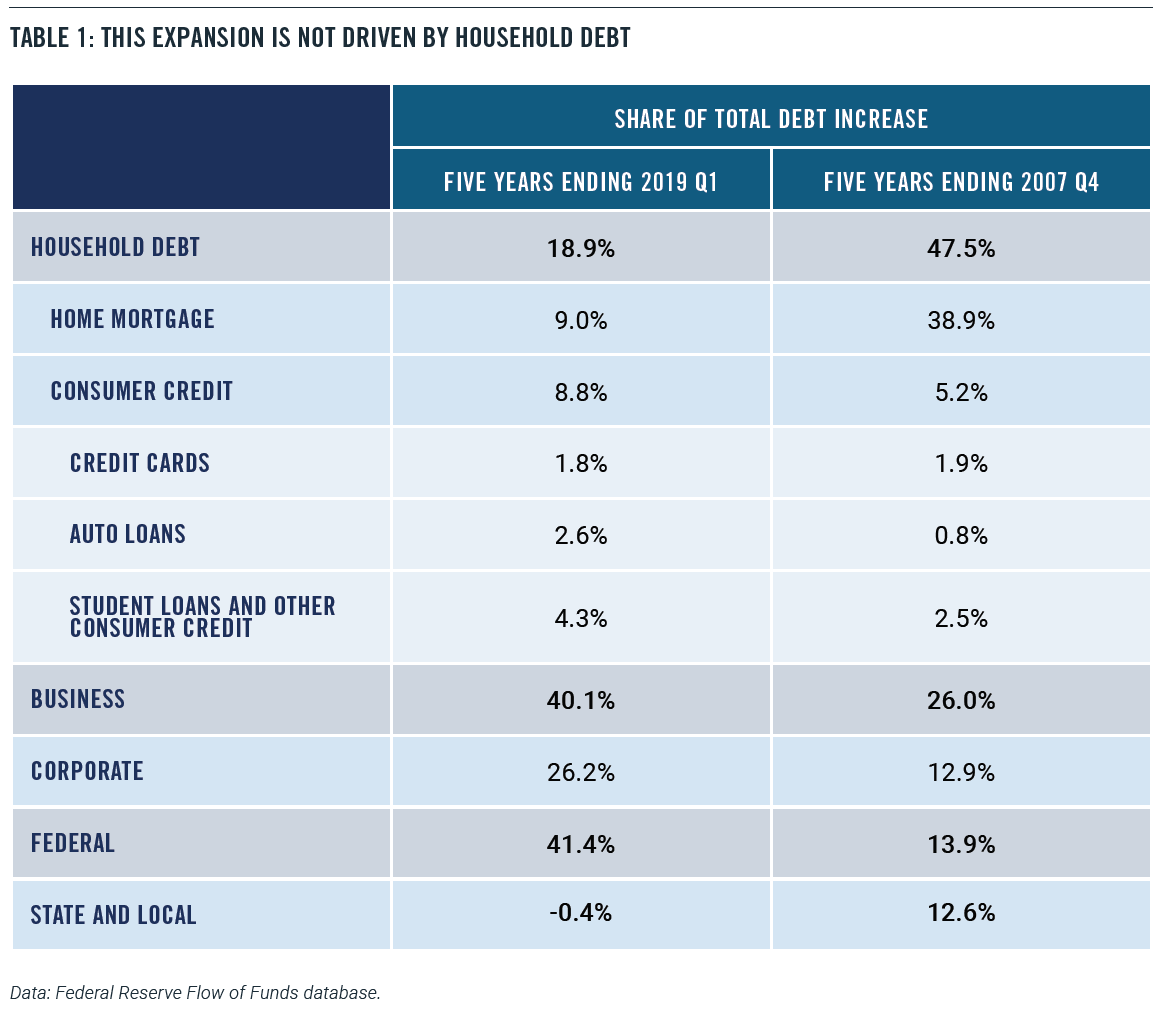
Recent patterns in debt accumulation are very different from those that preceded the financial crisis and Great Recession. Non-mortgage consumer credit – including auto loans, credit cards, and student debt – has risen by $900 billion over the past five years, according to Federal Reserve data. While that figure sounds substantial, that increase amounts to less than 9 percent of the total increase in domestic nonfinancial debt – that is, all debt except borrowing by financial institutions. The rise in consumer borrowing is dwarfed by the increase in business debt ($4.1 trillion) and federal debt ($4.2 trillion) over the same period. Those two categories together account for 82 percent of the increase in domestic nonfinancial debt (Table 1). The leading contributors to business debt growth are mortgages and corporate bonds.

Indeed, businesses have taken the greatest advantage of low-interest rates. Nonfinancial corporations have almost doubled their outstanding corporate bonds since the end of 2007 when the last recession started. Meanwhile, household debt has risen by only 10 percent.

Taking home mortgages into account, households have only accounted for 19 percent of the increase in domestic nonfinancial debt since 2014. By contrast, in the five years leading up to the Great Recession, households accounted for 48 percent of the debt increase. In other words, the financial boom in the pre-recession years was heavily driven by household borrowing, while households have only contributed a small portion to the current debt increase.
A skeptic could argue that, given derivatives and financial engineering, it’s possible for a relatively small portion of the debt market to drive an outsize increase in risk for the whole system. Indeed, that’s what happened ahead of the 2008 financial crisis. In May 2007, then-Chairman of the Federal Reserve Ben Bernanke famously said, “We believe the effect of the troubles in the subprime sector on the broader housing market will be limited, and we do not expect significant spillovers from the subprime market to the rest of the economy or to the financial system.”5 At the time, the value of subprime mortgages was about $1.3 trillion, which was only 10 percent of the mortgage market and an even smaller share of total borrowing. Bernanke and other policymakers figured that the problems in subprime mortgages could be easily contained.

What Bernanke and others failed to reckon with, however, was how the subprime mortgages had been designed to make sense only in a rising real estate market. Subprime mortgages were constructed effectively to subsidize interest rates with the possibility of appreciation. These financial instruments would offer low upfront rates that enabled lower-income borrowers to qualify. When the teaser rates eventually reset to much higher levels, the assumption was that the borrower could refinance into a new mortgage.

Moreover, the subprime mortgages were then securitized and used to build complicated financial derivative products. And when the subprime mortgages failed because of declining home prices, so did the derivatives. In other words, problems in a relatively small financial sector could be amplified and have a much larger effect on the rest of the economy.

Despite this concern, there is evidence to suggest that subprime auto lending is not a substantial risk to the broader economy. Auto loans are only 7.4% of household debt, which is the 40-year historical average.6 Moreover, the auto asset-backed securities (ABS) market is likewise dwarfed by the mortgage-backed securities (MBS) market. As of the second quarter of 2019, there was a mere $264 billion in auto-related securities, which included only $55 billion in subprime auto securities. By comparison, the amount of outstanding mortgage-related securities came to almost $10 trillion.7

Further, subprime auto loans don’t work the same way that subprime mortgage loans did in the pre-crisis era. Cars and trucks depreciate steadily over time, so the value of the collateral diminishes. That means lenders can’t afford to offer teaser rates, or excessive levels of negative equity, to buyers with low credit scores. They must charge higher rates, properly pricing risk. As one article put it, “the very nature of a real estate loan is very different from an auto loan. Real estate is an investment that typically appreciates over time. During the bubble years, consumers and lenders falsely believed appreciation would bail them out from poor judgment. Vehicles, on the other hand, depreciate. There is no false hope of higher values in the future to bail out a borrower or a lender.”8

The Auto Market

Despite the relatively small role that consumer debt is playing in the current debt expansion, some people can’t shake the idea that Americans are over-spending and over-borrowing to maintain a particular lifestyle. Consider this quote from an April 2019 piece from Business Insider:

The fact that America’s top-selling vehicle — a Ford truck with a price starting at nearly $30,000 – and many like it cost nearly half the median household income hasn’t stopped people from buying them and hasn’t stopped lenders from facilitating loans.9

Over the past five years, the price of new motor vehicles has risen by only 1.1 percent, according to estimates by the Bureau of Economic Analysis (BEA).10 By contrast, the overall price level of consumer goods and services have risen by 6.7 percent over the same stretch.11 In other words, the relative price of new motor vehicles has fallen over this period.

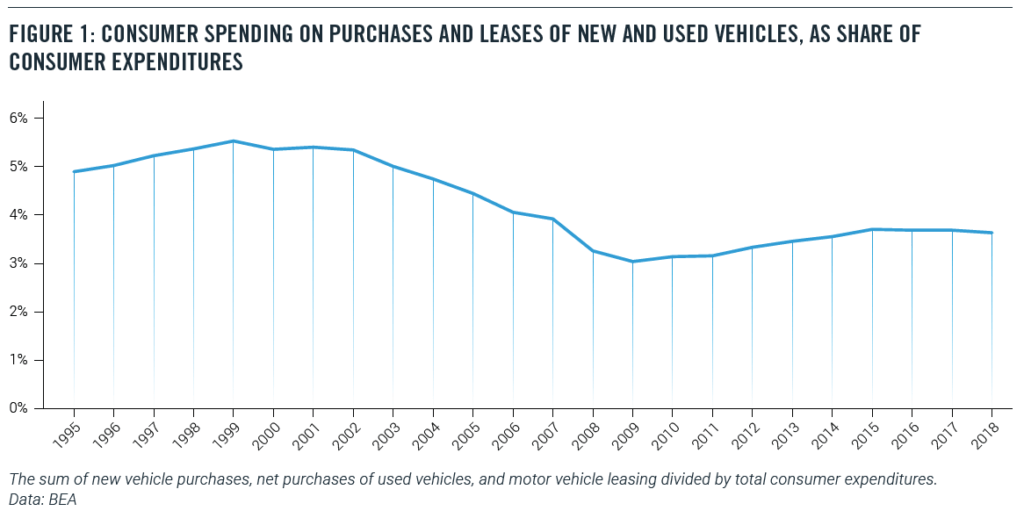
Not surprisingly, the share of consumer spending on new and used vehicles has fallen as well. In 2000, 5.4 percent of consumer spending went to purchases and leases of new and used vehicles. Today, that share is down to 3.6 percent (Figure 1).12
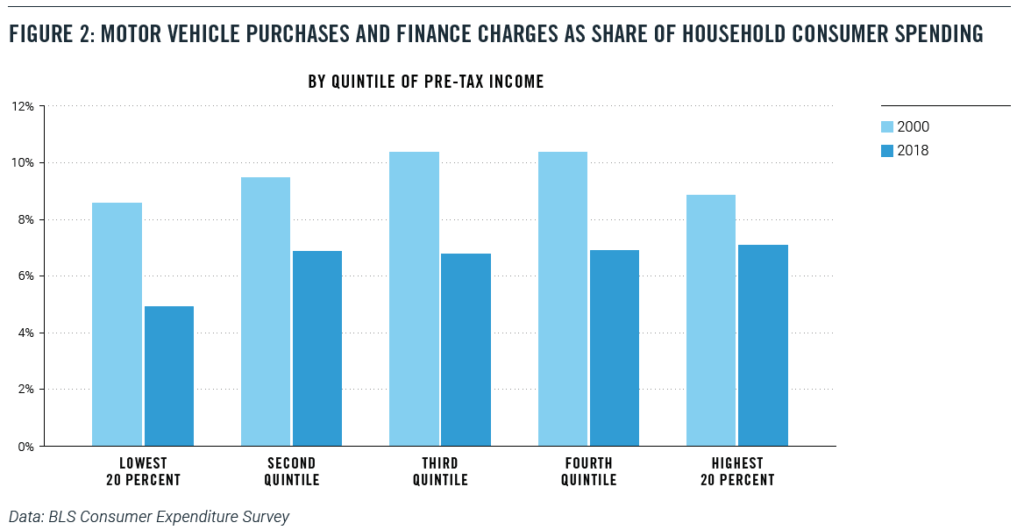
The BLS Consumer Expenditure Survey tells the same story. In 2000, motor vehicle purchases and finance charges amounted to 9.7 percent of household outlays. As of 2018, the last year for which full data is available, the share of vehicle purchases and finance charges fell to only 6.7 percent of household outlays.13 In part, this decline may represent a lengthening of the term of auto loans.14 (These figures would not be changed much by including automobile lease-related payments, which amount to about 10 percent of automobile purchase-related payments in 2018.)

The State of the Low-Income Auto Market

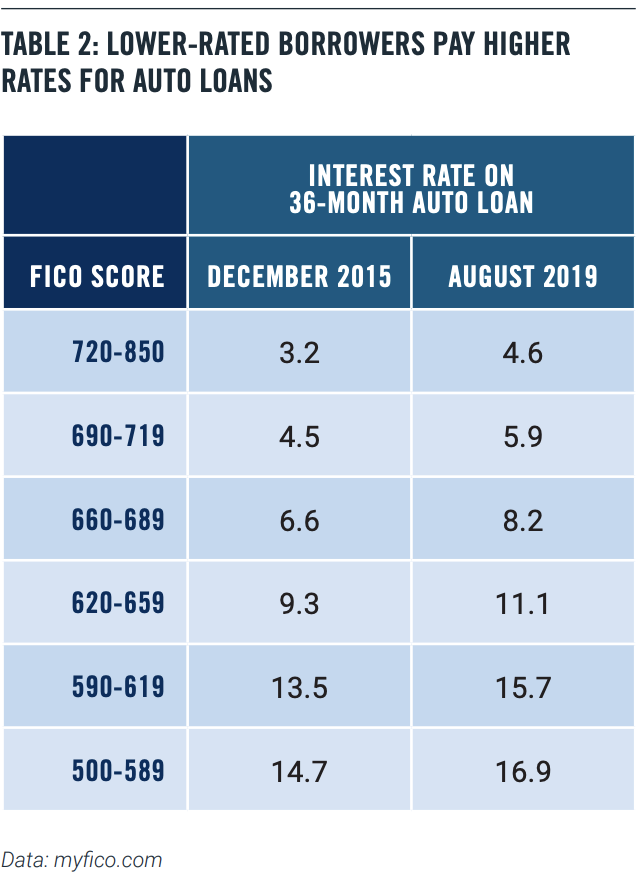
It’s not surprising that lower-rated borrowers pay more for their auto loans. Table 2 below shows interest rates for a 36-month new car loan at different credit rates for December 2015, which was close to the bottom of the credit cycle, and August 2019 (Table 2).

We can see that rates have risen for all credit-rating levels, but more so for the low-rated borrowers.

This risk-based pricing means that low-rated borrowers are not frozen out of the auto loan market. That’s good news, since, in many parts of the country, a car or truck is a necessity, even for low-income households. There is little or no public transit outside of densely populated urban areas, and ride-sharing services are not viable alternatives in many places. So, it is unsurprising that the share of low-income (the bottom quintile) households with a vehicle hold steady at 66 percent in both 2000 and 2018.

At the same time, low-income households saw motor-vehicle purchase and finance taking a smaller share of their budgets. In the bottom quintile of pre-tax income, motor vehicle purchases and finance charges fell from 8.5 percent of household budgets in 2000 to 4.9 percent in 2018 (Figure 2), a drop of almost four percentage points.15

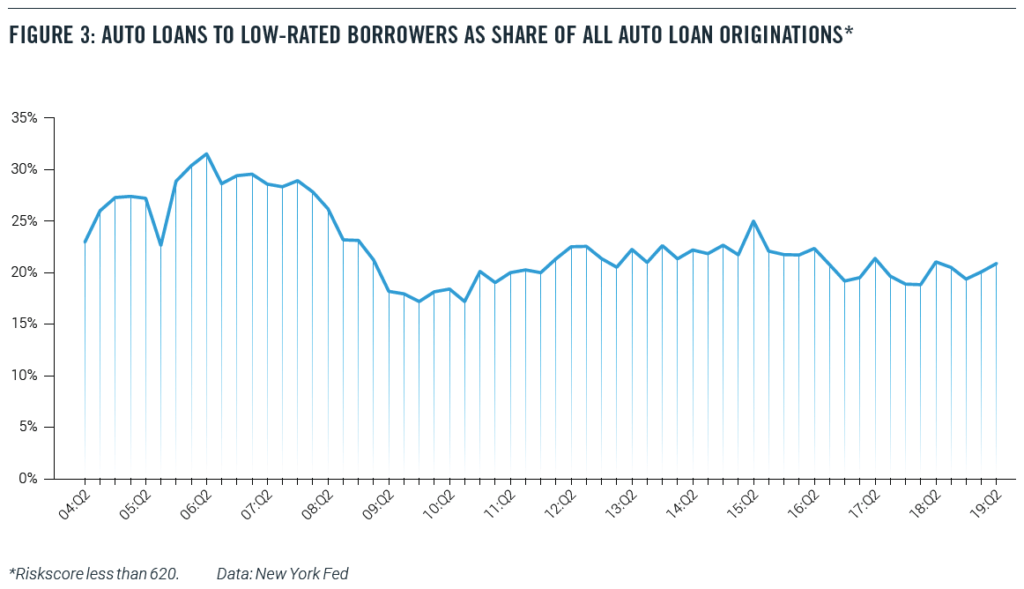
Similar data from the New York Fed’s Household Debt and Credit Report confirm that low-income households are not being uniquely stressed financially by automobile borrowing. Figure 3 shows the share of all auto loan originations that are going to low-rated borrowers (with a Riskscore of less than 620). Before the financial crisis, about 30 percent of new auto loans were going to low-rate borrowers, a startlingly high percentage. That share fell to 20 percent after the crisis and shows no signs of rising (Figure 3).16

The biggest piece of negative news has come from the New York Federal Reserve’s well-publicized finding in February 2019:

…(T)here were over 7 million Americans with auto loans that were 90 or more days delinquent at the end of 2018. That is more than a million more troubled borrowers than there had been at the end of 2010 when the overall delinquency rates were at their worst since auto loans are now more prevalent.18

This startling number, while impressive, simply doesn’t mean what it seems to suggest. This figure includes anyone who still has an old, bad auto loan on their credit record, even if the loan was made and written off years earlier.19 In fact, even after the lender writes off the loan, the loan servicer could continue to report the account to the credit bureaus.

The recent economic history of the United States helps to explain this figure. The number of nonfarm jobs did not return to pre-recession levels until 2014, while the employment-population ratio for Americans with a high school diploma but no college did not bottom out until 2015. As a result, today’s subprime borrowers are carrying around bad loans from the days when the labor market for less-educated workers was still struggling.

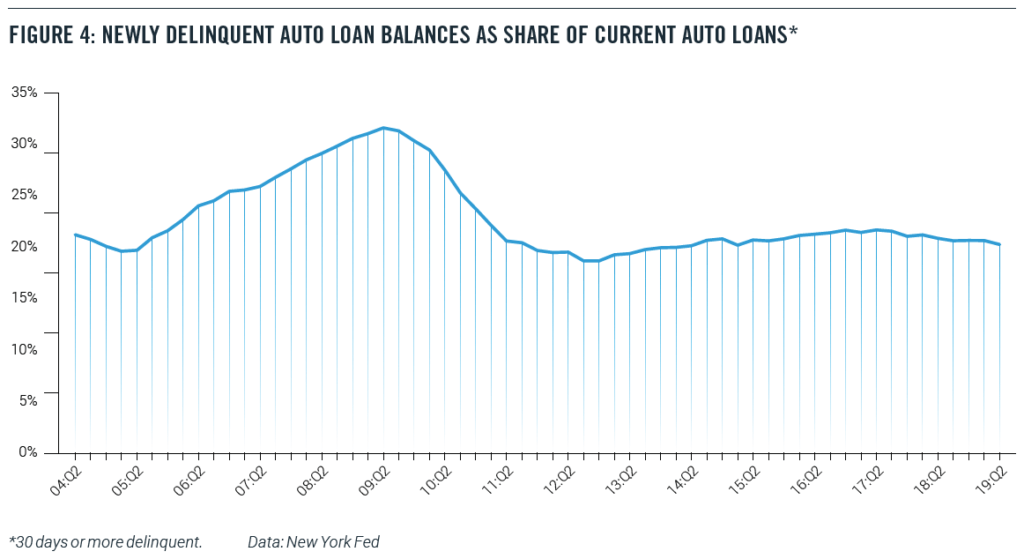
Indeed, in an August 2019 blog item, New York Fed economists recommend that anyone interested in the current performance of debt should look at the transition into delinquency- that is, a chart such as Figure 4.20 And by that measure, auto loans are doing far better than in the pre-recession years.

Conclusion

In the event of a recession or a significant economic slowdown, auto loan delinquencies will predictably rise. Subprime auto borrowers, who are more likely to have fewer resources, will be likely to fall behind in their payments when times turn bad.

Nevertheless, a careful look at the data does not suggest that either the origination of subprime auto loans or the exposure of the broader macroeconomy to the auto loan market is a cause for concern. In particular, the subprime auto-loan market looks nothing like the mortgage market before the Great Recession.

Newly delinquent auto loans, as a percentage of current balances, have been falling over the past two years, and the fact that a record number of Americans have a bad auto loan on their credit record is a testimony to economic history more than current loan practices and economic conditions, particularly given the rapid rise in total car sales during this period.

Indeed, risk-based pricing in the auto loan market appears to be supplying a steady flow of credit to low-rated borrowers without imposing excess stress on the financial system.

About the Authors

Michael Mandel is Chief Economic Strategist of the Progressive Policy Institute.

Douglas Holtz-Eakin is President of the American Action Forum.

Thomas Wade is Director of Financial Services Policy of the American Action Forum.
 

Mandel for RealClearPolicy: “Do Subprime Auto Loans Threaten the U.S. Economy?”

With partisan divisions as deep as ever, both sides can agree on one thing: Everybody wants to avoid another financial crisis. And forecasters have recently identified subprime auto loans as an existential threat to the economy.

The headlines are eye-catching and scary: “A $45,000 Loan for a $27,000 Ride: More Borrowers Are Going Underwater on Car Loans,” “Underwater: Consumers Are Treating Cars A Lot Like Houses During The Subprime Mortgage Crisis,” and more of the same. But is it true? Are subprime auto loans the new financial cancer threatening households and the economy, much like the subprime mortgage crisis did in 2007?

No.

Worries about subprime auto loans — which offer higher interest loans to riskier borrowers — are ill-founded and based on misleading data and faulty analogies, our new research finds.

Read the full op-ed here.

Bledsoe for USA Today: “Don’t fuel Donald Trump’s culture war on climate change. Beat it instead.”

Australia’s raging infernos, like our Western wildfires and more devastating storms, prefigure a darker climate future for all of us without urgent action. But for President Donald Trump, the climate crisis is just another opportunity to stoke anger among the American people and further divide us.

Trump has undermined every climate protection possible, not out of any philosophical conviction about smaller government, but in large part to deliberately provoke outrage on the left, and then use the limelight to falsely portray climate-protecting policies to his base as a culture war waged by left-wing elitists against average voters.

Earlier this month, it was a White House event where he announced proposals to weaken climate protections in the National Environmental Policy Act. In fact, NEPA could benefit from reasonable reforms — not the ones Trump proposes, but, for instance, allowing the siting of clean energy infrastructure needed to rapidly cut greenhouse gas emissions. But in Trump World, creating contempt for climate protection itself, like slurring immigrants or race-baiting rhetoric, is a key ingredient in the toxic stew of cultural resentment he pre-cooks in search of alienated voters hungry for scapegoats.

Read the full piece here.