Why the Tech Boom Has Not Yet Entered Bubble-land

There seems to be a theory going around that the current tech boom has entered into bubble territory. In a piece entitled “Is the dot com bubble about to burst?”, one journalist wrote:

Sometimes, when a love affair ends, you can’t remember what it was you ever saw in someone in the first place. That is the feeling right now of a lot of once-amorous investors who breathlessly wooed Facebook at its flotation in May and paid $38 for the privilege of a share in the social network.

And certainly some other tech stocks have been disappointing to investors, including Zynga and Pandora. Indeed, some skeptical  spirits have pointed to the surge in the venture capital investments as a sign that the top is here.

But let’s be serious. While the tech boom will likely enter Bubble-land eventually, we are nowhere near that point. I will offer three reasons. First, as long as the big telecom companies are still pouring billions into extending the capabilities of their  high speed mobile networks,  there will be new apps to develop and new companies to start.  Indeed, we have not yet seen an iPhone with 4G connections.

Continue reading “Why the Tech Boom Has Not Yet Entered Bubble-land” →

The Big Companies Betting On America: AT&T And Verizon Lead The Way

PPI’s popular summer policy brief, Investment Heroes, was picked up this week over at Forbes with analysis and commentary from Diana Carew. Carew explains how capital investments designed to increase efficiency still create jobs, points to foreign companies that would have made the list, and makes the case for a more positive view of Apple’s spending.
For all the talk about the trillions sitting on the balance sheets of the biggest U.S. companies, you might think that the S&P 500 is sitting on its hands and waiting for sunnier skies before investing capital.

The truth is rather different though, and a July report from the Progressive Policy Institute explains that capital investment, a critical means of growth for the economy, is hardly at a dead stop.

According to PPI, while the level of business investment remains below its 2007 peak, there are still companies shelling out hard-earned cash for new buildings, equipment and software. The think tank’s report lists 25 “Investment Heroes,” or companies that are pumping billions of dollars into the U.S. economy through their capital expenditures.

Looking over the list one thing becomes immediately clear: capital-intensive industries like telecom and energy are still spending. AT&T and Verizon Communications top PPI’s list, which drew on 2011 financial reports and regulatory filings by 150 of the biggest companies in the U.S.  with $20.1 billion and $16.2 billion in capital expenditures respectively. Exxon Mobil comes in third, with$11.7 billion, followed by Wal-Mart ($8.2 billion) and Intel ($7.4 billion).

Read the entire story HERE.

Move Over Demand, Make Room for Investment

It’s become conventional wisdom: when the economy falters, it’s because people aren’t spending. Give people money and they will spend their troubles away (and our troubles, thanks to the money multiplier).  Everyone is a winner. This advice is at the top of campaign trail talking points. It has been given by economists ranging from Bruce Bartlett and Paul Krugman to Ben Bernanke.

But what if that isn’t the whole story – the government has spent hundreds of billions in a series of stimulus measures aimed at consumers and it hasn’t been enough.  Growth is painfully slow and today’s jobs report shows we are still not creating enough jobs–163,000 in July–to absorb recessionary losses. So what’s going on – was the stimulus too little?  Is demand being unusually stubborn?

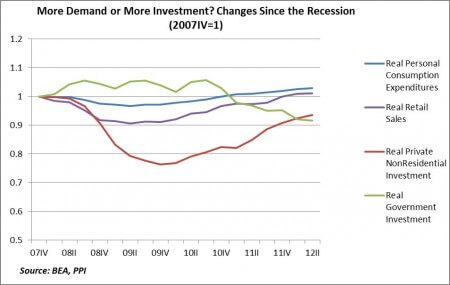
We’re missing something: it’s not only about demand; it’s also about investment. And the July 2012 annual revision to GDP confirms we are in an investment drought.  The graph below tells the story.

Halfway into 2012, real nonresidential private investment is still 7% below its pre-recessionary level. And after initially increasing, real government investment is now almost 10% below its pre-recession level – and falling. Meanwhile, demand appears to be doing fine. Both real personal consumption expenditures (PCE) and real retail sales, two commonly used measures of consumer demand, have fully recovered from the recession – and then some.

Continue reading “Move Over Demand, Make Room for Investment” →

Election Watch: Texas and Georgia Go Conservative, Presidential Race Drags On

There were two state primaries on July 31, in Georgia and Texas (actually a runoff for candidates failing to secure a majority in May). The latter got the lion’s share of national attention, with the predictable if not universally predicted victory of former state solicitor general Ted Cruz over Lt. Gov. David Dewhurst for the GOP Senate nomination.
Cruz won easily (57-43), overcoming a major financial disadvantage, Dewhurst’s universal name ID (he’s been in his statewide post for 10 years), and his opponent’s strong backing from most Texas Republican officials, most notably Gov. Rick Perry and two candidates dispatched from the field in May (Dallas Mayor Tom Leppert and former SMU, NFL and ESPN star Craig James). While most observers interpreted the results via the familiar template of Tea Party Insurgent Defeats Moderate Establishment Pol, what made the race fascinating was that Dewhurst was an unlikely target for an ideological purge.  A self-described “constitutional conservative” with strong backing from Texas business and social-conservative groups, about the only “heresy” he could be credibly accused of was a record of occasional negotiations with Democrats in the Texas legislature. But that was enough: Cruz’s vast array of out-of-state backers (e.g., the Club for Growth, Jim DeMint’s Senate Conservative Fund, various Tea Party groups, Sarah Palin) argued that weak-kneed Beltway Republicans needed to be sent another message against any compromise with Democrats on the difficult fiscal issues expected to come up immediately following the November elections—win or lose.

Another interpretation is simply that the line separating “true conservatives” from just regular conservatives is continuing to move to the Right. Cruz is notable for embracing some of the odder memes of the Tea Party Movement, such as the demonization of any sort of controls on economic development as emanating from a United Nations-led conspiracy dating back to the adoption of a vague “Agenda 21” at the Rio conference on sustainable development back in 1992 (this has been a particular obsession of the John Birch Society, but has inspired actual legislation in Alabama and pops up regularly in state and local GOP party platforms). Continue reading “Election Watch: Texas and Georgia Go Conservative, Presidential Race Drags On” →

WaPo Wrong on Principal Reduction

The Washington Post waded into the principal reduction battle yesterday, endorsing Federal Housing Finance Agency Acting Director Edward DeMarco’s refusal to allow Fannie Mae and Freddie Mac to write down principal balances on delinquent underwater mortgages. The Post editorial endorsed what is a fatally flawed assessment by FHFA of the large potential savings to taxpayers from a carefully crafted program to reduce principal balances for delinquent underwater borrowers.

FHFA’s “analysis” of the presumed risks and rewards of principal reduction appears to be aimed at justifying the hard line that DeMarco and Fannie and Freddie have drawn against granting principal forgiveness in any form other than through short sales. In fact, both Fannie and Freddie, with FHFA’s approval, have recently moved to ramp up their short sales volumes. In a short sale transaction, the homeowner sells her house for less than the amount owed on her mortgage and the lender accepts the net sales proceeds without requiring additional payment. This is a forgiveness of mortgage principal that is equal to the amount by which the mortgage loan balance exceeded the net sales proceeds. Why principal writedowns are allowed in the form of short sales, but not in any other form, simply is incomprehensible. Continue reading “WaPo Wrong on Principal Reduction” →

Why Bill Gross is Wrong: Innovation and Long-term Returns on Equity

Editor’s Note: This item is cross-posted from Innovation and Growth. 

Bill Gross of Pimco has just written a piece where he argues that the real return on stocks in the future will be much lower than the long-term historical average of 6.6%:

Yet the 6.6% real return belied a commonsensical flaw much like that of a chain letter or yes – a Ponzi scheme. If wealth or real GDP was only being created at an annual rate of 3.5% over the same period of time, then somehow stockholders must be skimming 3% off the top each and every year. If an economy’s GDP could only provide 3.5% more goods and services per year, then how could one segment (stockholders) so consistently profit at the expense of the others (lenders, laborers and government)?

He then goes on to argue that:

The Siegel constant of 6.6% real appreciation, therefore, is an historical freak, a mutation likely never to be seen again as far as we mortals are concerned.

In a world of slow innovation, Gross is likely to be correct.  The economy grows slowly, and it becomes difficult to justify compensating risk capital if risks are not paying off.

The calculation changes, however, if we have big disruptive innovations. Big disruptive innovations offer risk on both the upside and the downside. On the upside, disruptive innovations create a wave of high-growth companies that drive the stock market higher. On the downside, disruptive innovations offer the distinct possibility of driving existing companies out of business, once again accentuating risk. Continue reading “Why Bill Gross is Wrong: Innovation and Long-term Returns on Equity” →

Home Economics: Pressure Mounting for Principal Reduction

U.S. Treasury Secretary Tim Geithner has added his voice to the growing chorus calling on U.S. housing regulators to help “underwater” homeowners dig out from under a mountain of negative equity.

Geithner fired off a letter yesterday to Edward DeMarco, acting director of the Federal Housing Finance Agency (FHFA), deploring his agency’s continued opposition to “principal reduction.” He urged DeMarco to reverse his decision not to allow Fannie Mae and Freddie Mac to write down the principal on mortgages held by distressed homeowners.

The day before, FHFA had reaffirmed its stance against principal reduction as a way to reduce costly foreclosures. DeMarco worries that principal reduction would encourage “strategic defaults,” meaning that underwater borrowers would stop making payments on their loans to qualify for a write down. With taxpayers already footing the bill for Fannie and Freddie to the tune of $180 billion, DeMarco is understandably wary of running the bill even higher.

But Geithner believes that reducing loan balances could save money, “the use of targeted principal reduction by the GSEs would provide much needed help to a significant number of troubled homeowners, help repair the nation’s housing market, and result in a net benefit to taxpapers.”

I think Geithner has the better argument. In fact, PPI recently published a creative proposal by Rick Morris, a former Fannie Mae executive, to test the potential of principal reduction as another tool, along with refinancing to help homeowners take advantage of rock-bottom interest rates, for preventing foreclosures.

“Fannie and Freddie can offer “short sales” back to the existing homeowners in return for a share of their home equity,” says Morris in ‘Another Tool in the Toolkit: Short Sales to Existing Homeowners.’ “Unlike foreclosure and traditional short sales, which are to third parties and usually at a discount to true market value, this approach would help support home prices, lower future default risk, and save taxpayers billions of dollars.”

We hope DeMarco will reconsider. But what’s really needed is explicit authorization from Congress to engage in the kind of demonstration project that Morris envisions. This will limit taxpayers’ exposure, while exploring new ways to speed the recovery of U.S. housing markets. Unfortunately, the timing of DeMarco’s decision, right before a five-week recess, probably means that throwing a lifeline to homeowners via principal reduction will be shelved until after the election.

Photo Credit: Lauren Wellicome

Mitt Romney’s Vapid Foreign Policy

PPI’s Will Marshall detailed Mitt Romney’s recent adventure in the world of foreign policy over at The American Interest.  Romney was able to stumble his way through a trip to Britain, Israel, and Poland all while offering very little in the form of substantive policies focusing more on criticisms of President Obama’s foreign policy.

Mitt Romney’s midsummer foray into foreign policy has left Democrats giddy with schadenfreude. More than his stumbling performance abroad, however, it’s the substance of Romney’s views that ought to really give voters pause.

Or, more precisely, lack of substance. With less than 100 days to go, Romney has yet to develop a coherent outlook on U.S. security and leadership in a networked world. What we get instead is GOP boilerplate about American greatness and exceptionalism, and a pastiche of spaghetti-against-the wall criticisms of Obama’s foreign policy.

Romney, of course, wants the election to center on the economy, and he’s offering himself, in effect, as a more experienced and capable CEO. His missteps over the past week, however, raise doubts about his ability to take over as Commander in Chief.

The sequence began with his first major foreign policy address, to the Veterans of Foreign Affairs. It was a pedestrian affair that left even conservative commentators underwhelmed, when they bothered to comment on it at all. Next, Romney embarked on his Grand Tour of three U.S. allies—Britain, Israel and Poland—supposedly dissed by Obama. The point of the exercise was to show that Romney knows how to treat America’s best friends.

Read the entire article HERE 

Photo Credit: Austen Hufford

Election Watch: Ad War Heats Up, Romney Goes Abroad

The last week has continued the earlier pattern of daily fireworks in the presidential contest (excepting a brief pause in hostilities immediately after the Aurora massacre), but little if any significant movement in the polls. As anyone near a battleground state television can attest, the Obama campaign (and the Priorities USA super PAC) has continued harsh personal attacks on Mitt Romney as an out-of-touch rich man with no emotional connection with the middle class or interest in its aspirations, who is furthermore determined to cut taxes for people like him. The Romney campaign (which is now beginning to get advertising reinforcement from the very deep pockets of conservative super PACs) has responded harshly with a battery of ads and campaign speeches focusing on a clip from an Obama speech in Roanoke wherein he supposedly disrespected the personal contributions to the economy of entrepreneurs (in fact he was paraphrasing a well-known litany by Massachusetts Senate candidate Elizabeth Warren about the reliance of private businesses on public services and investments). It’s not entirely clear whether this intense barrage is intended simply to reinforce the general and long-standing Republican critique of Obama as someone who does not understand how the economy works and believes government is the source of all good things, or is more narrowly targeted at undermining Obama’s relatively strong standing with upscale, college-educated voters.

Continue reading “Election Watch: Ad War Heats Up, Romney Goes Abroad” →

Can American Idol Tell Us if Young People are Going Back to Work?

Economists are constantly coming up with offbeat and fun economic indicators. We’ve seen the economy explained through hemlines, long-distance relationships and even the toughness of marine recruiting ads.

In this spirit, let me unveil a new indicator—the American Idol indicator.

This indicator uses the number people attending Idol auditions each year to tell us if younger workers are more discouraged about their employment prospects. The idea here is that people are more likely to go to an AI audition if they have a lot of time on their hands – presumably because they are unemployed, underemployed, or have given up looking for a job. So a rise in the number of auditions might correspond to a rise in the unemployment rate, while a drop in auditions might signal things are getting better.

As it turns out, PPI’s American Idol indicator suggests younger workers are feeling better about their employment prospects over the coming months. The graph below compares the unemployment rate of workers aged 16-29 with the number of American Idol auditions since 2007. Rules of AI auditions stipulate contestants must be American citizens that are between the ages of 15-28.

Continue reading “Can American Idol Tell Us if Young People are Going Back to Work?” →

Election Watch: Romney Fights Bain Allegations, Minority Vote in Question

Despite the languorous weather and the decamping of many Americans to Vacationland, the election season is staying lively, and will probably remain so at least until the Olympics begin on July 27.

At the presidential level, there has been a notable contrast between the two campaigns and parties, and very stable polling. The main pro-Obama Super-PAC, Priorities USA, has been conducting heavy battleground state advertising pounding Mitt Romney for Bain Capital’s alleged outsourcing activities and (most recently) for his failure to release more than partial tax returns for just the two most recent years. The president and other Democrats have joined in through earned media outlets. The apparent strategy is to fatally undermine Romney’s use of his business background as a credential for the presidency, and then to go after the controversial GOP policy agenda encompassed in the Ryan Budget, which Romney has embraced. This two-pronged approach is being supplemented by a party-wide effort to make expiration of the Bush tax cuts for those earning over $250,000 a year (which has been polling quite well) as a litmus-test issue separating the two parties decisively.

Continue reading “Election Watch: Romney Fights Bain Allegations, Minority Vote in Question” →

GOP Guts Teen Pregnancy Prevention

If U.S. conservatives have made any useful contribution to anti-poverty policy, it’s driving home this crucial point: family structure matters. The whole vicious cycle of intergenerational poverty usually begins with teen pregnancy and unwed births.
Yet House Republicans this week proposed to gut federal programs that aim at reducing teen pregnancies. How do conservatives square their antipathy to such programs with their understanding of the risks and disadvantages of growing up in poor families headed by unmarried mothers?

You might think the answer is obvious: Mistrustful of government in general, Republicans don’t believe it knows how to do anything as complicated as promoting responsible sexual behavior.  Ok, but the same Republicans who called for cutting spending on prevention programs also voted to boost spending on federal abstinence programs.

So let me get this straight: Republicans believe that Washington is hopelessly incompetent when it comes to encouraging young girls to take every precaution against an unwanted pregnancy, but masterful in persuading them not to have sex at all. There’s little evidence to support this view, but in the GOP of Norquist and Bachmann, facts are no match for dogma.

Continue reading “GOP Guts Teen Pregnancy Prevention” →

PPI Battleground Home Value Index: Prices Will Only Increase From Here

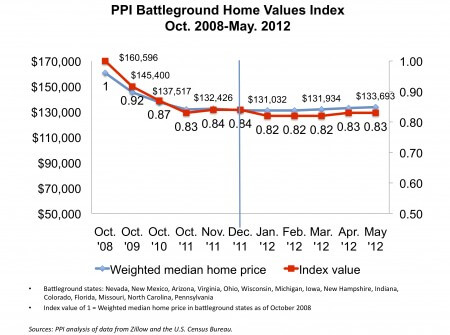
PPI’s monthly look at home values in 16 potential 2012 battleground states–our Battleground Home Values Index, May ’12– confirms values have bottomed, and are now showing price appreciation in the states that will decide the winner of the 2012 Presidential elections. This is welcome news for not only homeowners in battleground states, but for homeowners nationwide. With a clear bottom in values established, the “Big 3” of the housing crisis, Nevada, Arizona and Florida, have all seen prices move to the upside since the end of 2011, with Arizona experiencing a strong 4% move up.

Some Good News That Obama Should Be Touting

Will Marshall compiled four positive economic stories for Real Clear Politics that President Obama should be making better use of in his campaign for re-election. From farming to exports there are positive signs in the economy according to Marshall.

Despite a string of doleful job and sales reports, there are signs that America is starting to get its productive mojo working again. The good news can’t come fast enough for President Obama, who needs some economic success stories he can point to.

So, at the risk of diverting readers from the cosmically important question of when, exactly, Mitt Romney stopped running Bain Capital, let’s examine four pinpricks of light that have begun to penetrate the economic gloom:

First, check out America’s phenomenally productive farmers; Monday’s Washington Post notes that the agriculture sector last year sold $136 billion worth of goods abroad, boosting farm income to a record $98 billion. When it comes to high quality and affordable food, America is still number one in the world.

But, in a perfect example of the disjuncture between what’s happening in the real world and Washington’s thralldom to entrenched interests, Congress is cooking up new justifications for costly federal subsidies for the thriving agricultural sector. The culprits include supposedly fiscally conservative Republicans, who added callousness to hypocrisy by also voting to slash food stamps for poor families.

Read the entire article HERE

Let’s Kill the Mortgage Interest Deduction and Replace It With This

10.2011-Gold-Kim_HomeK_Accounts-A_Down_Payment_on_Homeownership_and_Retirement

The Atlantic highlights PPI’s proposal to create “HomeK” accounts for home buyers to aid in the purchase of new homes. The article further suggests that such accounts could replace mortgage interest deductions.

The mortgage interest deduction probably isn’t going anywhere soon. Voters are far too fond of it, and politicians are loathe to nix a popular sort-of-kind-of-middle-class entitlement. But while the tax break might be beloved by the people who actually show up on election day, it’s also a highly regressive giveaway to the top 20 percent of American households, who reap 75 percent of the benefit, as my colleague Matt O’Brien wrote yesterday.

So let’s say policy wonks could wave a magic wand and make the mortgage interest deduction disappear. How could we replace the thing? Even though everyone has sobered up a bit about it thanks housing bust, home ownership still has a lot of economic virtues we should want to encourage. For instance, it’s one of the few ways a large portion of this country actually saves. And we really don’t want Americans saving any less than they already are.

Read the entire article HERE.

Another Tool in the Toolkit: Short Sales to Existing Homeowners

Overview

Edward DeMarco, acting director of the Federal Housing Finance Agency (FHFA), is drawing fire from congressional Democrats for preventing Fannie Mae and Freddie Mac from writing down the principal on home mortgages held by underwater borrowers. With U.S. taxpayers already on the hook for nearly $200 billion in losses incurred by Fannie and Freddie since September 2008, DeMarco understandably doesn’t want to make a bad situation worse.

The lawmakers, however, have a point. The housing slump may be the most significant brake on America’s economic recovery. That’s why it’s worth experimenting with creative ways to help delinquent underwater homeowners dig out from under a mountain of “negative equity.”

Private sector experiences suggest that a carefully conceived principal reduction program could achieve significant savings for U.S. taxpayers by reducing losses at Fannie Mae and Freddie Mac. Such a program could be enacted responsibly and fairly without fueling moral hazard—the risk that borrowers who otherwise would make their mortgage payments go delinquent in an effort to get their principal balances reduced.

In effect, Fannie and Freddie can offer “short sales” back to the existing homeowners in return for a share of their home equity. Unlike foreclosure and traditional short sales, which are to third parties and usually at a discount to true market value, this approach would help support home prices, lower future default risk, and save taxpayers billions of dollars.

I propose that FHFA direct Fannie Mae and/or Freddie Mac to conduct a pilot program to test the technique’s viability and that Congress ask the Congressional Budget Office (CBO) to independently assess the potential savings for U.S. taxpayers should such a program be implemented on a full-scale basis.

The Principal Matter

Foreclosures are very expensive for lenders. In addition to the large costs of carrying, maintaining, and oftentimes improving homes they have foreclosed upon, disposing of the properties in foreclosure sales typically nets less than their fair market value. Similarly, short sales to third parties also usually suffer “distressed sale” discounts to the homes’ fair values. According to the latest LPS Home Price Index data, in today’s depressed real estate markets, foreclosed homes sell at an average discount of 29 percent and short sales at an average discount of 23 percent. And, of course, having on ongoing supply of such properties for sale adds pressure on home prices.

To avoid foreclosures, and thereby minimize their losses, many banks have already reduced principal balances on mortgage loans that they own. They have done this in two ways: by reducing the balances of outstanding mortgages through loan modifications, and by agreeing to short sales of homes which result in the borrowers’ loan obligations going away. In a short sale transaction, the bank lets the borrower sell her home for less than the mortgage loan balance without requiring her to repay the difference. This is a principal writedown for the borrower—it is equal to the amount by which the mortgage loan balance exceeded the sale price of the home in the short sale transaction.

Fannie Mae and Freddie Mac already provide underwater borrowers with relief on mortgage principal by allowing short sales of homes. In fact, both of the government-sponsored enterprises (GSEs) recently announced plans to streamline their short sales processes in order to stimulate the use of the technique. If they and FHFA are comfortable with granting principal reduction through short sales, then they must believe that doing so minimizes losses.

So the debate should not be about whether principal reduction per se can help minimize losses. It does. Rather, we should determine whether there is a better way to implement principal writedowns in order to reduce losses further for the GSEs without also creating meaningful additional moral hazard. Doing short sales of their homes to delinquent underwater homeowners, with them sacrificing some home equity as a cost, has the potential to save the GSEs (and, consequently, U.S. taxpayers) billions of dollars without stimulating moral hazard.

Download the entire report.